Enterprise Financial Misses As Credit Costs Offset Strong Loan Growth And A Firm 4.30% Margin
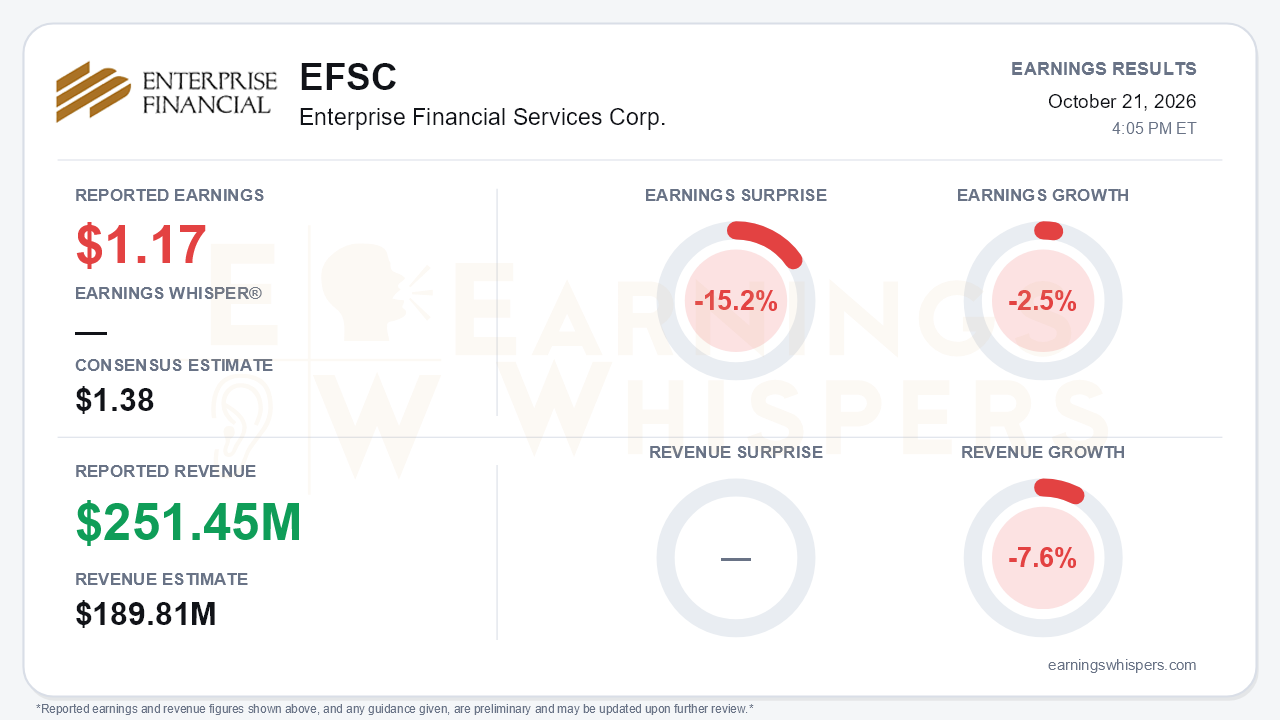
Enterprise Financial Services Corp. (NASDAQ: EFSC) delivered a third quarter in which the core banking engine ran well but credit costs swallowed much of the progress. Adjusted earnings of $1.17 per share missed the $1.38 consensus by 15.2% and fell 2.5% from a year ago. GAAP EPS was $1.14. Results improved sequentially from $1.13 in the second quarter, but remained well below the $1.30 to $1.36 run rate of the prior two quarters. That is the central tension: balance-sheet growth and margin stability are real, while asset quality and tangible capital moved the wrong way.
The revenue picture needs careful reading. Earnings Whispers puts revenue at $251.45 million, 32.5% above the $189.81 million consensus but down 7.6% year over year. The size of that beat appears to reflect a broader revenue definition that includes gross interest income, rather than a true operating surprise. The company's own core revenue was $192.5 million, up from $187.4 million in the linked quarter. The year-over-year decline is largely an artifact of the prior-year quarter, which included $32.1 million of anticipated insurance proceeds tied to a solar tax credit recapture.
The underlying spread business is healthier than the EPS miss suggests:
- **Net interest income** rose $5.9 million sequentially to $174.6 million.
- **Pre-provision net revenue** climbed to $74.6 million, from $68.2 million in the second quarter and $65.6 million a year ago.
- **Net interest margin** held at 4.30%.
- **Core efficiency ratio** improved to 58.9% from 61.1%.
- **Loans** grew $452.3 million in the quarter, led by construction, life insurance premium financing and investor-owned commercial real estate.
- **Deposits** grew $624.4 million, with noninterest-bearing balances holding at 33% of the total.
The quality of the quarter deserves scrutiny below the pre-provision line:
- **Provision.** The provision rose to $18.1 million, from $14.2 million last quarter and $8.4 million a year ago.
- **Charge-offs.** Net charge-offs were 36 basis points annualized, including a $7.0 million Missouri C&I loss.
- **Problem assets.** Nonperforming assets climbed to 1.03% of assets from 0.92%. The increase was driven by $18.0 million of agricultural loans moving to nonaccrual, a $15.5 million CRE foreclosure and smaller C&I and CRE credits. Repossessed property now totals $95.6 million.
- **Reserves.** The allowance stayed at 1.17% of loans even as nonperforming loans rose, so coverage slipped to 165.6% from 182.9%.
- **Workout costs.** Loan, legal and foreclosure costs pushed other expense up 6%.
- **Fee income.** Tax credit losses widened to $5.0 million. The quarter was also helped by $3.8 million of rental income from foreclosed properties, which is not a durable revenue stream.
We did not have management's third-quarter call commentary, so forward context comes from the release and the company's second-quarter remarks. On that call, management guided the margin to the mid-to-upper 4.20s, and the 4.30% result sits at the top of that range. September exit rates show a 6.47% loan yield against a 1.57% deposit cost, and new originations came in at 6.61%. Management also reaffirmed mid-single-digit annual loan growth, and year-to-date loan growth of roughly 4.6% keeps that target in reach. The second-quarter call also flagged risks that remain live:
- the delayed sale of Southern California foreclosed property due to a bankruptcy appeal;
- competitive loan pricing;
- higher construction costs slowing projects.
This quarter's agricultural nonaccruals add a new pocket of concern.
Capital is the other development investors cannot ignore. Rising rates widened unrealized securities losses to $367 million. As a result, tangible book value fell to $39.45 from $42.30, and tangible common equity to tangible assets dropped to 8.13% from 9.04%. Adjusted for held-to-maturity losses, that ratio is 7.63%. Regulatory ratios remain well-capitalized. Even so, the company repurchased 525,767 shares at an average $64.74, above both the quarter-end price of $58.95 and the current $60.25. It also raised the dividend to $0.36. Bears have legitimate ammunition in questioning the timing of those buybacks as tangible capital thinned.
The market has largely been waiting for clarity. Shares are up just 1.1% since the open following the July report and sit 0.2% below the 200-day moving average of $60.36. The Earnings Whispers price and AVWAP trend readings remain negative. Investor sentiment improved only fractionally, from -0.231 to -0.222, and remains negative. Expectations were not elevated going in, which may limit the damage from the miss but offers no clear catalyst.
The bottom line is that Enterprise is growing loans, deposits and pre-provision earnings at a respectable clip with a stable 4.30% margin. However, rising problem assets, a heavier provision and an 8% drop in tangible book value overshadowed that progress. Until nonperforming assets stabilize and the foreclosed-property overhang begins to clear, the franchise's earning power is likely to keep being discounted by credit concerns.
Read our earnings preview for Enterprise Financial Services Corp.: https://www.earningswhispers.com/article/EFSC/20449
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-09 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-10 | |
| Apr-24 | |
| Apr-23 | |
| Apr-22 |
