Popular Beats On Earnings, But A Second Charge-Off Guidance Hike And A Loan-Growth Cut Temper The Quarter
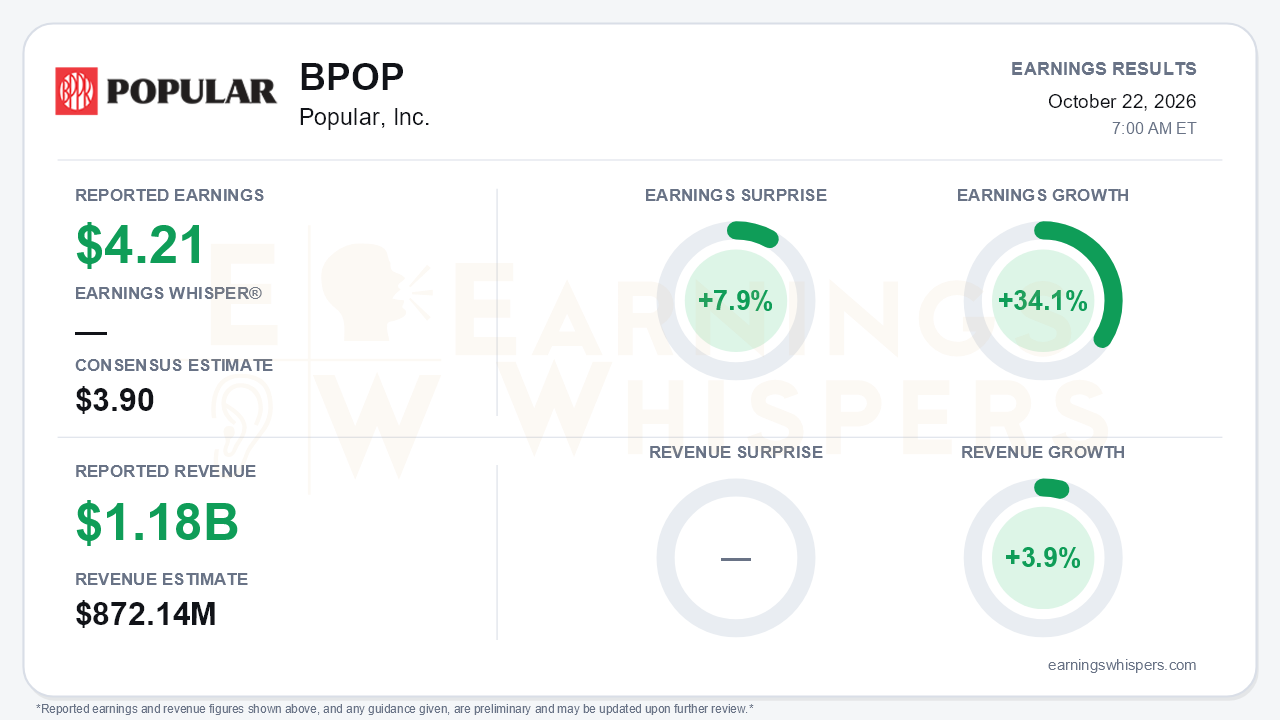
Popular, Inc. (NASDAQ: BPOP) earned $4.21 per share in the third quarter, beating the $3.90 consensus by 7.9% and growing 34.1% from a year ago. Reported revenue of $1.182 billion beat the $872.14 million consensus by 35.6% and rose 3.9% year over year. The beat is real, but this was a step back from a very strong second quarter. EPS slipped from $4.35, ROTCE fell from 17.02% to 15.80%, and management raised full-year net charge-off guidance for the second consecutive quarter while cutting loan growth. The central tension is a spread-income engine still running well against a credit and loan-growth outlook that keeps getting revised the wrong way.
The quality of the beat deserves some scrutiny. The 34.1% annual earnings growth is flattered by an easy comparison, since the year-ago quarter carried a $13 million goodwill impairment. The revenue comparison also warrants context. Net interest income of $699 million plus non-interest income of $176 million came to roughly $875 million, close to the consensus figure. On that core basis, the quarter looks more in line than spectacular.
Sequentially, the drivers were mixed:
- Net interest income rose $6 million, though one extra day contributed about that much.
- GAAP net interest margin slipped 3 basis points to 3.63%, as deposit costs rose 7 basis points to 1.64% on higher, more expensive Puerto Rico public deposits.
- Fees fell 3%.
- Operating expenses jumped 4%, largely on merit increases and performance-linked profit sharing.
- A lower provision helped cushion the decline.
Credit is where bears have legitimate ammunition. The net charge-off ratio did fall to 0.73% from 1.05%. That improvement mostly reflects a $71 million commercial charge-off in the second quarter that did not repeat. Underneath, a new $74 million C&I loan went to non-accrual, and a $34 million partial charge-off was taken on a second-quarter non-performer that the call identified as a telecom credit. Non-performing loans rose to 1.16% from 1.04%, and allowance coverage of NPLs dropped to 165% from 190%. Full-year charge-off guidance now stands at 80-90 basis points, up from 65-80 basis points last quarter and 55-70 basis points originally. That range implies roughly 100 basis points in the fourth quarter. Management called the commercial problems borrower-specific, and consumer and mortgage credit remain clean, with net recoveries in mortgage. Still, two straight increases weaken the argument that the problems are isolated.
The growth narrative also cooled:
- 2026 loan growth was cut to about 2% from the low end of 3-4%, reflecting weaker auto and lease activity, relationship discipline in the U.S., construction payoffs and fewer large Puerto Rico deals.
- Loan yields declined for the first time in the cycle on the call's measure, as the mix shifted away from higher-yielding auto loans.
- A new zero-fee deposit product will cost an estimated $8-10 million in annual fees.
- Puerto Rico unemployment ticked up to 6.2% from 5.8%.
The call's tone moved from last quarter's "nowhere near peak" framing toward loan growth converging with Puerto Rico GDP.
The call preserved a credible earnings story, however. Full-year net interest income growth held at about 8.5%, supported by Treasury reinvestment yields near 4.3%, versus 3.9% last quarter. Expense growth was trimmed to about 2%, even including maximum profit sharing, helped by roughly $50 million of recurring efficiencies that management expects to drive positive operating leverage in 2027. The fourth-quarter fee guide of about $170 million sits above the earlier $160-165 million quarterly range. Capital return is the other pillar. The bank repurchased $179 million of stock, raised the dividend 20% to $0.90, and guided to $150-200 million of quarterly buybacks through 2027, all from a 16.06% CET1 ratio. An initial 2027 charge-off view of 60-75 basis points gives investors a path back toward normal credit costs. FEMA disbursements running about 40% above last year's pace are a further tailwind. New CEO Jorge García inherits that setup on his first call.
Investor expectations had already cooled heading into the report. Earnings Whispers sentiment remained positive but weakened noticeably, falling from 0.47 to 0.31. Shares traded at $162.25 before the release, down 7.3% since the opening after the July report. The stock peaked at a 52-week high of $179.24 in mid-August, then slid to $152.43 on October 1, essentially at its 200-day moving average. It has since recovered to about 6.6% above that average. The trend readings are mixed: momentum is positive, while AVWAP remains negative, consistent with a stock that has given back much of its summer gain without breaking down.
The bottom line is that Popular delivered a clean beat on a still-expanding net interest income base, with disciplined expenses and aggressive capital return. The quarter also confirmed that commercial credit and loan growth are the weak links. Until fourth-quarter charge-offs land near the implied 100 basis points and 2027's lower range looks achievable, the market is likely to weigh the guidance revisions as heavily as the earnings surprise.
Read our earnings preview for Popular, Inc.: https://www.earningswhispers.com/article/BPOP/20506
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| 16 hours | |
| 16 hours | |
| Oct-05 | |
| Oct-01 | |
| Sep-10 | |
| Sep-04 | |
| Sep-01 | |
| Aug-20 | |
| Aug-05 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 |
