S&T Bancorp Posts Record EPS On Rate-Driven Margin Gains, But Stalled Loan Growth And A Guidance Cut Cloud The Outlook
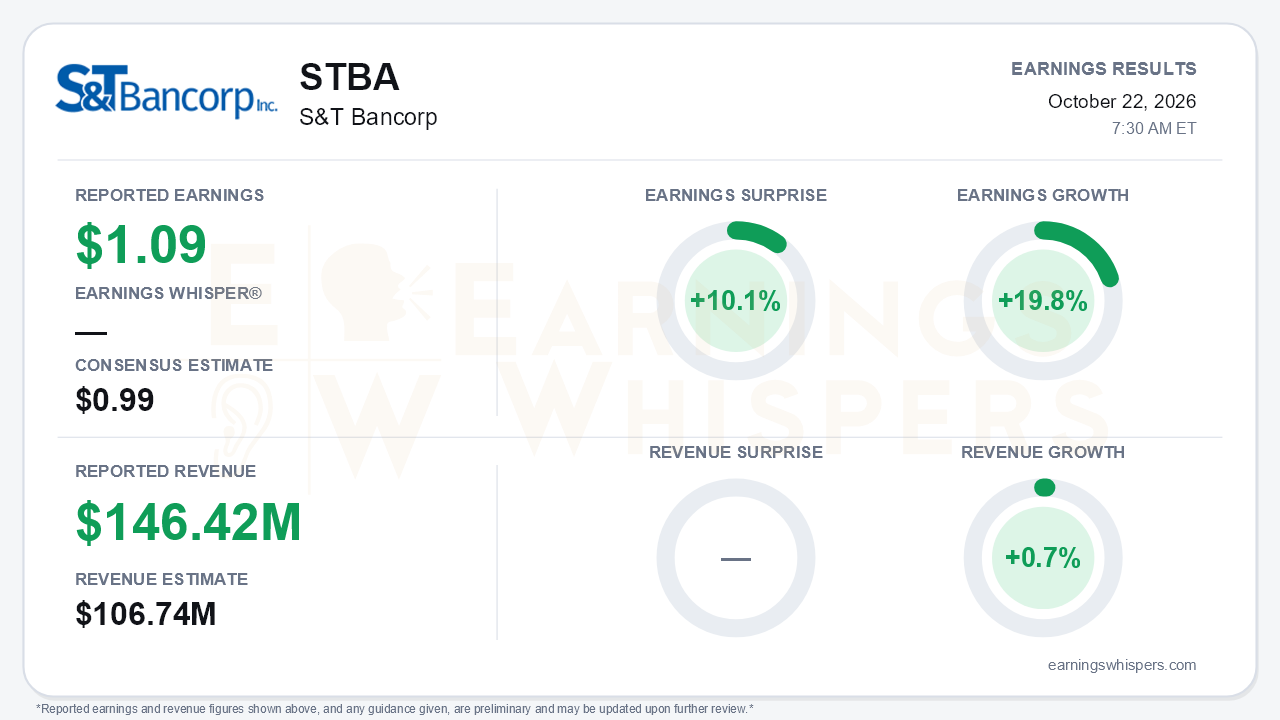
S&T Bancorp delivered its fourth consecutive quarter of rising earnings per share. Diluted EPS reached a record $1.09, beating the $0.99 consensus by 10.1% and growing 19.8% from a year ago. The sequence of $0.89, $0.94, $1.02 and now $1.09 shows earnings that are still accelerating. The engine, though, has narrowed. This quarter's strength came almost entirely from margin expansion and a smaller share count, while the balance sheet stopped growing and management cut its loan outlook. That is the central tension: profitability is improving while the growth story is getting thinner.
The quality of the beat deserves scrutiny on two fronts. First, net income rose to $38.6 million from $35.0 million a year ago, a solid but notably smaller gain than EPS growth. The difference reflects repurchases of 8.3% of outstanding shares since late 2025, totaling $133.4 million. Second, the headline revenue comparison needs context. Reported revenue of $146.42 million topped the $106.74 million consensus by 37.2%, but the reported figure appears to include gross interest income. Management's own record-revenue figure on a net basis was roughly $108 million. The revenue surprise therefore looks largely definitional rather than a sign of operating outperformance. Revenue growth of 0.7% year over year is the more honest reading of a top line that is barely moving.
What did move was the margin. Net interest margin (FTE, non-GAAP) expanded 7 basis points to 4.06%, up from 3.99% in the second quarter and 3.93% a year ago. Asset yields rose 9 basis points while funding costs rose only 3. Management tied this to the September Fed rate hike: 36% of loans reprice within a month, against a deposit beta of only 30-40%. On that basis, management raised its margin outlook from 'high-390s stability' to 'north of 4% into 2027,' assuming two to three more hikes. Other metrics also improved:
- Fee income guidance edged up to $14-15 million per quarter.
- The efficiency ratio improved to 53.23%, aided by a $1.1 million expense decline that the release partly attributed to timing items.
- Return on assets rose to 1.55%.
- Pre-provision net revenue (non-GAAP) climbed to 2.01% of average assets.
The weaker side of the ledger is where the outlook changed. Period-end loans were essentially flat, compared with roughly $99 million of growth in the second quarter. Commercial and industrial balances fell about $50 million on lower line utilization, deliberate exits from deteriorating credits and weak originations. Management cut loan-growth guidance from mid-single digits for the second half to flat-to-low-single digits for the fourth quarter. It also acknowledged that the C&I pipeline is not building and that new bankers are slowed by non-solicit agreements. Rising rates are pushing up cap rates, which is pressuring commercial real estate appraisals and prompting tighter underwriting. Deposit competition is also intensifying, with incremental funding costs in the low 4% range and leaking higher. Management described spread pressure building on both sides of the balance sheet. That raises the question of how long the favorable beta math can persist.
Credit is a mixed picture rather than a problem. On the positive side, nonperforming assets fell to 0.45% of loans plus OREO from 0.50%, and reserve coverage of nonaccrual loans improved to 256%. On the negative side:
- Net charge-offs doubled sequentially to 0.10% of average loans.
- Criticized and classified assets rose about 7%.
- Higher rates cost tangible book value an estimated $0.66 per share through accumulated other comprehensive income, according to management.
- Expenses are guided to rise to $59-60 million per quarter in 2027, from about $58 million this year.
There are offsetting catalysts. Buybacks could resume in the fourth quarter under a $100 million authorization. Slower growth also delays the crossing of the $10 billion asset threshold, which pushes the roughly $6-7 million annualized Durbin hit to mid-2028 at the earliest. Online and mobile platform upgrades round out the operational agenda.
The market setup is more complicated than the surprise implies. Investor sentiment slipped from marginally positive to marginally negative. The shift is small, but it points to softer enthusiasm heading into the print. Shares set a 52-week high of $53.50 shortly after the July report, then faded to an inter-earnings low of $47.07 in mid-October. Entering the report at $48.86, the stock was down 4.2% from the post-July open and sat in the lower part of its quarterly range. It still held about 6.2% above its 200-day moving average. Earnings Whispers trend readings are mixed, with momentum positive but AVWAP negative. Investors appear to have been discounting the growth slowdown even as earnings kept climbing.
The bottom line is that S&T is extracting more profit from a balance sheet that has stopped expanding. The rate-driven margin outlook and possible renewed buybacks give the earnings story credible near-term support. However, flat loans, a reduced growth guide, rising criticized assets and intensifying deposit competition give bears legitimate ammunition. The next leg depends less on margin and more on whether loan growth can restart before funding pressure catches up with asset yields.
Read our earnings preview for S&T Bancorp: https://www.earningswhispers.com/article/STBA/20544
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-13 | |
| Oct-01 | |
| Sep-24 | |
| Aug-05 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-01 | |
| Jun-18 | |
| Jun-17 |
