Third Coast Bancshares Matches The Whisper, But A Broken Margin Guide Overshadows Strong Balance-Sheet Momentum And The Great Plains Deal
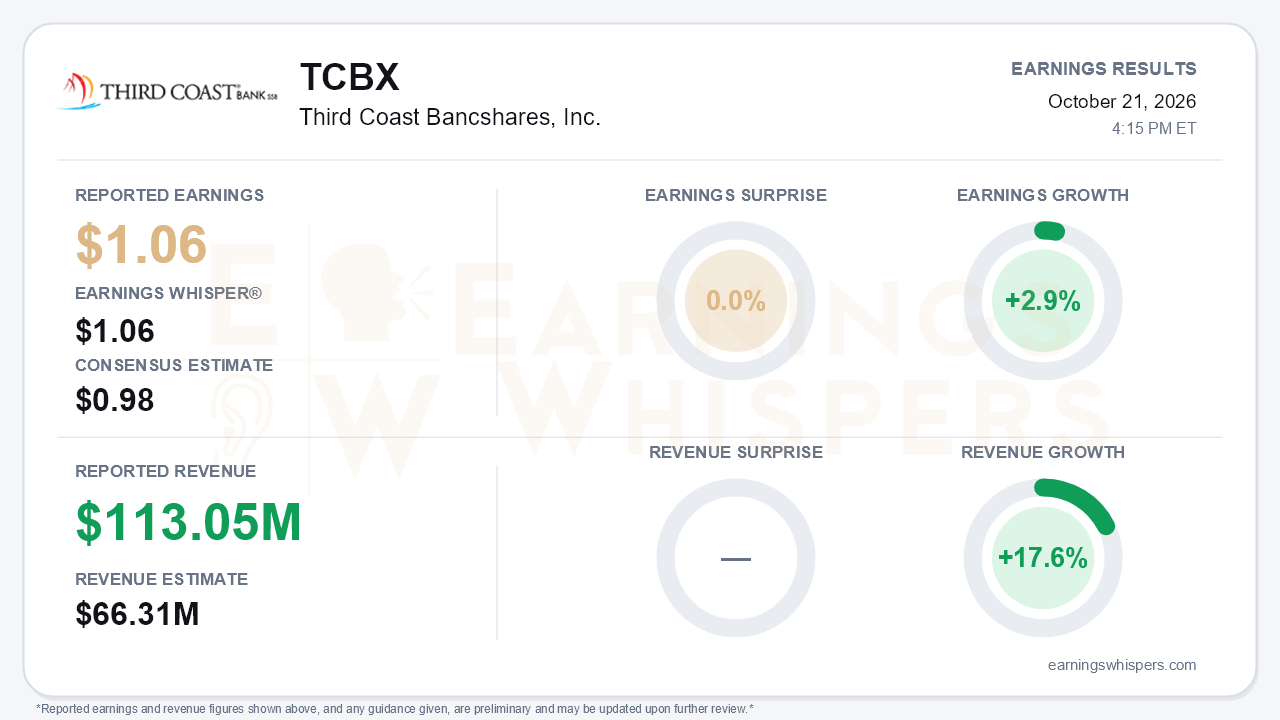
Third Coast Bancshares delivered adjusted earnings of $1.06 per share for the third quarter. That was $0.08 above the $0.98 consensus but exactly in line with the $1.06 Earnings Whisper number, so the result was in line with what the more demanding investors expected. Adjusted earnings grew just 2.9% year over year even though revenue rose 17.6%. That gap is the core of the quarter. Third Coast is growing its balance sheet rapidly, but margin compression and acquisition costs are absorbing most of the benefit. The quarter also included a margin decline that contradicted management's own guidance.
The quality of the quarter deserves scrutiny on several fronts. GAAP diluted EPS fell to $0.93 from a record $1.08 in the second quarter. The decline came from two sources:
- $3.2 million of merger-related expenses in the third quarter;
- the absence of the $3.5 million factoring gain that lifted the second quarter.
On an adjusted basis, earnings improved from $0.98 to $1.06. Stripping out the factoring gain, however, the underlying run rate was roughly flat. The reported revenue beat also needs context. The $113.05 million figure combines gross interest income with fee income. Net interest income actually slipped to $59.5 million from $60.3 million, and net interest margin fell to 3.70% from 3.83%. Margin was 4.10% a year ago. On the expense side, the efficiency ratio rose to 63.1%, or 58.6% on an adjusted basis, compared with 56.5% in the second quarter.
The margin miss is the central tension. In the second quarter, management guided net interest margin flat-to-up and pointed to securitizations as a tailwind. Instead, margin dropped 13 basis points. Management cited three causes:
- about $800,000 of premium amortization tied to the Keystone acquisition;
- minimal fee contribution from the third-quarter securitization, which was slightly net negative to results;
- lower-yielding retained securities.
Cost of interest-bearing deposits rose to 3.49% from 3.41%, and management acknowledged deposit betas near 100% on some accounts. Management now guides fourth-quarter margin to about 3.80% with upside, noting September ran near 3.85%. That is plausible, but it comes one quarter after a missed guide, and investors will want to see it delivered.
Beneath the margin problem, the franchise-building metrics were genuinely strong. Reported loan growth was only $57 million, but excluding the $87.5 million commercial real estate securitization, underlying growth exceeded $144 million. That was above the $75–125 million quarterly range management had set, and October added roughly $80 million more. Funding also improved:
- noninterest-bearing deposits rose $78 million to $721 million;
- that brought them to 12.2% of total deposits, up from 11.0%;
- the new core system has already enabled 25 deposit accounts above $1 million.
Management raised its quarterly fee income guide to about $5 million from $4–4.5 million. The fourth-quarter securitization, the first from the commercial portfolio, is expected to carry more fee income than the third-quarter deal. Tangible book value reached a record $33.31. Still, management held loan guidance rather than raising it, citing possible dampening from higher rates and a need to focus on integration.
The Great Plains merger reshapes the setup. The all-stock deal is valued at about $239.6 million and would create a roughly $9 billion bank with entry into Oklahoma and a larger Dallas/North Texas presence. It is expected to close between February and April 2027. The deal arrives immediately after the Keystone conversion, so back-to-back integration execution, share dilution, and continued merger expenses are legitimate risks. Credit is stable but not spotless:
- nonperforming loans edged up to 0.53% on about $2.3 million of SBA loans moved to nonaccrual, and SBA softness continues;
- other real estate owned has climbed to $27 million from $8.4 million earlier in the year, lifting nonperforming assets to 0.82% of assets;
- offsetting that, Third Coast recorded a third straight quarter of net recoveries.
Investor sentiment remains negative but improved meaningfully, rising to -0.485 from -0.63 at the prior report. That suggests skepticism is easing rather than reversing. The stock has not rewarded the balance-sheet progress. Shares are down 5.2% since the open following the July report, at $40.76, and sit essentially on the 200-day moving average of $40.79. The Earnings Whispers trend signals lean negative, with the AVWAP reading negative and price trend only neutral.
The bottom line is that Third Coast is executing well on loans, deposits, fees, and tangible book value, but the margin miss and acquisition noise are keeping earnings growth in the low single digits. With the stock parked at its 200-day average and sentiment still negative, delivering roughly 3.80% margin in the fourth quarter is the clearest near-term test of whether that growth can finally reach the bottom line.
Read our earnings preview for Third Coast Bancshares, Inc.: https://www.earningswhispers.com/article/TCBX/20488
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-07 | |
| Oct-07 | |
| Sep-30 | |
| Sep-17 | |
| Sep-14 | |
| Aug-24 | |
| Jul-28 | |
| Jul-28 | |
| Jul-22 | |
| Jul-13 | |
| Jul-02 | |
| Jul-01 | |
| Jun-18 |
