Pool Corp. Squeaks Past Estimates As Sales Reaccelerate, But Freight-Driven Margin Erosion Leaves Buybacks Carrying EPS
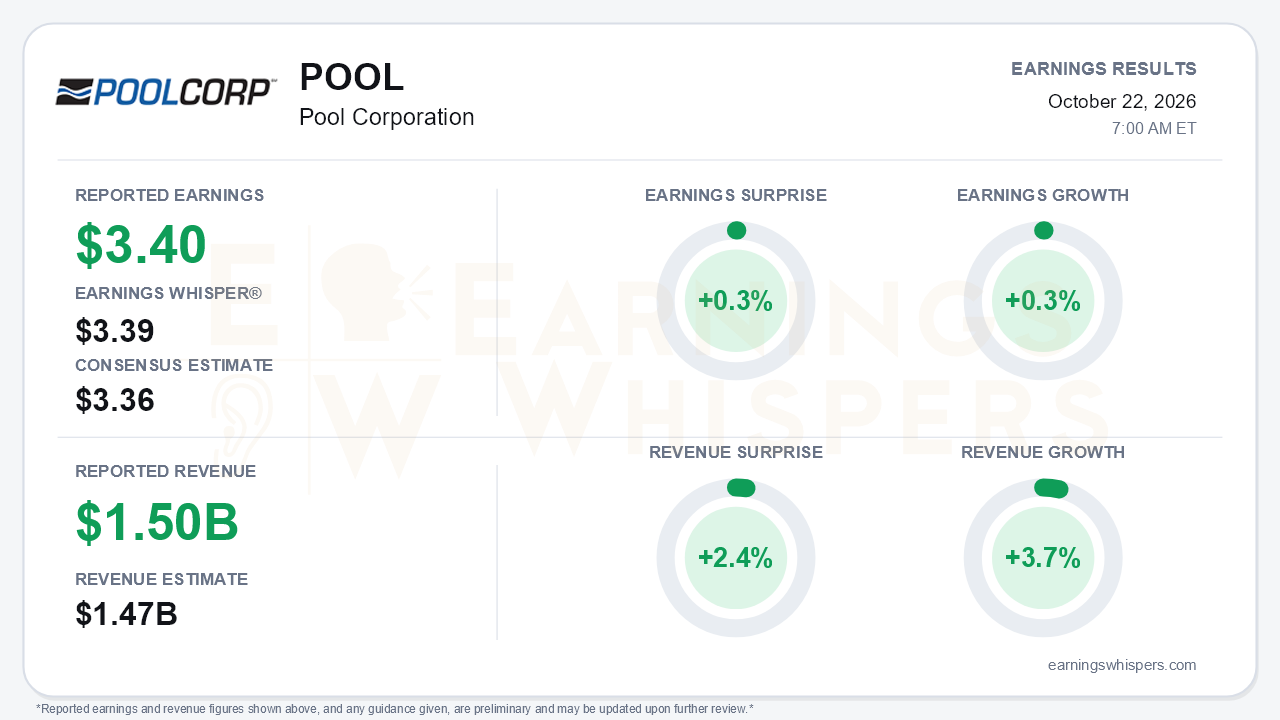
Pool Corporation's third-quarter beat was narrow, and its sources deserve attention. The distributor earned $3.40 per share, ahead of the $3.36 consensus and a penny above the $3.39 Earnings Whisper number, a 0.3% surprise. Earnings grew just 0.3% from a year ago. Revenue was stronger, rising 3.7% to $1.505 billion and topping the $1.47 billion consensus by 2.4%. Sales growth, which the company rounds to 4%, picked up from 2% in the second quarter. That is the central tension. Demand improved, but the higher sales did not reach the bottom line. Profitability weakened at nearly every level beneath revenue.
The income statement shows the problem. Gross margin fell 60 basis points to 29.0%. Management blamed higher inbound freight, customer mix, and a tough comparison against last year's mid-season price increases. The erosion is getting worse: gross margin was down 20 basis points year over year in the first quarter and 30 basis points in the second. Selling and administrative expenses rose 5%, faster than sales, because of performance-based pay, insurance, and outside fees for strategic initiatives. As a result, operating income fell 3% to $172.2 million, and operating margin narrowed to 11.4% from 12.3%. Net income also dropped 3%, to $123.0 million. GAAP EPS held flat at $3.40, and adjusted EPS rose a penny, only because the diluted share count fell about 3.5% to 35.9 million. Without the buyback, this would have been an earnings decline.
The operating detail from the call was better than the margin line suggests. Pricing contributed about 3 points of growth and volume roughly 1 point. Chemicals swung to 4% volume-driven growth from a 2% decline, and equipment improved to 5% from 3%. Building materials grew for a fifth straight quarter. Sun Belt markets recovered to low-to-mid single-digit growth after falling mid-single digits in the second quarter. Retail customer sales turned positive at 3%, Pinch-a-Penny rose 3%, commercial grew 7%, and Europe gained 8% in local currency. Management raised its full-year sales growth outlook to 3-4% from "low single digits" and lifted its pricing contribution estimate to about 3%. Cash generation was the clearest strength. Operating cash flow reached $419.8 million year to date, up 47%, while inventory fell 3% even as sales grew. Management now expects full-year operating cash flow to exceed net income.
The forward picture is less encouraging. Management confirmed adjusted EPS guidance of $10.87 to $11.17 but did not raise it, despite the higher sales outlook. Against $10.21 earned through nine months, the range implies only $0.66 to $0.96 in the fourth quarter. Freight inflation, which management called the steepest since COVID, is expected to persist at third-quarter levels. The August building-materials price increase covers only part of that cost, and most repricing is pushed into early 2027. Fourth-quarter gross margin is expected to come in below last year. October sales are running only about 2% higher as the pricing benefit fades. The 2027 headwinds are already visible:
- Interest-rate swaps expire in February, lifting the borrowing rate to roughly 5.2% from 4.2%.
- The year has one fewer selling day.
- Management has flagged further investment spending.
- New pool construction and the housing-tied Horizon irrigation business remain weak.
- Management expects the 2027 macro environment to be no better than 2026, and the 6-9% long-term growth algorithm stays off the table without a market recovery.
The offsets are mostly promises for now. New CEO John Watwood sounded more energized, citing "green shoots" and an M&A pipeline described as much healthier than a few months ago. Management also promised a quantified strategic framework with the February 18 report and an updated long-term algorithm at an Investor Day in the first half of 2027.
The market had already priced in a lot of skepticism. Shares closed at $172.44 before the report, down 15.4% from the open after the July release and 15.6% below the 200-day moving average of $204.33. The stock fell from an inter-earnings high of $209.78 in early August to a 52-week low of $152.70 on October 8, then rebounded nearly 13% heading into the print. Investor sentiment improved meaningfully, from -0.15 to +0.05, though that is closer to neutral than enthusiastic. Price and AVWAP trend readings remain negative, while sequential growth and momentum are neutral. That mix fits a stock trying to stabilize rather than one with a clear recovery underway.
The bottom line is that Pool delivered a better top line and excellent cash flow, but the quality of the earnings beat is thin. Gross margin is eroding faster each quarter, costs are outgrowing sales, and the share buyback is doing the work that operations used to do. The reaffirmed guidance and a softer October suggest margin relief is unlikely before 2027 pricing takes effect. Interest costs and investment spending will also weigh on that year. Bulls have a credible demand recovery and a strategic reset to point to, while bears have legitimate ammunition in the profitability trend. The next real test is whether February's framework can show a path back to margin expansion.
Read our earnings preview for Pool Corporation: https://www.earningswhispers.com/article/POOL/20537
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-08 | |
| Sep-25 | |
| Aug-13 | |
| Aug-04 | |
| Jul-29 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-15 | |
| Jul-09 | |
| Jun-16 | |
| Jun-09 |
