Oceaneering Misses EPS Consensus As Refinancing Charge And Soft Q4 Guide Overshadow Record Subsea Margins And A Constructive 2027 Outlook
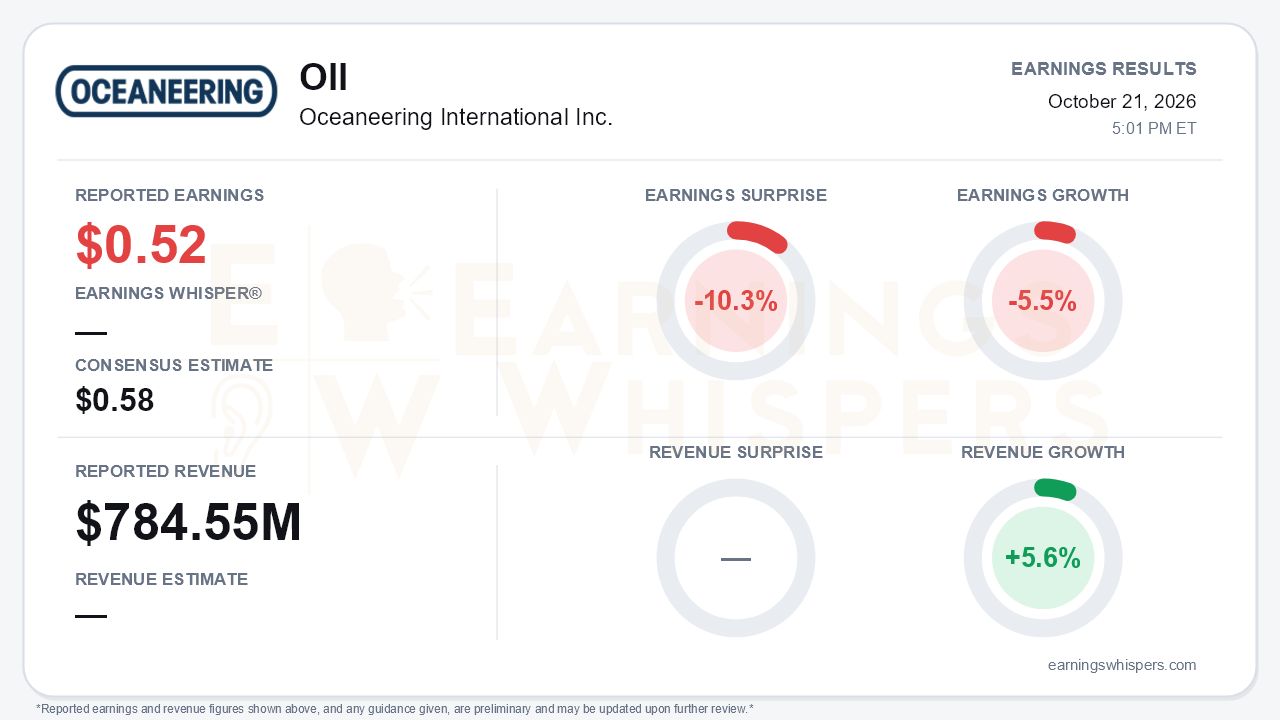
Oceaneering International (NYSE: OII) reported third-quarter earnings of $0.52 per share, missing the $0.58 consensus by 10.3%. Earnings fell 5.5% year over year even as revenue grew 5.6% to $784.55 million. The headline miss and the operating story point in different directions. Management described results as in line with its guidance and consensus, a claim that fits the $119 million adjusted EBITDA print, which sat inside the $115-125 million range given on the second-quarter call. It does not fit the per-share comparison. That gap between the operating results and the bottom line is the first thing investors need to untangle.
The EPS shortfall traces mostly to items below the operating line. Operating income rose 7% to $92.2 million and gross margin improved, but a $19.0 million loss on debt extinguishment tied to the third-quarter refinancing pulled pretax income down to $69.1 million from $79.9 million. The tax provision also nearly doubled to $16.5 million. GAAP net income attributable to Oceaneering fell 26% to $52.6 million. The non-GAAP adjusted figure, which strips out foreign-currency effects and discrete tax items but does not add back the debt charge, was $0.50 per share, versus $0.55 a year ago and $0.63 in the second quarter. The quality of the miss is therefore better than the number suggests. Underneath, though, earnings power was not expanding as fast as the record EBITDA headline implies. Adjusted EBITDA was the highest since late 2015, yet consolidated adjusted EBITDA margin held flat at 15%.
Subsea Robotics was the clear standout. Segment operating income rose 16% to $75.4 million, and EBITDA margin reached 39%, up from 35% in the second quarter and 32% in the first and the highest since the 2020 resegmentation. Revenue per ROV day climbed to $11,781 on pricing strength in Europe, West Africa and Norway. Two caveats matter here. The call attributed part of the margin to a one-time U.S. Gulf cost recovery, and utilization was stuck at 65%. Weakness elsewhere offset some of that strength. Manufactured Products grew revenue partly on the resolution of a legacy mobility contract, while Grayloc weakened. ADTech margin slipped to 11% on pass-through work and program costs, and IMDS earned just $2.8 million on $75.8 million of revenue. Cash generation was the quarter's other bright spot. Free cash flow of $142 million compared with $32 million in the second quarter and an outflow in the first, lifting cash to $735 million and liquidity above $1 billion.
The forward picture is the central tension. Fourth-quarter EBITDA guidance of $85-95 million implies full-year 2026 of roughly $403-413 million, the lower half of the $400-440 million range, and management did not explicitly reaffirm that range. Subsea operating income is guided down as rigs relocate out of the U.S. Gulf, and OPG is guided lower on mix. Leading indicators are also softening:
- Manufactured Products' trailing book-to-bill fell to 0.77 from 0.88.
- Backlog slid to $435 million from $568 million a year earlier.
- Floating rigs under contract dropped to 136 from 139.
Against that, initial 2027 EBITDA guidance of $430-480 million is about 11% above implied 2026 at the midpoint, with free cash flow expected to rise. Supporting catalysts include roughly $180 million of ROV and survey awards running into 2031, about $160 million of Manufactured Products orders, and Navy follow-ons worth up to $154 million and $67 million. Management hedged the timing, however. It cited rig moves, continuing-resolution risk to defense program starts, and OPG scheduling, and the low end of the range implies a roughly flat energy business.
Investor sentiment remained negative but improved modestly, moving from -0.108 to -0.073 ahead of the report. Shares closed at $44.09, down 6.6% since the open following the July report, though still about 10.8% above the 200-day moving average of $39.78. The stock has given back ground over the quarter without breaking its longer-term uptrend. Supporting trend readings are mixed to soft, with price trend neutral and AVWAP negative, consistent with a market that has grown less willing to pay up ahead of a seasonally weaker fourth quarter.
The bottom line is that Oceaneering's EPS miss owes more to a refinancing charge and taxes than to operations. Still, the quarter was not as clean as record Subsea margins and surging free cash flow make it look. A soft fourth-quarter guide, eroding Manufactured Products backlog and a slipping rig count give bears legitimate ammunition. A credible 2027 EBITDA growth outlook and a fortified balance sheet give bulls a reason to look through the near-term trough, as long as the timing risks management flagged do not push that recovery further out.
Read our earnings preview for Oceaneering International Inc.: https://www.earningswhispers.com/article/OII/20475
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-01 | |
| Sep-23 | |
| Aug-11 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-14 | |
| Jul-06 | |
| Jul-01 | |
| Jun-30 | |
| Jun-25 | |
| Jun-24 |
