Old Republic Misses On Operating EPS As Specialty Margins Erode Beneath Faster, Partly Acquired Premium Growth
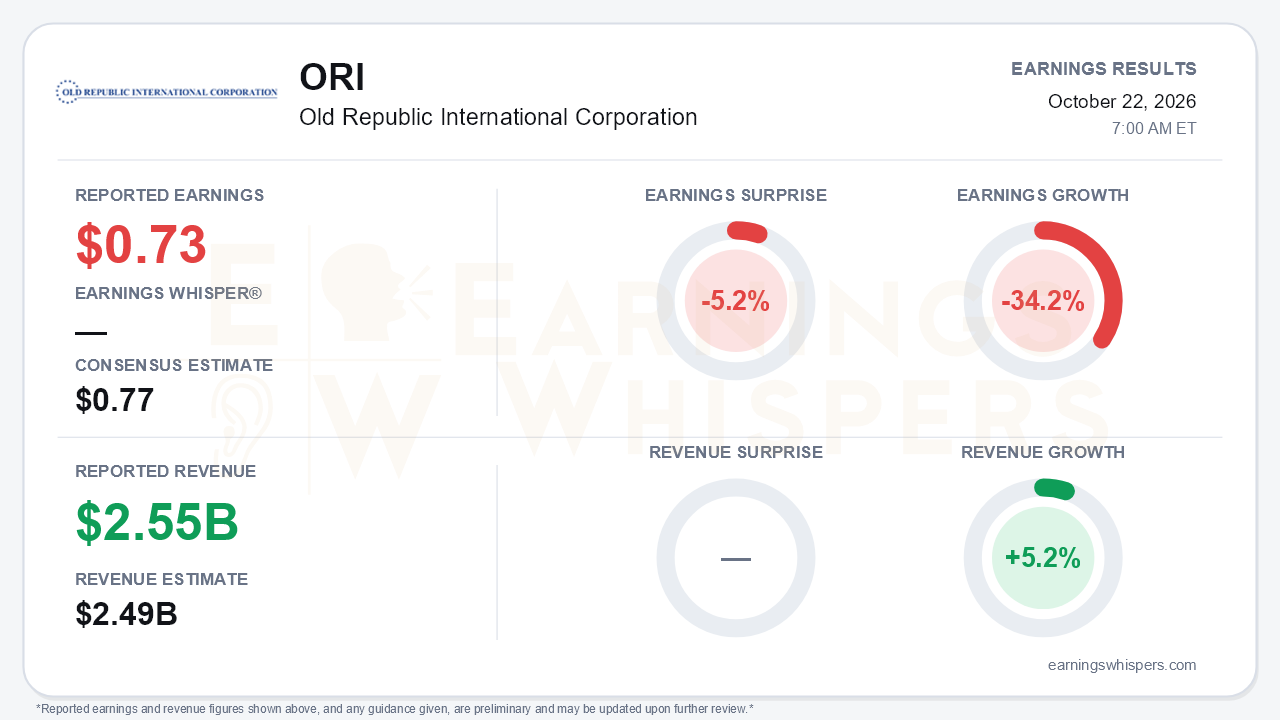
Old Republic International reported third-quarter net operating income of $0.73 per diluted share, missing the $0.77 consensus by 5.2%. Revenue of $2.551 billion beat the $2.49 billion estimate by 2.4% and grew 5.2% year over year. On the normalized basis, earnings fell 34.2% year over year. The company's own like-for-like comparison is gentler: operating EPS fell 6.0% from $0.78. The gap exists because the prior-year GAAP figure of $1.11 included $0.33 of realized investment gains. Either way, the central tension is clear. Old Republic is growing faster, helped by an acquisition and auto warranty volume, while its core specialty underwriting margin keeps slipping toward the edge of management's target range.
The quality of the quarter deserves scrutiny because the GAAP line flatters it. Net income of $243.2 million ($0.99 per share) included a $124.9 million bargain purchase gain from the July 1 closing of ECM Insurance Group, which more than offset $63.2 million of after-tax realized investment losses. Strip those out and net operating income fell 7.8% to $181.4 million. Consolidated pretax operating income was $227 million, down from $238 million in the second quarter and $248 million a year ago. Net premiums and fees earned rose 8.8% to nearly $2.3 billion, but the consolidated combined ratio worsened to 96.1% from 95.3%. Corporate & Other swung to a $27.0 million pretax loss, reflecting:
- higher interest costs from the May debt issuance;
- ECM transaction costs;
- lower investment income on a shrinking parent-level asset base.
The operating story splits sharply by segment. In Specialty Insurance, net premiums written rose 10.5% as reported, or 4.4% on the underlying basis management uses (excluding ECM and the auto warranty write-up to retail). That compares with 1.6% underlying growth in the second quarter and 3.4% in the first, so the top line genuinely accelerated. Workers' compensation premiums swung to +7% from -8.4%, and commercial auto improved to +5.7%. Margins moved the other way. The specialty combined ratio rose to 96.0%, versus 95.5% last quarter and 94.8% a year ago, for three reasons:
- Favorable reserve development shrank to 0.8 points from 3.4 points, with general liability and financial indemnity again developing unfavorably.
- A $20 million credit loss on a guaranteed asset protection account added 1.4 points to the expense ratio. It follows a $17.5 million credit loss in the fourth quarter of 2025, so bears have legitimate ammunition about underwriting discipline in program business.
- In commercial auto, rate increases eased to the mid-teens from the high teens while the loss ratio rose to 71.0% from 69.4%.
The current-year loss ratio did improve, so the deterioration is concentrated in reserve releases and one-off credit costs rather than accident-year pricing. Even so, the CEO acknowledged that specialty now sits at the top of its 90%-95% target range and that he is planning for several years of soft-market conditions.
Title was steadier but lost some of its earlier optimism. Pretax operating income rose 10.1% to $50.4 million, and the year-to-date combined ratio improved to 96.9%. Agency revenue grew 9%, but directly produced premiums were flat and commercial share slipped to 23.6% of earned premium. Management sounded more cautious as mortgage rates move toward 7%, a notable shift from the brighter title outlook voiced on the second-quarter call. Book value per share also fell to $24.65 from $25.33 in the second quarter, driven by $1.29 per share of unrealized bond losses.
The forward catalysts are real. ECM is accretive and its external quota share has been removed, so Old Republic now retains more of that premium. Auto warranty net written premium reached $545.9 million year to date versus $350 million a year earlier, and management floated $600-$700 million or more annually within a few years. Start-up operating companies are up roughly 40%. New-money bond yields of 5.4% sit well above the roughly 4.9% book yield, although investment income growth slowed to 1.5%. Buybacks also stepped up to $113.8 million in the quarter, plus about $60 million after quarter-end.
Investor sentiment improved modestly ahead of the report, rising from 0.0144 to 0.0874, but it remains close to neutral rather than enthusiastic. The stock has drifted 1.2% lower since the open after the July report and closed at $40.13, just 1.1% below its $40.59 200-day moving average. Shares sit about 10% below the $44.65 high set shortly after the last report and 8.3% above the October 1 low. That pattern shows the market already giving back the post-July optimism. The Earnings Whispers price and AVWAP trend readings remain negative, consistent with that fade.
The bottom line is that Old Republic delivered better top-line momentum than it has all year, but the earnings engine is weakening underneath. Thinner reserve releases, a repeat credit loss, and softening commercial auto pricing pushed specialty to the top of its target range just as management prepares for a prolonged soft market. ECM, warranty growth, higher reinvestment yields, and heavier buybacks give the story credible support, but the miss shows that growth is not yet translating into operating earnings.
Read our earnings preview for Old Republic International Corporation: https://www.earningswhispers.com/article/ORI/20533
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 13 hours | |
| 13 hours | |
| Oct-13 | |
| Oct-08 | |
| Sep-16 | |
| Aug-14 | |
| Aug-06 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-20 | |
| Jul-09 | |
| Jun-30 |
