SL Green Matches FFO Estimates As A One-Time Stake Sale Masks A Rate-Driven Guidance Cut, While Manhattan Leasing Keeps Strengthening
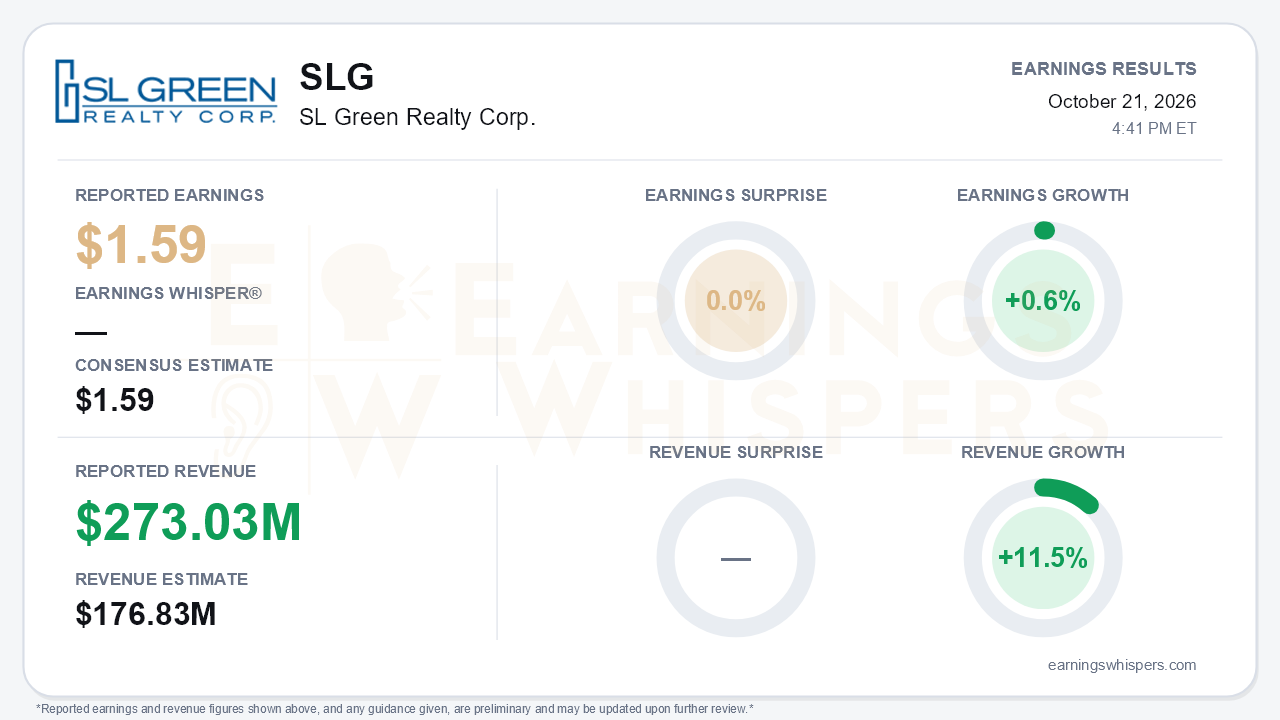
SL Green Realty Corp. (NYSE: SLG) reported third-quarter FFO of $1.59 per share, exactly matching the consensus estimate and up 0.6% from $1.58 a year earlier. Revenue of $273.03 million rose 11.5% year over year and beat the consensus estimate by 54.4%. The headline guidance note says SL Green raised its outlook, but the raise needs a closer look. The full-year 2026 FFO range moved from $5.60-$5.90 to $6.50-$6.70. That increase includes $1.10 per share of income from selling a 20% stake in the company's food and beverage hospitality business. Against that, management deducted $0.25 per share for higher interest rates. Excluding the one-time sale, the operating outlook moved lower. That is the central tension. The office business is getting stronger, while the earnings outlook is being squeezed by financing costs and slower asset sales.
The quality of the quarter's results also deserves scrutiny. GAAP net income jumped to $1.01 per share from $0.34. Most of that came from a $91.4 million gain on real estate sales, which does not reflect recurring earnings power. FFO was essentially flat, so it is the better measure of how the business is running. The revenue mix was healthier. Rental revenue rose to $165.6 million from $149.7 million, and fee income climbed to $30.6 million from $23.3 million. Below that line, the picture was less favorable. Net interest expense increased to $50.0 million from $47.2 million. Borrowings on the revolving credit facility rose to $930 million from $640 million at year-end. SUMMIT Operator expenses of $42.9 million were well above SUMMIT revenue of $34.7 million. For the first nine months, FFO was $3.85 per share versus $4.60. The prior-year figure included a $0.94 per share gain from the repayment of the 522 Fifth Avenue loan, which accounts for much of that decline.
The operating story was clearly the strongest part of the report. SL Green signed 591,108 square feet of Manhattan office leases in the quarter, bringing the year-to-date total to nearly 2 million square feet. On replacement leases, new rents were 13.6% above the previous fully escalated rents in the quarter and 15.7% above them year to date. Same-store office occupancy, including signed leases that have not yet started, reached 95.0%, up from 92.9% at the end of 2025. Same-store cash NOI excluding lease termination income rose 5.0%. That exceeds the 3.5%-4.5% range management set at the start of the year. Tenant concessions are also easing. Free rent averaged 8.2 months in the quarter versus 8.6 months year to date, and tenant improvement allowances were $85.20 per square foot versus $89.88. On the call, management said the leasing pipeline has grown to 1.3 million square feet, up from 900,000 in the first and second quarters. Pricing in that pipeline is running more than 20% above prior rents. Management also reaffirmed its target for cash same-store NOI growth above 10% in 2027.
The balance sheet and transaction activity point the other way. Management said rates are roughly 100-150 basis points higher than its plan assumed. About $0.20 of the $0.25 reduction comes from interest expense, and about $0.05 from lower fee income. Asset sales are also taking longer. Six of 11 planned deals are complete, covering roughly $1 billion of a $2.5 billion program. Some of the remainder may slip into the first half of 2027, which would also delay the related joint venture fees. SUMMIT was a disappointment. The World Cup, which management described in the first quarter as a likely boost, ended up keeping tourists away, and Paris pre-opening costs added pressure. Management's tone was notably defensive when analysts described the asset sales as delayed. Looking further ahead, capitalized interest will decline as development projects lease up, which will push 2027 interest expense higher.
There were also real offsets. The $2.0 billion refinancing of 245 Park Avenue closed at an effective rate of 6.37% on SL Green's share. With that deal, more than $7 billion of the 2026 financing plan is complete, and little refinancing is needed in 2027. The pending sale of 110 Greene Street should bring in about $216 million, which is earmarked for paying down corporate debt. Management also expects to close a roughly $500 million construction loan for 750 Third Avenue in December. Other potential sources of upside include the debt fund, which has now deployed $643 million, and new special-servicing and asset-management mandates.
Investor sentiment remained positive but weakened, falling to 0.1545 from 0.2450 at the July report. Shares were at $46.68 on the report date, down 9.0% from the $51.30 open after the prior release. That leaves the stock almost exactly at its 200-day moving average of $46.74. Since the last report, the stock has given back gains even as leasing improved, and the AVWAP trend reading remains negative. Investors appear to have been pricing in the rate pressure before management formally reduced the outlook.
The bottom line is that SL Green's office business is performing as well as it has in years. Occupancy, rent increases on new leases, concessions and the leasing pipeline are all moving in the right direction. However, the guidance raise depends on a one-time sale, and the underlying earnings outlook was cut for higher rates and slower asset sales. Bears have legitimate ammunition on leverage and execution timing. Bulls can point to a leasing recovery that supports the 2027 NOI target. Execution on the remaining asset sales and interest costs will likely shape how much of that operating strength shows up in earnings.
Read our earnings preview for SL Green Realty Corp.: https://www.earningswhispers.com/article/SLG/20483
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-05 | |
| Sep-18 | |
| Sep-16 | |
| Sep-15 | |
| Sep-14 | |
| Sep-11 | |
| Sep-09 | |
| Aug-31 | |
| Aug-25 |
