VeriSign Misses By A Penny But Raises Its Outlook For A Third Straight Call As Record Registrations Mask Renewal Slippage
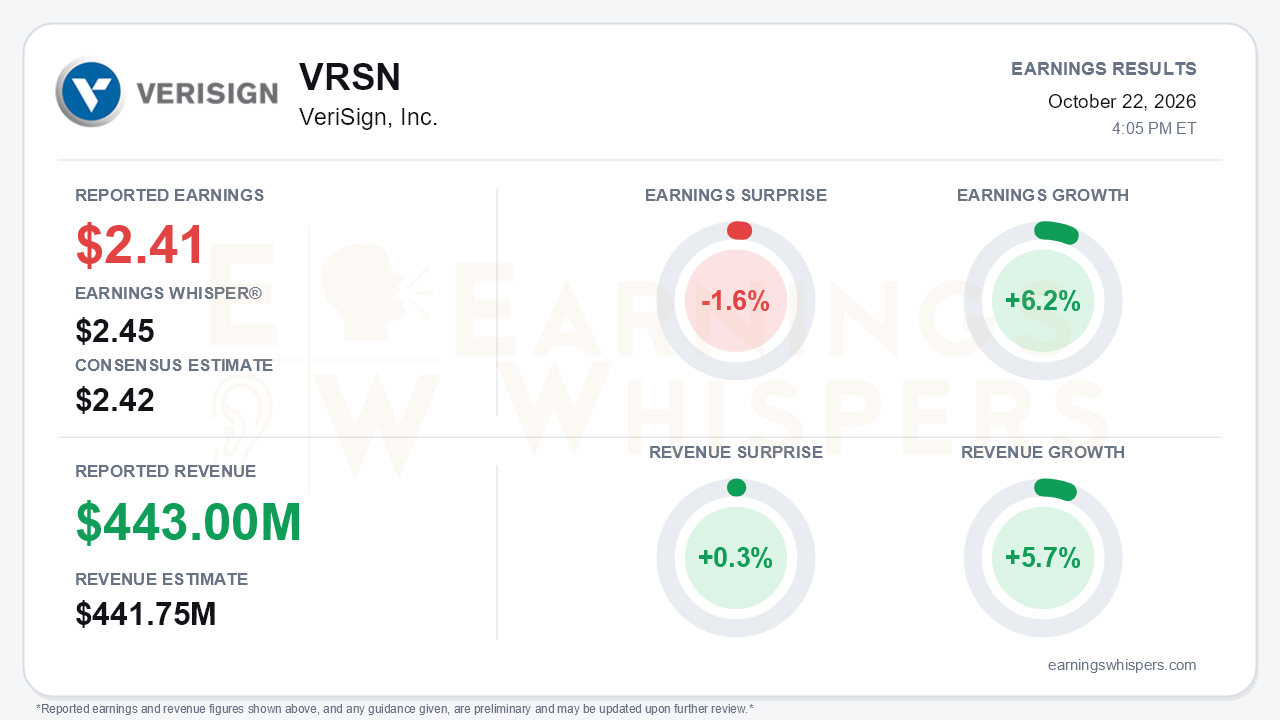
VeriSign's third quarter delivered a small earnings miss inside a fundamentally stronger outlook. The registry operator reported earnings of $2.41 per share, short of the $2.42 consensus and the $2.45 Earnings Whisper number, a 1.6% shortfall. Revenue of $443.0 million edged past the $441.75 million estimate by 0.3%. Earnings grew 6.2% year over year and revenue rose 5.7%. The $2.41 figure excludes a $7.5 million pre-tax loss on assets held for sale. On a GAAP basis, diluted EPS was $2.35, versus $2.27 a year ago and $2.38 in the second quarter. The headline is a modest miss, but the real story is that management again raised its full-year outlook on the back of the strongest domain-name demand in years.
The quality of the earnings line deserves scrutiny. GAAP net income was essentially flat at $212.6 million versus $212.8 million a year earlier, so per-share growth came almost entirely from the shrinking share count. Diluted shares fell to 90.4 million from 93.6 million, helped by another $189 million of buybacks in the quarter. Several costs moved against the company:
- Operating income rose to $296.5 million from $284.3 million, but SG&A jumped to $70.2 million from $60.6 million.
- Total operating expenses climbed to $147 million from $138 million in Q2, including the held-for-sale charge.
- Tax expense rose to $67.0 million from $58.9 million.
- Free cash flow fell to $261 million from $303 million a year ago, which management attributed to higher cash taxes and employee and vendor payments.
Cash and marketable securities dropped to $476 million after VeriSign redeemed $550 million of 2027 notes. Senior debt was roughly unchanged from year-end because the company issued new notes earlier in the year.
Beneath that, the operating trend clearly accelerated:
- New .com and .net registrations reached a record 13.1 million, up from 12.7 million in Q2, 11.5 million in Q1, and 10.6 million a year ago. Management cited AI and agentic AI as accelerating tailwinds.
- Net additions rose to 3.4 million from 3.05 million in Q2 and 2.54 million in Q1.
- The domain base reached 182.5 million, up 6.1% from a year earlier.
That demand drove the third straight increase in full-year domain base growth guidance, now 6.5% to 7.0%. The initial guidance was 1.5% to 3.5%. Full-year revenue guidance rose to $1.755 billion to $1.760 billion from an initial $1.715 billion to $1.735 billion. Operating income guidance moved up to $1.188 billion to $1.192 billion, even after absorbing the $7.5 million loss. Management's tone shifted from teasing new services to discussing launched products. The call preserved, and arguably strengthened, a credible growth story for a business long viewed as a slow-growth toll road.
The central tension is renewal quality. The preliminary Q3 renewal rate slid to 74.3%, down from 75.2% in Q2, 76.3% in Q1, and 75.4% a year ago. The final Q2 rate of 75.2% in the press release was also slightly below the prior year's 75.5%. Management attributed the decline to mix: a heavier share of first-time renewals, which typically renew at only a mid-40% rate. That explanation is reasonable, but it also defines the 2027 risk. The record 2026 cohort will face its first renewal test next year, and management acknowledged it will watch that cohort closely. Bears have legitimate ammunition if AI-driven registrations prove less sticky than legacy demand.
The catalyst calendar is now concrete:
- A $0.71 .com wholesale price increase takes effect November 1. About half of its benefit lands in 2027, and so far registrars have passed little of it through at retail.
- The .web launch begins with a 30-day sunrise in mid-December. A limited registration period for .com holders runs from mid-January to early April 2027, followed by general availability.
- VeriSign Informed, a certificate-revocation security service, is in beta, with pricing due by year-end and production in the first half of 2027. VeriSign also applied for .pki, its only application in ICANN's new gTLD round.
Offsetting risks include monetization uncertainty around .web and VeriSign Informed, an expected seasonal slowdown in Q4 registrations, and AI-driven server and memory inflation pressuring capex.
The market had largely anticipated the improvement. Shares entered the report at $307.25, up 16.5% since the open after the July report and about 14% above the 200-day moving average. That left the stock within 1% of its inter-earnings high of $310, set September 22. The Earnings Whispers trend signals were uniformly positive heading in. Investor sentiment, however, slipped from slightly positive (0.04) to slightly negative (-0.02). That is a modest cooling rather than a reversal, but it suggests expectations had become fuller than the stock's strength alone implied.
The bottom line is that VeriSign's penny-level miss matters less than its third consecutive guidance raise and record registration growth. Still, net income was flat, cash flow softened, and EPS growth leaned on buybacks. With the stock priced near its highs, the debate now shifts to whether the 2026 registration surge renews in 2027 and whether .web, the price increase, and VeriSign Informed can convert momentum into durable earnings growth.
Read our earnings preview for VeriSign, Inc.: https://www.earningswhispers.com/article/VRSN/20591
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-01 | |
| Sep-28 | |
| Jul-24 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 |
