Omnicom Matches The Whisper As Core Organic Growth Accelerates To 7.2%, But Adjusted Earnings Growth Cools
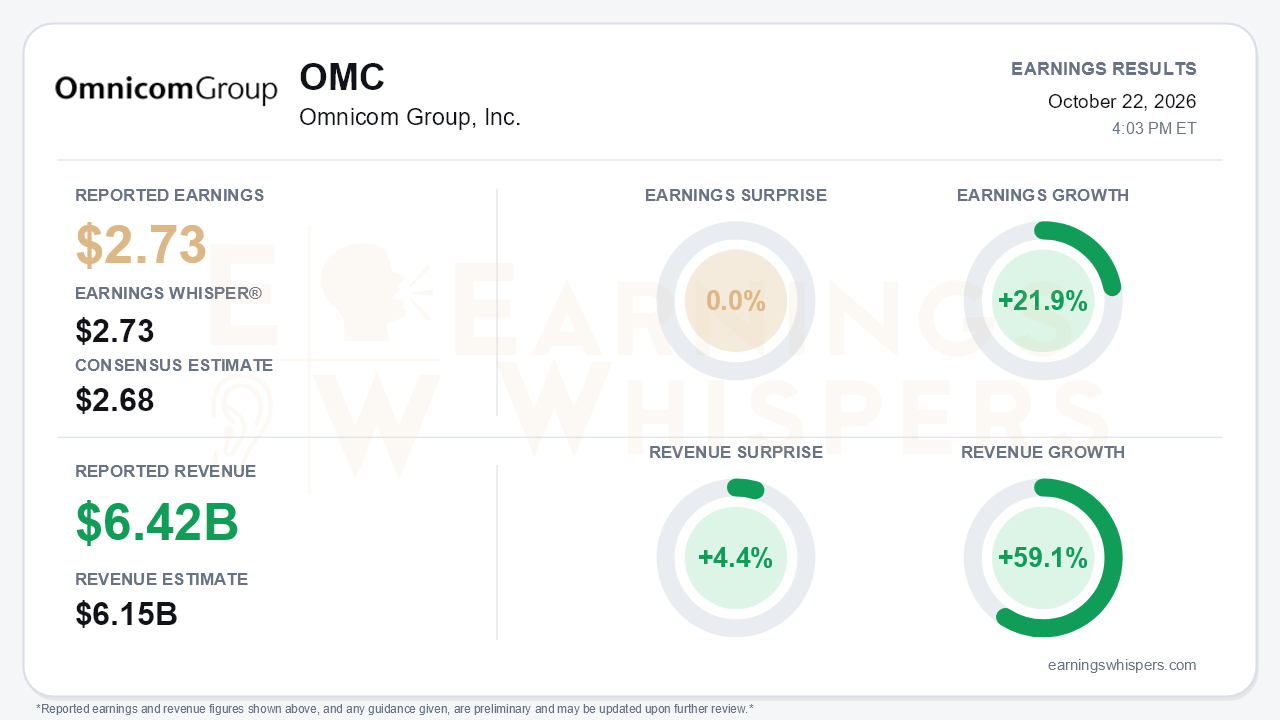
Omnicom's third quarter delivered exactly what the most demanding expectations required. Adjusted earnings of $2.73 per share matched the Earnings Whisper number and topped the $2.68 consensus, making it an in-line result against whisper expectations. Revenue of $6.42 billion beat consensus by 4.4%. The 59.1% revenue growth is mostly the Interpublic acquisition, which closed in November 2025, so the more important number is beneath it. Core organic growth reached 7.2%, up from 6.1% in the second quarter and 3.9% in the first. That acceleration is the main story. The complication is that adjusted EPS growth slowed to 21.9% from 29.3% last quarter, even though sequential EPS still edged up from $2.65.
The quality of the beat holds up better than a typical acquisition-heavy quarter, but it deserves scrutiny. Core adjusted EBITA rose 21.1% to $1.1 billion, and the core margin widened to 18.2% from 16.2%. Management attributed the improvement to cost synergies and organic growth.
The businesses Omnicom is selling ran at just an 8.2% margin on $412 million of revenue. Shedding them flatters the remaining company, and in Omnicom's case that pruning is deliberate rather than cosmetic.
On a GAAP basis, diluted EPS rose to $2.38 from $1.75. That figure was helped by several items:
- A $106.8 million gain on a subsidiary sale, largely offset by $84.7 million of repositioning charges and $40.4 million of integration costs.
- Favorable tax settlements.
The adjusted figure also excludes $0.32 per share of after-tax amortization, up from $0.08 a year ago, so the gap between GAAP and adjusted results is now structurally wider. Interest expense of $132.8 million, up $72.4 million, is the clearest cost of the deal's financing. Consolidated adjusted EBITA margin of 17.6% was essentially flat with the second quarter's 17.8%, which suggests margin expansion may be maturing even as revenue accelerates. The dividend was raised to $0.80 from $0.70.
One caveat matters for interpreting the forward story. The conference-call material available for this review duplicates the July second-quarter call, so it offers no new third-quarter commentary. What it establishes is the framework management set three months ago:
- Full-year core organic growth guidance raised to 4.5%-5% from 4%.
- Adjusted EPS growth guided to the high teens, up from double digits.
- Synergies a little over halfway to the $900 million 2026 target, with $1.5 billion targeted by mid-2028.
- Integrated media growth of just over 10%, with wins at Adidas, IBM and Subway.
The third-quarter release does not restate that organic guidance. It only affirms the synergy target, so investors should not assume guidance was raised again. Still, a 7.2% third quarter on top of a 5% first half sits well above the 4.5%-5% range. Either the guide was conservative, or a meaningful fourth-quarter slowdown is embedded. Investors will want that resolved.
Bears still have legitimate ammunition from the July framework:
- Advertising was falling high single digits.
- Health had slowed to flat.
- Asia Pacific had turned slightly negative.
- Middle East & Africa was down double digits.
- Management described the pitch environment as "as brutal as it's ever been," with peer pricing pressure.
- First-half working capital was a $2.4 billion outflow.
- Experiential's World Cup-driven growth sets up a tough 2027 comparison.
The disposal program, expanded to $3.5-3.6 billion of annualized revenue and concentrated in advertising, is shrinking exactly the weak segments. That helps the reported mix but also reduces scale.
Investor expectations have shifted materially. Earnings Whispers sentiment climbed from -0.30 after the July report to roughly neutral at 0.00, a meaningful improvement. Even so, it is not a level that signals crowded optimism. Price behavior has been volatile rather than directional. Shares hit a 52-week high of $89.57 in late August, fell to $73.63 at the end of September, and entered the report at $80.50. That is 3.7% below the open following the prior report, 9.3% above the quarterly low, and 3% above the $78.15 200-day moving average. The Earnings Whispers trend readings are mostly positive, with sequential growth and momentum improving while the price trend is neutral. The market setup is more complicated than the clean whisper match implies: the stock has already given back its post-July enthusiasm.
The bottom line is that Omnicom's integration is producing what it promised: faster organic growth, wider core margins and double-digit adjusted EPS growth. Matching the whisper rather than clearing it, along with a slowdown in EPS growth from the second quarter's pace, keeps this from being a decisive upside surprise. The next test is whether management updates organic guidance to reflect the 7.2% run rate, and whether shrinking advertising and health remain contained.
Read our earnings preview for Omnicom Group, Inc.: https://www.earningswhispers.com/article/OMC/20622
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Oct-16 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-06 | |
| Oct-04 | |
| Sep-29 | |
| Sep-28 | |
| Sep-21 |
