MaxLinear's AI Optical Ramp Accelerates Again, But Wafer Prepayments Turn Cash Flow Negative
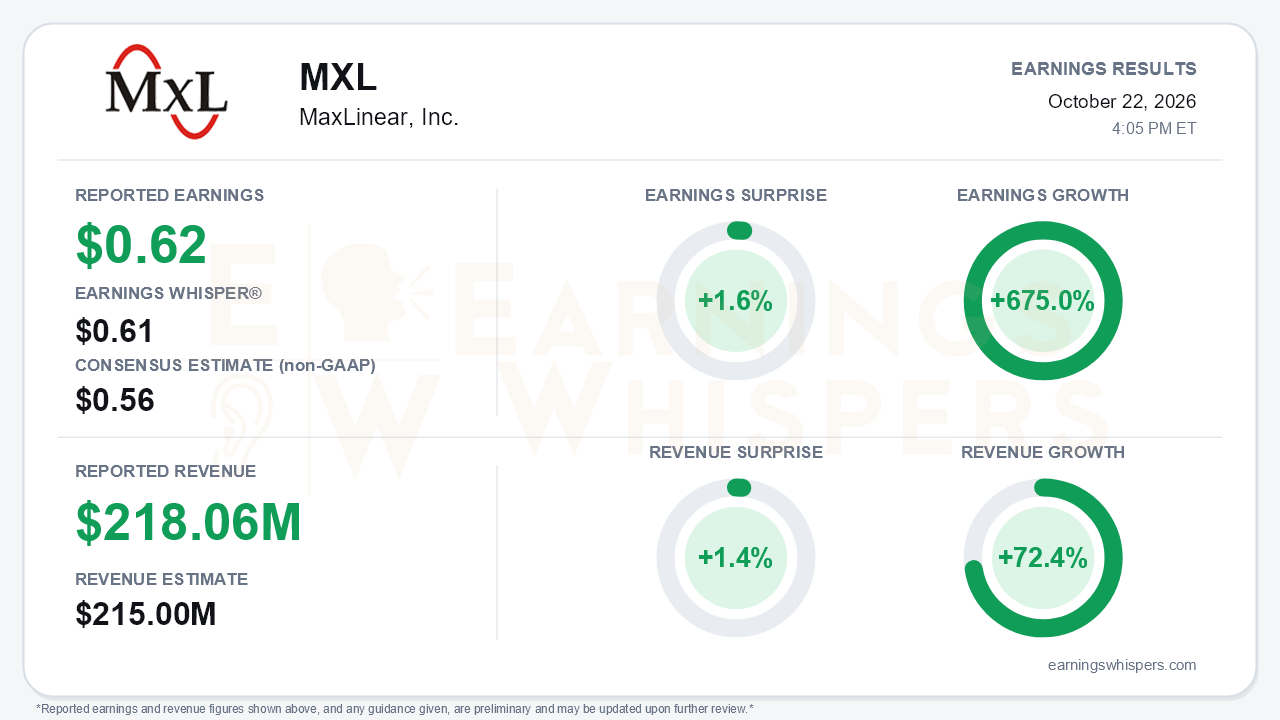
MaxLinear delivered another beat-and-raise quarter built almost entirely on its AI data center optical business. Third-quarter non-GAAP earnings were $0.62 per share, ahead of the $0.56 consensus and the $0.61 Earnings Whisper, a 1.6% surprise. Revenue of $218.06 million beat the $215.0 million consensus by 1.4% and grew 72.4% year over year. Earnings grew 675.0% from a year ago. The bigger story is the sequential trajectory. Non-GAAP EPS nearly doubled from $0.35 in the second quarter, and revenue rose 29% quarter over quarter, clearing the company's own $210-$220 million guide. The central tension is that the growth engine is now constrained less by demand than by supply and by the cash needed to secure it.
The quality of the quarter is better than the modest surprise suggests. On a GAAP basis, MaxLinear earned $0.30 per share, compared with a $0.52 loss a year ago. GAAP operating margin swung to 13.9% from -2.5% in the second quarter and -32.7% in the year-ago period. Non-GAAP operating margin climbed from 16% in the first quarter to 22% in the second and 29.5% now, which brings it to the edge of the 30% long-term target band. Gross margin also improved, with non-GAAP gross margin rising to 60.0%, so the operating leverage is coming from mix as well as volume. GAAP operating expenses fell 14% year over year as restructuring and Silicon Motion-related costs faded. Stock-based compensation and share-settled bonuses still add up to nearly $29 million a quarter, however, which keeps a wide gap between GAAP and non-GAAP profitability.
Infrastructure revenue reached roughly $125 million, up 210% year over year. The progression was $47 million in the fourth quarter of 2025, then $63 million, $85 million, and now about $125 million, and the segment is larger than all other categories combined. Management raised its 2026 optical data center outlook for a fourth straight quarter, to $250-$270 million. That figure stood at roughly $130 million at the start of the year. Visibility also lengthened considerably. Management cited bookings extending through 2027 into 2028, compared with about six months of visibility on the second-quarter call. The initial Rushmore 1.6T design win, which includes TIA attach, is now expected to ship in the first half of 2027, earlier than the mid-to-late 2027 timing discussed last quarter. Management said 1.6T ASPs are more than twice 800G levels, and it is targeting a teens share of the DSP market in about two years. Outside optical, an XGS-PON hyperscale control-plane win completed qualification with backlog for 2027, and broadband is expected to grow next year on PON share gains.
The forward guide supports the story. Fourth-quarter revenue is expected at $240-$260 million, above estimates. Non-GAAP gross margin is guided to 59%-62% and non-GAAP operating expenses to $65-$70 million, even with a seasonal decline expected in broadband and connectivity.
The risks are not trivial, and they are mostly the costs of success.
- **Supply:** Management called foundry DSP wafer capacity a binding constraint.
- **Execution:** Internal engineering resources limit how many 1.6T qualifications can run at once.
- **Cash:** Operating cash flow swung to -$13.6 million from +$4.8 million in the second quarter. Prepaid expenses and other current assets jumped to $121.6 million from $75.8 million in the quarter and $31.6 million a year ago, reflecting wafer prepayments that management expects to keep rising.
- **Debt:** The company drew $40 million on its revolver during the quarter and expanded the facility by $70 million to $200 million. Long-term debt rose to $164 million, and guided interest expense is climbing.
- **Costs and receivables:** Input cost inflation is only partially being passed through, and DSO edged up to 31 days.
- **Concentration and legal:** Growth is concentrated among a limited number of hyperscale customers, and the Silicon Motion arbitration remains unresolved.
The market setup is more complicated than the fundamentals imply. Shares spiked from an inter-earnings low of $55.93 on September 3 to a high of $113.13 on October 7. By the eve of the report they had fallen back to $75.79, 33% below that peak and 8.7% below the open after the July report. The stock still sits about 31% above its 200-day moving average of $57.99, so the longer-term uptrend is intact, but much of the speculative run has been unwound. Investor sentiment remained positive but weakened meaningfully, falling from 0.35 to 0.23. Sequential growth and momentum trend readings are positive, while AVWAP remains negative, consistent with buyers from the October spike sitting on losses.
The bottom line is that MaxLinear's operating story strengthened on nearly every axis this quarter: revenue, margins, visibility, product timing, and the full-year optical outlook. The headline beat was narrow, but the raise and the 1.6T pull-in matter more. What investors must now weigh is the working-capital and borrowing burden of securing scarce wafer capacity, along with heavy dependence on a handful of hyperscale programs. Expectations had already cooled before the report, so the debate centers less on demand and more on whether MaxLinear can fund and supply that demand without stretching its balance sheet.
Read our earnings preview for MaxLinear, Inc.: https://www.earningswhispers.com/article/MXL/20577
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 56 min | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| Oct-13 | |
| Oct-13 | |
| Oct-06 | |
| Oct-01 | |
| Sep-28 | |
| Sep-25 | |
| Aug-27 | |
| Aug-17 | |
| Aug-17 | |
| Aug-10 |
