Knowles Beats And Raises Again As Orders Outrun Capacity, But A Flat First Half Of 2027 Tempers The Story
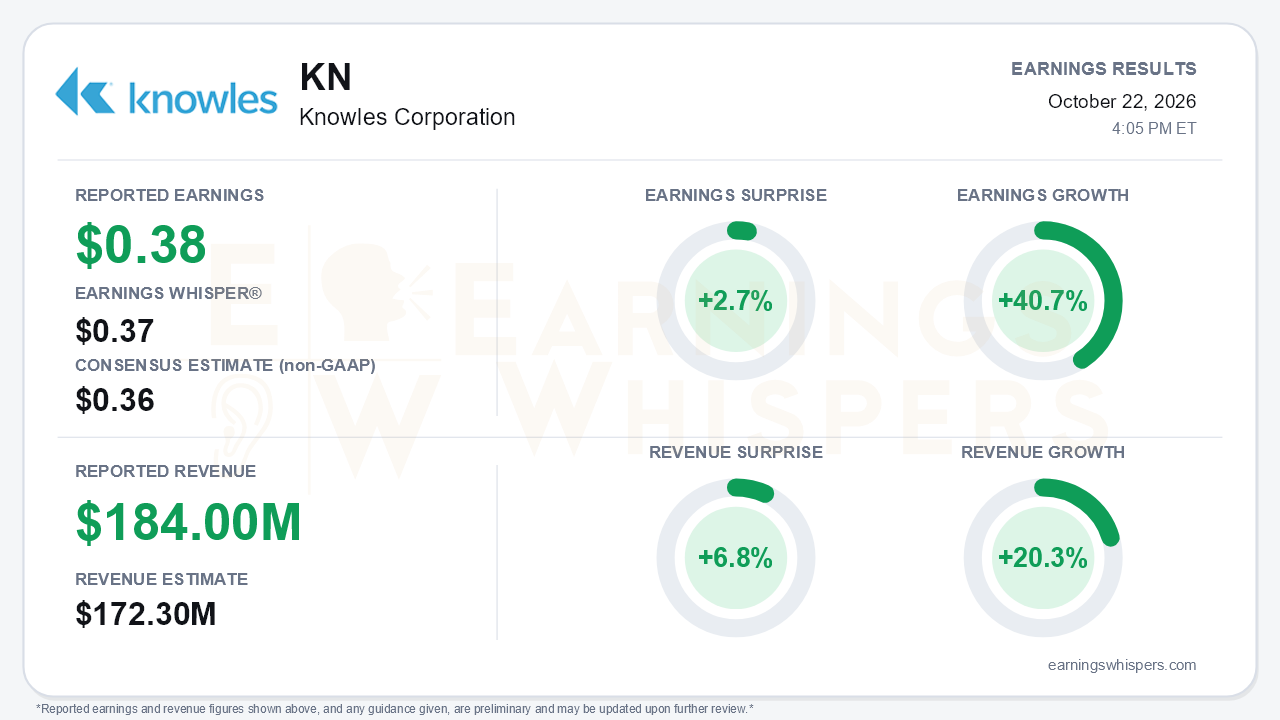
Knowles delivered its third straight beat-and-raise, and the strongest signal in the quarter came from orders, not earnings. Non-GAAP EPS of $0.38 topped the $0.36 consensus by 2.7% and edged past the $0.37 Earnings Whisper number, rising 40.7% from a year ago. Revenue of $184.0 million beat the $172.3 million consensus by 6.8% and grew 20.3%. That is a clear acceleration from 14% growth in the second quarter and 16% in the first. Management now expects 2026 revenue growth of about 16% at the midpoint of its fourth-quarter range, up from 10-12% three months ago and 'above 4-6%' at the start of the year. Fourth-quarter guidance came in above estimates. The central tension is that demand has moved ahead of Knowles' ability to supply it. The company is effectively telling investors that growth will pause in the first half of 2027 while new capacity comes online.
The quality of the beat deserves some scrutiny. A 6.8% revenue surprise produced only a 2.7% EPS surprise because profitability did not scale with sales. Non-GAAP gross margin slipped to 45.3% from 46.2% a year ago, and GAAP gross margin fell to 44.2% from 45.7%. Precision Devices (PD) gross margin rose just 10 basis points year over year to 41.6%, held back by unfavorable inventory adjustments, after expanding 140 basis points in the second quarter. Non-GAAP operating expenses held flat sequentially at $40.1 million, but they were up from $34.8 million a year earlier, and management acknowledged SG&A is rising with pulled-forward hiring. Adjusted EBIT margin still improved to 23.0% from 22.6%, and adjusted EBITDA margin reached 26.3%. The leverage is real but modest. GAAP diluted EPS from continuing operations was $0.24, versus $0.21 a year ago.
Beneath the headline, the story is really about Precision Devices. PD revenue jumped 33% to $117 million, accelerating from 25% and 17% growth in the prior two quarters. Book-to-bill climbed to 1.5 from 1.4, 1.19 and 1.06 over the preceding three quarters. Orders reached roughly $180 million, up from about $140 million. Wins included a multi-year defense radar filter order of more than $15 million, and management flagged a possible follow-on to the existing $75 million energy order. The MedTech and Specialty Audio (MSA) segment, by contrast, grew only 4% to $67 million. Management said AI-driven hearing aid launches pulled demand forward, and MSA gross margin eased to 51.9% from 53.1% in the second quarter.
The forward picture splits into two phases. In the near term, PD is running close to capacity. Management implied PD revenue will be roughly flat sequentially through the first half of 2027, with total revenue slightly down in the first quarter. The exit from the stamping business adds a 2-3% MSA headwind, concentrated in the first half. Over the longer term, capex rises to 5-7% of revenue in 2027 from a historical 3-5%, with new capacity arriving in late first quarter 2027 and fully available in the second half. Management expects 2027 growth to exceed its May 2025 Investor Day targets and reiterated a path to 30% EBITDA margins within two to three years. It also expects margins in the Cornell film business to keep climbing from the mid-30s toward 40%-plus, and it plans a new Investor Day in 2027. Bears have legitimate ammunition elsewhere too:
- semiconductor equipment demand in industrial may not be sustainable;
- the energy order could finish before any follow-on arrives;
- inventory rose to $150.3 million from $124.6 million at year-end, and receivables climbed.
Cash flow recovered in the quarter. Adjusted free cash flow was $42.6 million, though the nine-month total of $62.4 million trails last year's $81.2 million. Fourth-quarter operating cash flow is guided to $60-70 million, and buybacks stepped up to $25 million.
The market setup is more complicated than the surprise implies. Investor sentiment improved meaningfully into the report, rising from 0.21 to 0.35. Yet the stock entered earnings at $34.92, down 10.4% from the open after the July report. Shares sat 14.5% below the inter-earnings high of $40.82 set in early August and 8.6% above the late-August low of $32.16. They remain 7.2% above the 200-day moving average, so the longer-term trend is intact even after a sharp giveback from the post-July spike. Trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Knowles is now constrained by supply, not demand, which is a better problem to have. Still, investors face a flat first half of 2027, softer MSA growth and gross margins that have not kept pace with revenue. The record backlog and raised outlook make the 2027 capacity ramp the key test of whether this growth story keeps compounding.
Read our earnings preview for Knowles Corporation: https://www.earningswhispers.com/article/KN/20572
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Sep-30 | |
| Sep-29 | |
| Aug-12 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-06 | |
| Jul-06 | |
| Jul-01 | |
| Apr-24 |
