JAKKS Pacific Beats On Accelerating Sales, But Pulled-Forward Revenue, Flat Margins And A Lower Tax Rate Complicate The Story
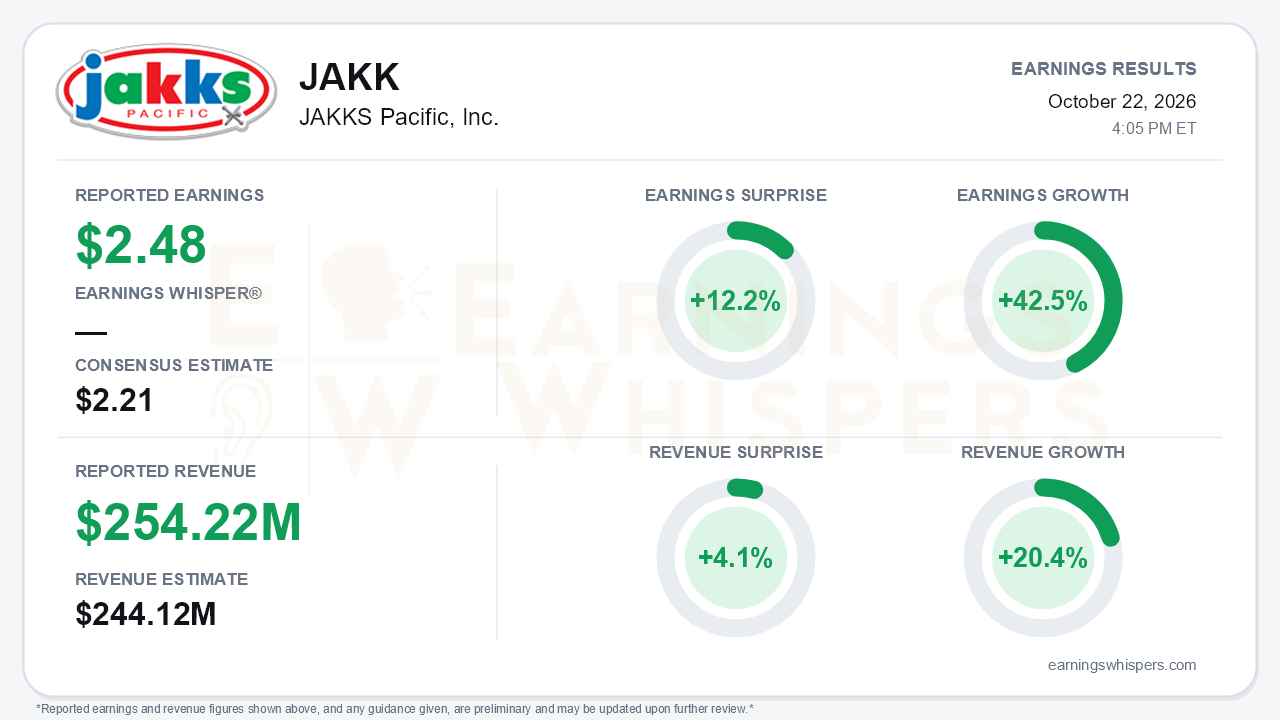
JAKKS Pacific delivered its strongest quarter of the year. Third-quarter GAAP earnings of $2.48 per share beat the $2.21 consensus by 12.2% and grew 42.5% year over year. Revenue of $254.22 million topped the $244.12 million estimate by 4.1% and rose 20.4%. Growth is clearly accelerating. Quarterly sales went from a 6% decline in Q1 to gains of 17% in Q2 and 20% in Q3, and year-to-date growth reached 13%. That is well ahead of the low-to-mid single-digit plan management set at the start of the year. The central tension is that some of that strength was borrowed from the fourth quarter, and the margin structure underneath the top line is not improving.
The quality of the earnings beat deserves scrutiny. Pre-tax income rose 27% to $37.6 million, roughly in line with the 27% gain in operating income. Net income jumped 50%, however, because the tax provision fell to $7.7 million from $9.8 million despite higher profits. That implies an effective rate near 21% versus roughly 33% a year ago. A meaningful share of the EPS growth therefore came below the operating line. Gross margin of 32.1% improved only 10 basis points year over year. Cost of goods actually rose 60 basis points as a share of sales, offset by lower tooling amortization. Operating leverage came mainly from G&A, which grew 13% against 20% sales growth. Adjusted EPS of $2.68, which excludes stock compensation, compared with $1.80. Adjusted EBITDA rose 22% to $44.4 million, lifting trailing-twelve-month adjusted EBITDA to $45.7 million from $37.8 million at Q2.
The operating story is overwhelmingly a U.S. one. North America sales rose 28% and U.S. sales rose 31%, while International fell 4%. International had grown 38% in Q1 and 3% in Q2, and its year-to-date growth slowed to 7% from 20% at the half. Canada fell 35.5% and Latin America fell 23.4%. By category, Dolls, Role-Play and Dress-Up accelerated to 29% growth from 12% in Q2, led by Disney Princess and Frozen. Management said point-of-sale at its top two accounts remains up double digits. Action Play & Collectibles grew 19% on Super Mario Galaxy, though action point-of-sale was roughly flat against tough Sonic 3 comparisons. Costumes reached $62 million, recovering to slightly above 2024 levels. Management's characterization of the year shifted from "roughly in line" in Q1, to "on track, potentially exceeding" in Q2, to a clearly better year than 2025. CEO Stephen Berman said he feels "extremely confident."
The call added credible catalysts, mostly aimed at 2027:
- The Dollhouse collector platform is expanding, including a Walmart-exclusive horror line that sold out at NYCC.
- Walmart private-label listings have doubled, with a stroller ranking as the retailer's top new fall item.
- The 2027 tentpole slate now includes a Simpsons movie alongside Sonic 4 and Frozen 3.
- An anime and VTuber initiative is drawing enthusiastic retailer feedback.
- The Toys R Us reopening of roughly 120 stores, mostly pop-ups, adds a new outlet.
Bears also have legitimate near-term ammunition. The CFO said some Q4 sales were pulled into Q3, which sets up a softer holiday comparison. There is no new entertainment release supporting holiday 2026. Resin and diesel prices are pressuring product and freight costs, and the CFO said there is little scale leverage left in gross margin, which has slipped from 33.4% in Q1. Direct selling expenses rose 27% on heavier promotion, and tariff guidance remains pending.
The balance sheet improved. Inventory fell to $63.8 million from $71.5 million, and cash rose to $45.1 million from $27.8 million. Nine-month operating cash flow swung to a $17.4 million inflow from a $24.8 million outflow. Receivables climbed to $240 million, with days sales outstanding edging up to 87, consistent with heavier quarter-end shipments. The quarterly dividend was maintained at $0.25.
The market setup is more complicated than the surprise implies. Shares entered the report at $29.27, up 35% since the open after the July report. That price sits within 1% of a 52-week high set on October 21 and nearly 30% above the 200-day moving average. Price, momentum and AVWAP trend readings are all positive. Investor sentiment, meanwhile, slipped modestly further into negative territory, from -0.02 to -0.09. That is not a dramatic shift, but it suggests investors were growing more cautious even as the stock rallied.
The bottom line is that JAKKS produced a genuine acceleration in sales, cash generation and EBITDA, and the call preserved a credible growth story for 2027. But the EPS beat was flattered by a lower tax rate, gross margins are flat to slipping under new cost pressure, International has stalled, and management acknowledged that Q4 revenue was pulled forward. With the stock already pricing in much of the good news near its highs, the fourth-quarter holiday sell-through and margin trajectory now matter more than this quarter's headline beat.
Read our earnings preview for JAKKS Pacific, Inc.: https://www.earningswhispers.com/article/JAKK/20571
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-05 | |
| Oct-01 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-13 | |
| May-19 | |
| May-18 | |
| May-15 | |
| May-12 | |
| May-07 | |
| May-01 |
