Enova Tops Consensus But Misses The Whisper As Accelerating Lending Growth Meets The Loss Of Its Bank Catalyst
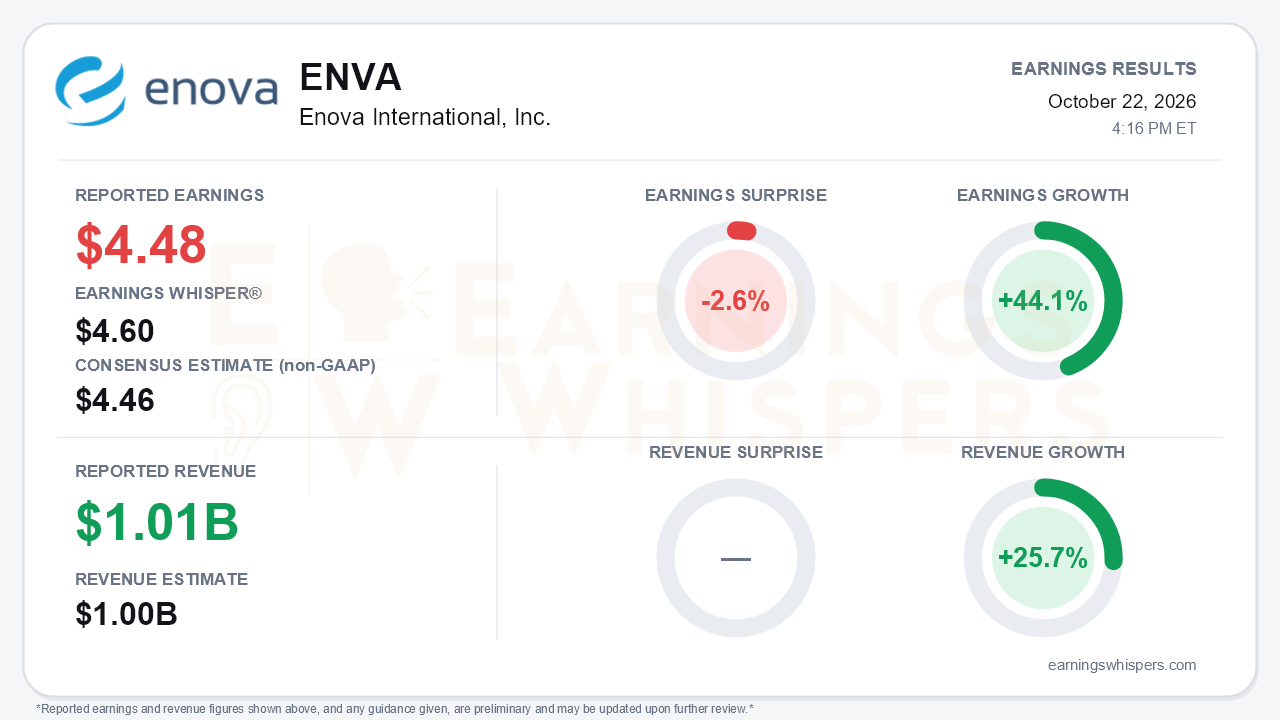
Enova International delivered a quarter that was strong on almost every operating measure yet still fell short of what the most bullish investors wanted. Adjusted EPS of $4.48 edged past the $4.46 consensus but missed the $4.60 Earnings Whisper number by 2.6%. Revenue of $1.009 billion, the first $1 billion quarter in company history, beat consensus by 0.9% and grew 25.7% year over year. Earnings Whispers calculates year-over-year EPS growth of 44.1%. Management's own comparison shows adjusted EPS up 33% from $3.36, and investors will see that smaller figure in the release. That is the central tension. The lending engine is accelerating, but the quarter also ended the Grasshopper Bank combination that had anchored the bull narrative for most of the year.
The growth trajectory itself is hard to fault. Revenue growth has stepped up from 15% in the fourth quarter of 2025 to 17%, 22% and now 26%. Originations rose 31% to $2.6 billion, the 12th straight quarter above 20%. Combined receivables reached a record $5.9 billion, up 30%. The sharpest change came in consumer lending: consumer originations jumped 37% versus 23% in Q2 and 10% in Q1, and consumer revenue growth nearly doubled to 21%. Net revenue margin held at 61%, above management's 55-60% range. The consolidated net charge-off ratio improved to 8.1% from 8.5% a year earlier, with consumer charge-offs 100 basis points better.
The quality of the beat still deserves scrutiny, because growth is being bought with heavier spending and is starting to show up in early-stage credit. Marketing expense climbed to $230 million from $147 million, about 23% of revenue against a roughly 20% guide. That pushed adjusted EBITDA margin down to 26.6% from 27.1% even as revenue surged. Consolidated 30-plus-day delinquencies rose to 8.0%, up from 7.5% in Q2 and 7.2% a year ago, and SMB delinquencies rose 40 basis points sequentially. SMB charge-offs held at 4.8%, so this is not yet a loss problem, but it is the metric bears will watch most closely. SMB growth is also cooling gradually:
- receivables growth eased from 39% to 36% to 34% across the first three quarters;
- origination growth slowed to 28% from 42% in Q1.
Management responded by raising the bar again. The fourth-quarter guide calls for revenue growth of roughly 25% and adjusted EPS growth of 30-35%, above the roughly 30% it had guided for Q3. Full-year adjusted EPS growth guidance has climbed from at least 20% at the start of the year to 30-35%. G&A guidance fell to 4.5-5% of revenue. Funding also improved:
- cost of funds slipped to 8.0%;
- the company completed its largest term securitization at tighter spreads;
- liquidity rose to $1.3 billion from $929 million.
Management was also candid about the limits of the guide. It said 30%-plus consumer origination growth will not persist, a heavier new-customer mix keeps marketing intensity elevated, and the consumer net revenue margin should drift back toward about 50%.
The bigger strategic shift is the withdrawal of the bank regulatory applications, which ends the Grasshopper deal. Over the prior three calls management had pitched more than 25% adjusted EPS accretion, cheaper deposit funding and broader geographic reach for consumer products. All of that is now off the table. Management argued the decision does not diminish growth and pivoted toward organic adjacencies: a deposit advance product, secured consumer lending and SMB embedded finance. It also pivoted toward buybacks. Repurchases more than doubled to $46 million in Q3, October purchases had already matched that total, and $252 million of capacity remains. Even so, diluted share count was essentially flat year over year, so buybacks have so far mainly offset dilution.
The market had already priced in plenty of doubt before the report. Shares hit a 52-week high of $267.45 in mid-August, then slid to $164.77 on October 1. They entered the report at $180.05, down 22.2% since the opening after the July report and about 1.7% below the 200-day moving average. Investor sentiment nonetheless became more positive, rising from roughly neutral at 0.03 to 0.18. That is a modest improvement rather than enthusiasm. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while AVWAP remains negative, consistent with a stock whose fundamentals have outrun its price action.
The bottom line is that Enova's core business is accelerating, guidance keeps moving higher, and funding and liquidity have rarely looked better. The whisper miss is marginal next to that. However, the loss of the bank catalyst removes a meaningful source of future earnings upside. Rising delinquencies and above-plan marketing spend also give bears legitimate ammunition. With the stock sitting well off its August peak and near its 200-day average, the debate now rests on whether organic growth and buybacks can carry the story without the bank.
Read our earnings preview for Enova International, Inc.: https://www.earningswhispers.com/article/ENVA/20565
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-08 | |
| Oct-08 | |
| Sep-17 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-14 | |
| Jul-31 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-10 |
