AppFolio Clears The Whisper By A Penny, But A Trimmed Margin Ceiling And Slowing Subscriptions Test A 35% Rally
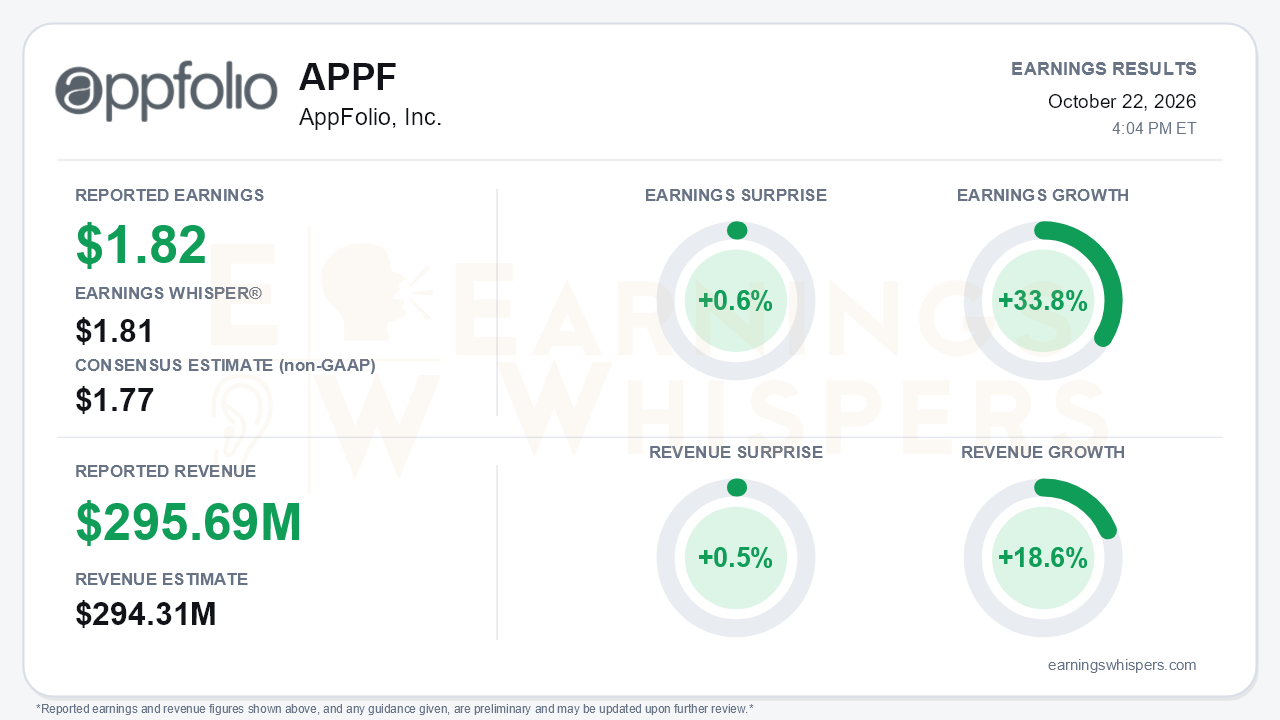
AppFolio delivered the kind of quarter that is easy to admire and harder to get excited about. Non-GAAP earnings of $1.82 per share topped the $1.77 consensus and edged past the $1.81 Earnings Whisper number, a 0.6% beat. Revenue of $295.69 million beat consensus by 0.5%. Earnings grew 33.8% year over year on revenue growth of 18.6%, so profit is still compounding far faster than sales. The central tension is that the beat was narrow and came from cost discipline rather than any reacceleration in growth. Management also trimmed the top of its full-year margin range to fund heavier sales spending. For a stock that had run roughly 35% since the last report, a steady quarter may not be enough.
The gap between earnings growth and revenue growth came almost entirely from operating leverage. GAAP operating income rose 64% to $57 million, a 19.4% margin compared with 14.1% a year ago. Non-GAAP operating margin expanded to 27.3% from 23.5%. On a non-GAAP basis, research and development fell to 15% of revenue from 18%, and general and administrative expense dropped to 6% from 8%. Headcount grew only 2% against 19% revenue growth. GAAP earnings growth was more muted at $1.29 per diluted share versus $0.93, because the income tax provision jumped to $13.6 million from $3.1 million. A smaller diluted share count, 35.6 million versus 36.3 million, also helped per-share comparisons after $129 million of year-to-date buybacks, though repurchases slowed to just $4.2 million in Q3. Operating cash flow rose to $97 million, but it fell as a share of revenue to 32.7% from 34.5%. Cash and investments climbed to about $307 million.
Beneath the headline, growth is steady but gently decelerating. Revenue growth held at 19%, matching Q2, after sliding from 22% in Q4 of fiscal 2025 and 20% in Q1. Value Added Services, at $232 million, remains the engine, though growth eased to 21% from 22%. Subscription services growth slowed to 14% for a second straight quarter, down from 18% in Q1 and 17% in Q4 of fiscal 2025. Units under management rose 8% to 9.8 million, a solid but not accelerating pace. Management again flagged that unit expansion among existing customers is pacing slower than last year and expects that to persist through Q4. That is a meaningful admission for a business whose payments-driven model depends on unit growth.
Guidance carried the same mixed message. AppFolio raised the low end of its full-year revenue outlook to $1.122–$1.127 billion, its third consecutive increase, lifting midpoint growth to 18.3%. However, management narrowed non-GAAP operating margin guidance to 26.5%–27.5% from 26.5%–28.0%. The reason is a deliberate step-up in sales and marketing, which reached 15% of revenue versus 13% a year ago. Subtracting nine-month revenue of $839 million from the full-year range implies Q4 revenue of roughly $283–$288 million, below the quarter just reported. Part of that reflects a difficult comparison against one-time Stack partnership revenue in Q4 2025. Management also cited rising data center costs from AI usage and payments mix as a pressure on cost of revenue.
The catalyst list is long and product-heavy. It includes:
- banking partnerships with Column and Enterprise Bank & Trust that enable automated transaction matching;
- a Receptionist Performer and an Accounting Performer beta that saves about 17 hours a month;
- Resident Messenger resolving more than 30% of conversations without escalation;
- a Claude connector now available to all customers;
- a Stack ecosystem that has grown to 5.6 million connected units across about 100 partners;
- enterprise wins, including Renosi's roughly 8,000-unit standardization and a 14,000-unit Eucalyptus migration.
The heavier sales spending reads as a bet that these products can reignite unit expansion. That bet has not yet shown up in the subscription line.
The market setup is more complicated than the beat implies. Shares opened at $161.24 after the July report, briefly fell to $155.55, and then rallied to $236.58 on September 1. Heading into this report they sat at $217.20, up 34.7% since the prior earnings open, about 18% above the 200-day moving average and 8% off the quarterly high. Investor sentiment moved the other way, falling from -0.15 to -0.31 and becoming meaningfully more negative even as the price climbed. Price-based trend readings remain largely positive while sequential growth is neutral, consistent with a stock that has rallied faster than its underlying growth rate.
The bottom line is that AppFolio remains a high-quality compounder whose margin expansion is real and well funded by cost discipline. The quarter, however, offered little new upside. The beat was thin, subscription growth has cooled, existing-customer unit expansion is lagging, and the margin ceiling came down to pay for growth that has yet to materialize. After a 35% run and with sentiment already souring, bulls need the new AI and payments products to translate into faster unit growth. Bears have legitimate ammunition until they do.
Read our earnings preview for AppFolio, Inc.: https://www.earningswhispers.com/article/APPF/20554
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Sep-29 | |
| Sep-24 | |
| Aug-26 | |
| Aug-20 | |
| Aug-14 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 |
