BeFra Beats On Revenue But Misses On EPS As The Tupperware Boost Masks A Slowing Organic Core And Another Jafra Stumble
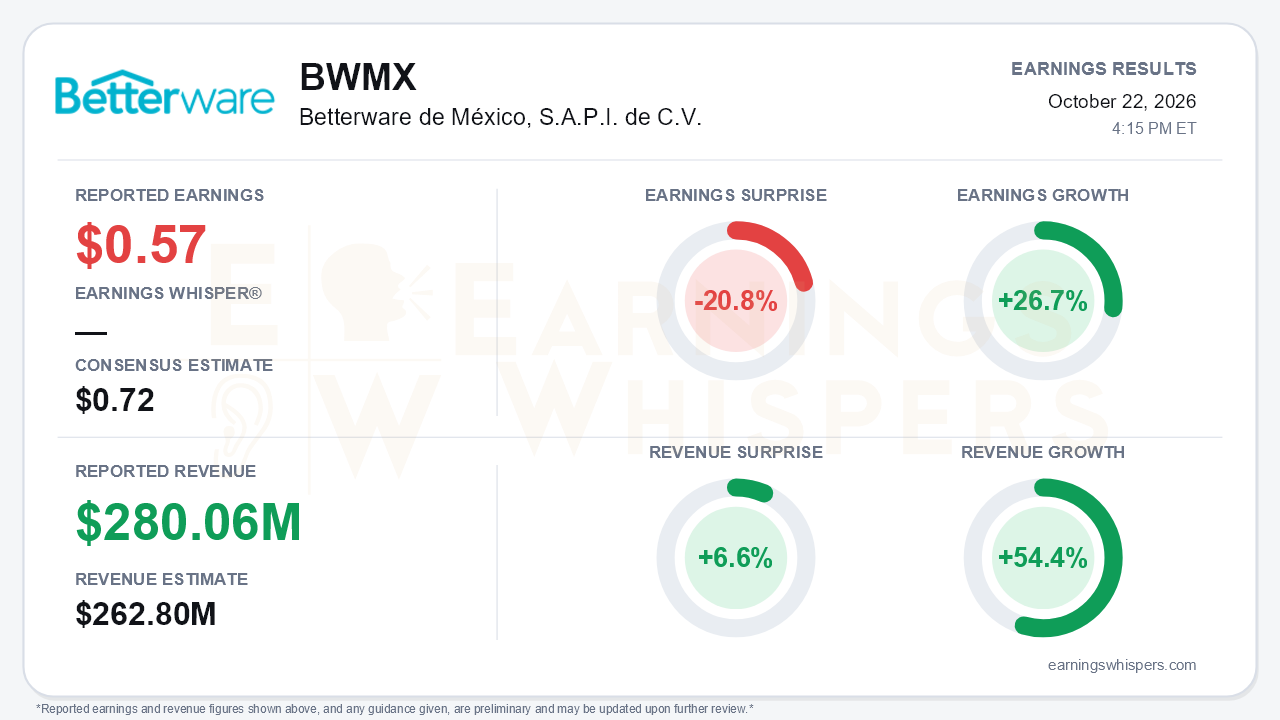
Betterware de México (BeFra) delivered a quarter of two very different stories. Reported earnings of $0.57 per share missed the $0.72 consensus by 20.8%. Revenue of $280.06 million beat the $262.8 million estimate by 6.6%. Earnings still grew 26.7% year over year and revenue rose 54.4%, driven by the first full quarter of Tupperware Latam. That is the central tension. The acquisition is adding scale, cash flow and diversification faster than many expected, while the legacy business is slowing and Jafra has stumbled again.
The quality of the miss deserves scrutiny. Most of it arose below the operating line. In pesos, operating income rose 40.2%, roughly in step with the 43.1% revenue gain. Income tax expense, however, jumped 75.3% against a 43.5% rise in pre-tax income, which held net income growth to 24.2%. Management called the tax recognition temporary and expects the full-year effective rate to normalize in the mid-30s. Investors should treat that as guidance, not a reported outcome. Margins were softer. Consolidated gross margin fell 438 basis points to 64.1% and EBITDA margin slipped to 20.9% from 21.4%. Most of the gross-margin decline reflects Tupperware's lower-gross, higher-EBITDA model, but Betterware also lost about 200 basis points to elevated freight costs. Cash flow was the standout. Free cash flow rose 91.3% to MXN 1,059 million, or 105% of EBITDA. That figure includes a MXN 174 million benefit from an acquisition-related balance reclassification, so underlying conversion was strong but not quite as dramatic as the headline suggests.
Beneath the consolidation effect, the trend is less flattering. Organic revenue growth slowed to 2.3% from 4.1% in the second quarter. Organic EBITDA fell to MXN 650 million from MXN 722 million a year ago. Betterware was the bright spot, growing 9.7% (Mexico +8.5%) for a third straight quarter of growth, though its EBITDA rose only 3.1%. Jafra relapsed. Revenue fell 2.8% and EBITDA dropped 20.1%, just one quarter after a Q2 rebound that management had framed as a corrected tactical issue. CEO Andrés Campos is now interim managing director of Jafra Mexico for an expected six to twelve months. This is the second Jafra execution problem in a year, and the Jafra Plus app has slipped again to early 2027. Bears have legitimate ammunition here.
Guidance reflected the same split. BeFra raised post-acquisition revenue growth guidance to 24%-26% from 18%-22% and reaffirmed a 19% full-year EBITDA margin. However, it narrowed organic growth guidance to 4%-5% from 4%-8%, effectively cutting the midpoint from 6% to 4.5%. The Tupperware data supports the deal thesis. Core direct-selling revenue grew 14.0%, with Mexico up 23.0% and Brazil's decline moderating to 3.3% from 10%-15% before the acquisition. Tupperware's reported revenue fell 6.8% because discontinued B2B and non-core sales dropped out, and management says that drag should not recur next quarter. Tupperware's EBITDA margin of 26.1% was well below the prior year's combined 31.1%, but in line with the mid-twenties level management expects going forward. Other positives:
- The cash conversion cycle shortened to 50 days from 78.
- Net debt/EBITDA improved to 1.65x after MXN 431 million of debt repayment.
- Interest coverage rose to 6.91x.
- The MXN 250 million dividend was maintained.
Management has not yet quantified synergies.
Investor sentiment improved materially heading into the report, moving from -0.25 to +0.04. That is a shift from moderately negative to roughly neutral, not a sign of enthusiasm. The stock tells a more cautious story. As of the pre-report snapshot, shares traded at $15.89. That is 8.3% below the open after the July report, 7.7% under the 200-day moving average and 11% below the inter-earnings high of $17.85 set in late July. The stock sat just 4.9% above its September low of $15.15. Price and AVWAP trend readings remain negative, even as momentum has turned positive. The market has been discounting the integration story rather than rewarding it.
The bottom line is that BeFra's quarter strengthened the case for the Tupperware acquisition: revenue beat, total growth guidance rose, cash generation surged and leverage fell. It also weakened confidence in the organic franchise. The EPS miss was largely tax-driven, but Jafra's relapse, persistent freight pressure and the organic guidance cut are real fundamental concerns. With shares in the lower part of their range and below the 200-day average, the next leg likely depends less on Tupperware, which is performing, and more on whether Jafra can show the turnaround management is again promising.
Read our earnings preview for Betterware de México, S.A.P.I. de C.V.: https://www.earningswhispers.com/article/BWMX/20558
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-08 | |
| Sep-15 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-21 | |
| Jul-21 | |
| Jul-09 | |
| Jun-08 | |
| Jun-02 |
