Infosys Misses And Trims FY27 Again As Record Deal Wins And AI Growth Point Past A Fading Core
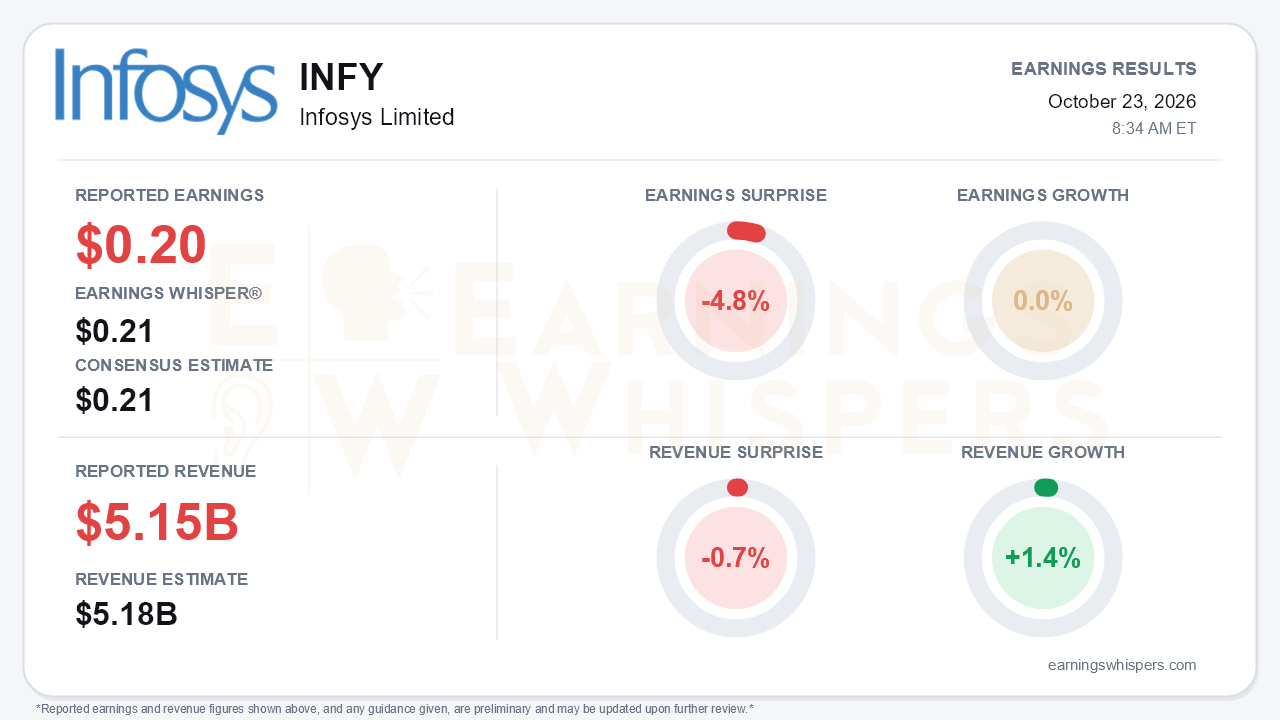
Infosys (NYSE: INFY) delivered a modest miss on both lines for its fiscal second quarter and lowered its full-year outlook again. EPS of $0.20 fell short of the $0.21 consensus and the $0.21 Earnings Whisper number by 4.8%, and earnings were flat year over year. Revenue of $5.145 billion grew 1.4% but missed the $5.18 billion consensus by 0.7%. FY27 constant-currency revenue guidance now stands at 1%-2%, down from 1.5%-3% after the first quarter and from 1.5%-3.5% when the year began. The central tension is clear: the core services business is still decelerating, while the longer-dated pipeline has rarely looked better. A record-sized mega deal and surging AI revenue argue for a better FY28, but they do little for the next two quarters.
The quality of the quarter deserves scrutiny beneath the stable 21.0% operating margin. Operating profit rose only about 1% to $1.079 billion. Lower other income ($77 million versus $100 million) and a higher tax bill pushed net profit down to $817 million from $839 million, and basic EPS in dollars slipped 0.3%. Management highlighted 8.7% EPS growth in rupee terms, a reminder that currency is flattering the narrative. Currency also propped up the margin. A 40-basis-point currency tailwind and 20 basis points from Project Maximus offset a 70-basis-point post-sale support swing and 20 basis points of acquisition costs. Free cash flow fell 15.7% year over year, although conversion remained healthy at 113% of net profit. The release puts free cash flow at $928 million, while the call analysis cites $922 million. Either way, it was slightly below the first quarter.
The call made the slowdown explicit. Year-over-year constant-currency growth decelerated to 1.5% from 2.4% in the first quarter and 4.1% in the fourth quarter of FY26. The CFO cited several pressures:
- softer volumes;
- pricing pressure from competitors and from clients demanding AI-driven productivity givebacks;
- weak discretionary spending in US-centric retail and high tech, including a client-specific ramp-down and lower third-party revenue.
The offshoring shift and a European manufacturing client together weigh roughly 2 points on growth. The second half faces wage hikes, continued pricing intensity and December-quarter furloughs. The guidance trajectory deserves care. The prior 1.5%-3% range included about 1.7 points from acquisitions, so the organic outlook implied by 1%-2% is thin. The source material variously describes this as the second straight cut and the third consecutive one, depending on whether the initial FY27 range, which came in below the prior year's raised outlook, is counted. Management's tone has moved from raising guidance a year ago to defending deal discipline and insisting that AI-driven deflation is "finite."
The offsetting evidence is substantial. Large-deal TCV jumped to $5.2 billion, 62% net new, from $3.6 billion in the first quarter and $3.2 billion in the fourth quarter. That total included a net-new mega deal of over $2 billion over seven years, which management expects to add more than 1% to FY28 growth once it ramps from late in the fourth quarter. A $1 billion renewal and a pipeline holding other mega deals add to the outlook. AI revenue reached 10.5% of the total, up 29% sequentially, compared with 8.2% in the first quarter and 5.5% three quarters ago. Net headcount grew by 4,000 after shrinking in the first quarter, attrition eased, and the interim dividend rose to Rs 26. Financial services, energy and utilities, manufacturing, and Europe are growing. Bears still have legitimate ammunition: pricing pressure, a soft North America, and a CEO transition to Ashish Dash in April 2027.
The market setup is more complicated than the miss implies. Shares hit a 52-week low of $10.12 on October 8, then rallied about 31% to $13.30 on October 22, the day before the report. They entered earnings within 1% of their inter-earnings high and are up 27.2% since the open after the July report. The stock is now only 1.5% above its 200-day moving average. Investor sentiment swung sharply, from a clearly negative -0.49 to a roughly neutral +0.03. Expectations had therefore rebuilt quickly ahead of a report that delivered a miss and a lower outlook, though guidance moved toward where estimates already sat. The Earnings Whispers trend signals are mixed, with AVWAP positive but momentum still negative.
The bottom line is that Infosys traded near-term credibility for long-term visibility. FY27 is shaping up as a 1%-2% growth year with currency-assisted margins and flat dollar earnings. The record deal flow and AI ramp give FY28 a credible reacceleration story, but that story starts largely after the furlough season. With the stock having rallied into the print and sentiment reset to neutral, the burden now shifts to converting those wins into revenue before pricing pressure erodes them.
Read our earnings preview for Infosys Limited: https://www.earningswhispers.com/article/INFY/20609
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| 10 hours | |
| 12 hours | |
| Oct-19 | |
| Oct-12 | |
| Oct-11 | |
| Oct-11 | |
| Oct-10 | |
| Oct-10 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 |
