Flagstar Misses As Third Straight Guidance Cut Pushes Its Turnaround Into 2028
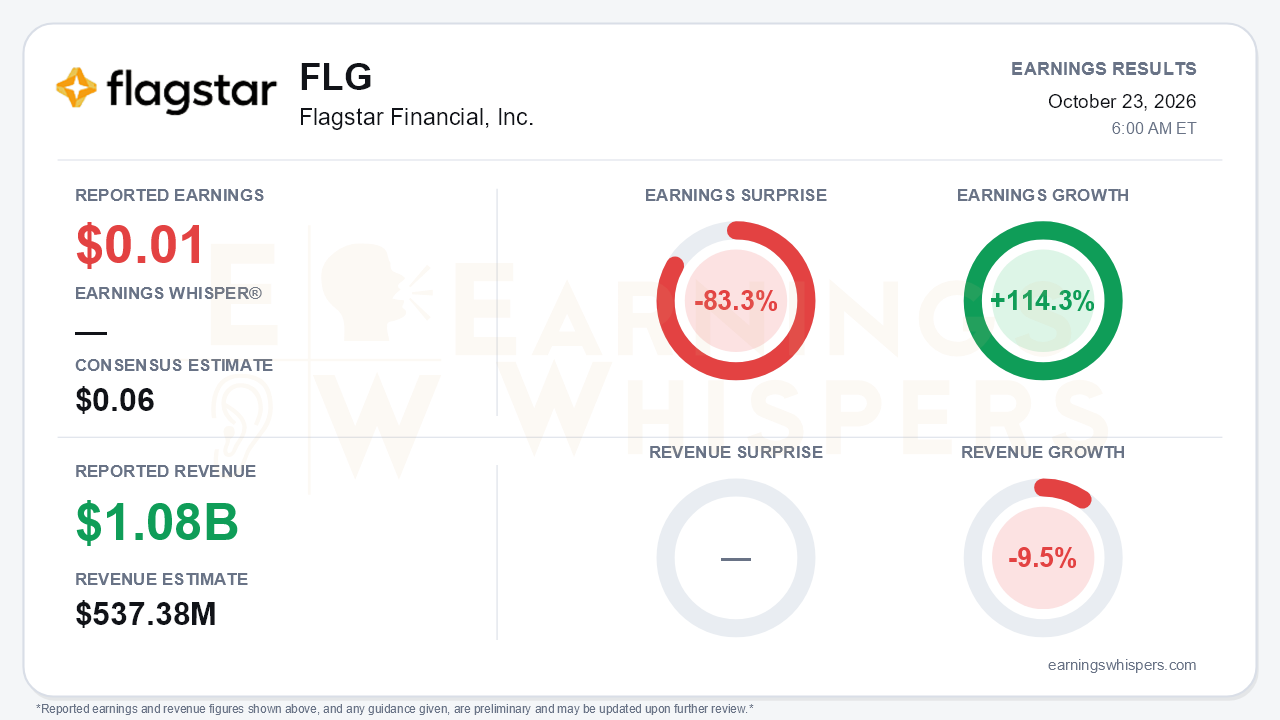
Flagstar Financial earned just $0.01 per share in the third quarter, missing the $0.06 consensus by 83.3%. That figure flatters the quarter. The penny required a $22 million income tax benefit from settling a 2019-2021 federal tax audit, because the bank posted a $10 million pretax loss. Earnings grew 114.3% year over year, but that reflects a swing from a $0.11 loss in last year's third quarter rather than real profitability. The bigger story is the outlook. Management cut guidance for the third consecutive quarter, roughly halved its 2027 EPS target, and moved peer-level profitability from 2027 to 2028.
The revenue picture needs context. On Earnings Whispers' basis, revenue was $1.082 billion, beating the $537.38 million consensus by 101.3% while falling 9.5% from a year ago. That comparison mixes different definitions. The bank's own net revenue measure, net interest income plus non-interest income, was $530 million, up 3% sequentially and slightly below the consensus figure. Underneath, operations did improve:
- Net interest income rose 5% to $460 million.
- Net interest margin widened four basis points to 2.17%, and management said the September margin was 2.23%.
- Adjusted pre-provision net revenue rose 6% to $66 million.
Those gains were consumed by a $76 million provision, up from $18 million in the second quarter. Net charge-offs actually fell to 0.49% of loans from 0.66%. The bank said the larger provision mainly reflected higher interest rates, including their effect on the New York City rent-regulated multi-family book, while net charge-offs set its size and the allowance stayed flat.
That is the central tension. The commercial bank management is building is working. Commercial and industrial loans rose $2.0 billion, or 11%, to $20.6 billion, matching the second quarter's pace. Originations reached $2.9 billion, and banker headcount grew to 164 from 124 at the start of the year. C&I loans now make up 24% of assets, versus 17% at year-end 2025. Commercial deposits grew about $600 million. The legacy book is moving the other way:
- Criticized and classified loans jumped $670 million, or 6%, reversing declines in the prior two quarters.
- Multi-family loans 30 to 89 days past due climbed to $392 million from $233 million.
- Commercial real estate loans 30 to 89 days past due rose to $79 million from $30 million.
- Non-accrual loans stalled near $2.8 billion, and the year-end target slipped to about $2.6 billion from $2.3 billion.
Management tied the pressure to a forward curve that now assumes four rate hikes. Those hikes push up cap rates on rent-regulated buildings, particularly in the Bronx, and squeeze debt-service coverage. The New York City rent freeze that took effect October 1, combined with rising operating costs for landlords, adds to the strain.
The guidance reset is severe:
- 2026 EPS fell to $0.10-$0.15 from $0.40-$0.50.
- 2027 EPS fell to $0.85-$0.95 from $1.60-$1.70, against an original $1.90-$2.00.
- The new 2028 range of $1.60-$1.70 is essentially last quarter's 2027 target, delayed a year.
- Year-end 2027 assets are now projected at $92.1 billion rather than $100 billion.
- The year-end 2026 asset forecast of $82.1 billion sits below the current $87.4 billion.
- Fee income guidance was cut by roughly $80-$100 million on weaker mortgage gain-on-sale.
- Deposit growth assumptions were reduced as competitors price CDs near 4.75%.
- 2027 expense guidance moved higher.
- Buybacks are paused through the fourth quarter.
Credibility suffers here as well. Last quarter, management described a one-to-two-quarter delay as its worst case.
Bulls still have specific catalysts:
- About $12 billion of multi-family loans with coupons below 3.9% reset or mature between October 2026 and December 2027, with another $7 billion in 2028. Management frames this as a mechanical driver of 2027 earnings.
- Fourth-quarter margin guidance of 2.20%-2.25% points to continued expansion.
- A $10.7 billion floating-rate CRE book leaves the bank roughly neutral to slightly asset-sensitive if rates rise.
- CET1 of 12.38% still implies about $1.2 billion of excess capital at the low end of the target range.
Capital is moving the wrong way, though. CET1 fell from 13.16% last quarter. Tangible book value per share dropped to $17.05 from $17.51 as unrealized losses widened. The completed $250 million buyback retired about 19.1 million shares at roughly $13, above where the stock now trades.
The market had largely priced in disappointment before the release. As of October 22, shares were $11.44:
- down 19.7% since opening at $14.25 after the July report;
- 15.3% below the 200-day moving average of $13.51;
- just 5% above the inter-earnings low of $10.90 set on October 19;
- more than 21% below the quarter's $14.59 high, which came on the day of the last report.
The Earnings Whispers trend signals are mostly negative, with price, sequential growth and AVWAP readings all pointing down. Investor sentiment remained positive but softened modestly, slipping to 0.237 from 0.287. That reading came before the scale of the guidance cut was known.
The bottom line is that Flagstar's franchise rebuild is real but is being outrun by the legacy multi-family book and the rate environment. Margin expansion, C&I growth and lower charge-offs are genuine improvements. But a third straight guidance cut, worsening credit migration, paused buybacks and a target that slid a full year give bears legitimate ammunition. The investment case now depends on loan repricing delivering in 2027 before rent-regulated credit deteriorates further. Investors have had little reason to take that timeline on faith.
Read our earnings preview for Flagstar Financial, Inc.: https://www.earningswhispers.com/article/FLG/20606
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 2 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| Oct-09 | |
| Sep-08 | |
| Aug-06 |
Flagstar Bank data breach settlement: Find out if you qualify for up to $25,000
FLG
Yahoo Personal Finance
|
| Aug-05 | |
| Aug-05 | |
| Jul-27 | |
| Jul-24 | |
| Jul-24 | |
| Jul-24 | |
| Jul-24 | |
| Jul-24 |
