Eastern Bankshares Posts Record Operating Earnings And Cleaner Credit, But Rising Deposit Costs Cloud The Margin Story
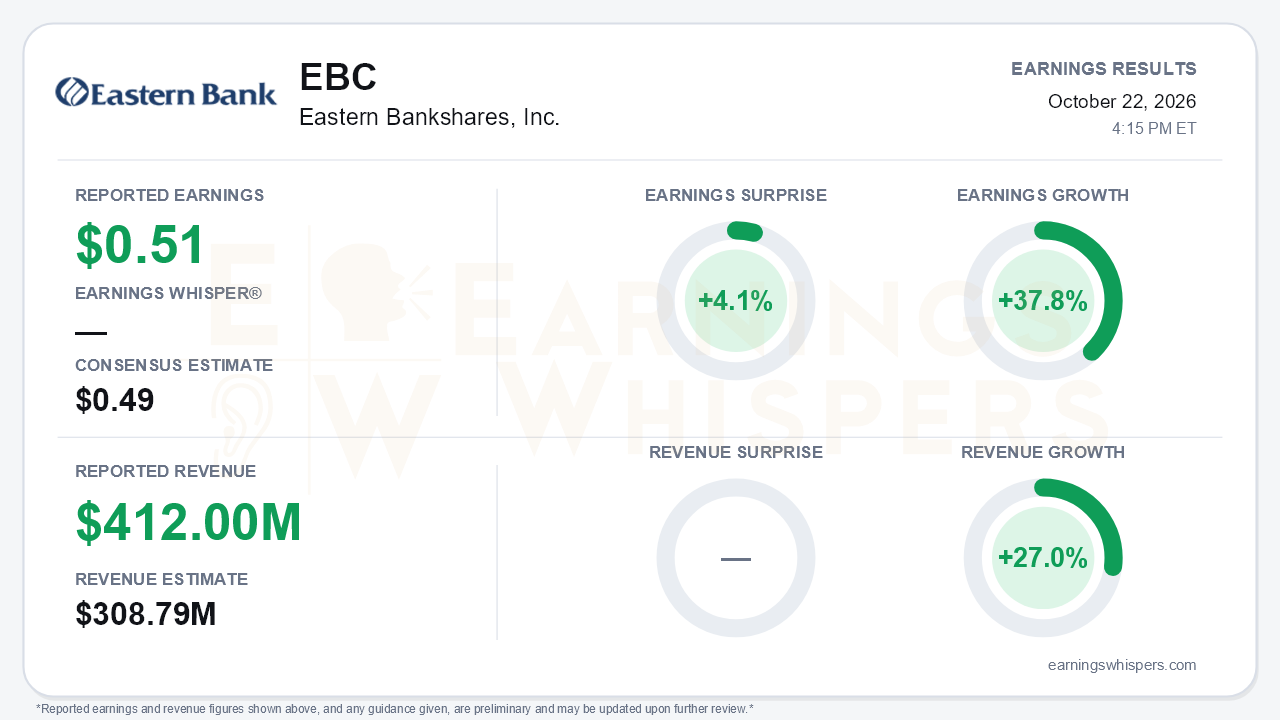
Eastern Bankshares (NASDAQ: EBC) delivered the cleanest quarter since closing the HarborOne merger. Earnings of $0.51 per share beat the $0.49 consensus by 4.1% and grew 37.8% year over year. For the first time post-merger, GAAP and operating results were identical, at $111.0 million or $0.51 per share. That is a record operating figure, and it continues a clear progression from $0.40 in the first quarter to $0.49 in the second. The central tension is that Eastern is earning more through cost discipline, credit normalization, and buybacks. Its core spread engine, however, slipped as deposit competition intensified more than management expected.
The headline growth figures need context. The 37.8% EPS growth compares with year-ago operating EPS of $0.37. On a GAAP basis, diluted EPS actually dipped from $0.53, because the prior-year quarter carried a large tax benefit. The reported $412.0 million revenue figure, up 27.0% and well ahead of the $308.79 million consensus, reflects a gross measure: total interest income plus noninterest income. The company's own net revenue was $306.6 million, slightly below the second quarter's $309.5 million. Investors should therefore read the 33.4% revenue surprise largely as a definitional gap rather than a blowout.
The operating gains came from three sources:
- **Net interest income** rose $5.9 million on balance-sheet growth.
- **Operating expenses** fell $6.7 million, pushing the operating efficiency ratio down to 47.5% from 49.0%.
- **Operating return on tangible common equity** climbed to 15.7% from 15.3% in Q2 and 12.8% in Q1.
Some of the expense relief was soft. It included lower retirement-benefit costs, the absence of second-quarter shareholder advisory fees, and a release of unfunded commitment reserves. Operating fee income also fell about 16%, as equity-market-linked retirement investments and non-recurring loan-sale gains reversed.
The call made clear that the margin story deteriorated. Net interest margin fell 4 basis points to 3.62% as deposit costs jumped 9 basis points to 1.56%, with a September spot rate of 1.59%. That compares with just a 1 basis point increase in the prior quarter. The CFO acknowledged the company "underestimated deposit pricing," and competition is now widening to larger regionals. Period-end deposits grew only $98 million versus $814 million in the second quarter. FHLB advances also more than doubled to $821.5 million. The margin guide has already drifted from 3.65%-3.75% in January to 3.60%-3.65% in July, and July guidance was simply reaffirmed this time. Loans grew a respectable 1.1%, led by CRE and C&I, and the pipeline held near $1 billion. However, closings are slowing as higher rates force deals to be reworked with lower coverage ratios and more equity. Management declined to frame 2027 loan growth until January.
Management's counterargument rests on asset repricing. Roughly $1 billion of fixed-rate assets reprices in the fourth quarter and about $800 million per quarter in 2027. Management said this outpaces deposit costs even with further rate hikes, and it expects a stable margin in the fourth quarter and modest improvement next year. Credit is a genuine strength:
- **Non-performing loans** fell for a third straight quarter, to $84.8 million or 0.36% of loans, from 0.60% in Q1.
- **Net charge-offs** dropped to 9 basis points from 17.
- **HarborOne workout** has roughly one more quarter to go, according to management.
Bears have legitimate ammunition here too. Criticized and classified commercial loans ticked up modestly, and fourth-quarter expenses are guided higher to roughly $163-164 million as technology and AI spending builds. Tangible book value per share slipped to $12.96 on a $110.5 million AOCI hit from the securities portfolio. The TCE ratio fell to 9.64% from 10.06%, partly due to the $89.1 million returned to shareholders.
Investor sentiment moved sharply lower heading into the report, falling from roughly neutral (0.01) to -0.37. That is a meaningful shift, consistent with mounting concern over rate pressure on deposits and loan demand. Price action has been more measured. Shares, at $22.11, are down 3.7% since the open following the July report but remain about 5.5% above the 200-day moving average of $20.95. The company repurchased 2.6 million shares in the quarter at a weighted average of $22.11, essentially the current price, and has bought another 1.6 million shares quarter-to-date. The Earnings Whispers trend readings lean modestly constructive, with AVWAP positive and price trend neutral.
The bottom line is that Eastern produced a high-quality profitability quarter, with record operating EPS, a mid-teens return on tangible equity, and credit metrics that have largely put the HarborOne cleanup behind it. The investment debate has shifted from merger execution to funding costs. Management's repricing math suggests the margin can stabilize. Still, the company has already missed its own deposit-pricing assumptions once, and loan growth is softening. That makes the January outlook, not this beat, the real test for a skeptical shareholder base.
Read our earnings preview for Eastern Bankshares, Inc.: https://www.earningswhispers.com/article/EBC/20564
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-23 | |
| Oct-22 | |
| Oct-05 | |
| Sep-17 | |
| Sep-01 | |
| Jul-30 | |
| Jul-24 | |
| Jul-23 | |
| Jul-16 | |
| Jul-02 | |
| Jun-11 | |
| Jun-05 | |
| Jun-04 | |
| May-07 | |
| Apr-25 |
