Customers Bancorp's Margin Inflection Arrives, But A Softer NII Guide And Higher Costs Temper The Beat
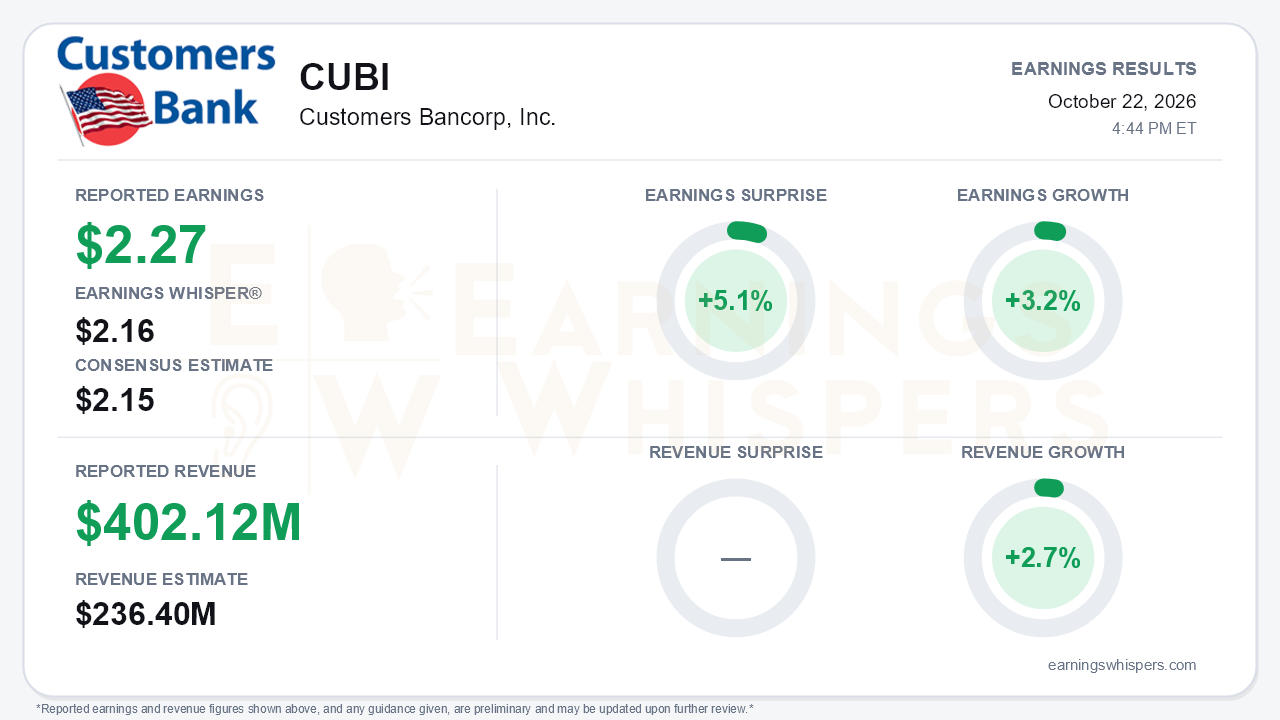
Customers Bancorp (NYSE: CUBI) delivered the inflection management had promised. Core EPS was $2.27, ahead of the $2.15 consensus and the $2.16 Earnings Whisper number, a 5.1% surprise. GAAP diluted EPS was $2.25. Year-over-year earnings growth was a modest 3.2%, but that understates the shift. Sequentially, EPS climbed from $1.97 in Q1 to $2.05 in Q2 and now to $2.27, so the bank is clearly accelerating off a mid-year trough. The year-ago quarter is a tough comparison: NIM was 3.46% and ROCE was 15.6%, and the diluted share count is about 1.3 million higher today. The central tension is that operating momentum improved meaningfully even as the full-year revenue and expense guide moved the wrong way at the margin. Investor sentiment soured into the print as a result.
The headline revenue comparison needs context. Reported revenue of $402.12 million beat the $236.4 million consensus by 70.1% and grew 2.7% year over year. That figure appears to reflect gross interest income plus fee income. The bank's own core revenue, net of interest expense, was $240.2 million, so on a like-for-like basis the top-line beat was far narrower than the percentage suggests.
The quality of the quarter rests on net interest income. NII rose $15 million, or 7.6%, to $208 million. Tax-equivalent NIM edged up to 3.19% from the 3.17% Q2 trough, and the CFO cited a September run rate near 3.25%. Q3 NIM was held back by excess cash parked while deposit inflows ran ahead of loan funding. Expenses slipped $1 million sequentially, and the efficiency ratio improved roughly 340 basis points to 47.2%. Non-interest income fell to $31 million on lower warrant gains. A favorable tax rate also helped earnings.
The balance sheet story is strong.
- **Loans:** Loans reached a record $18.5 billion, up 13.5% year over year. Corporate banking alone grew $690 million in the quarter, which offset declines in mortgage warehouse and construction.
- **Deposits:** Deposits grew $831 million to a record $22.6 billion. Non-interest-bearing balances posted a third straight record at $7.2 billion.
- **Deposit cost and beta:** Deposit cost held flat at 2.50%. Management said the early deposit beta after the September Fed hike was about 33%, versus roughly 60% in the prior hiking cycle. For a bank once criticized for expensive funding, that is a notable data point.
The call added real catalysts:
- 2026 loan growth guidance was raised to 12%+ after being anchored at 8-12% for three quarters, and the deposit floor was lifted to 9%+.
- The Pennsylvania Department of Banking consent order was lifted.
- A new Palantir partnership targets commercial deposit onboarding.
- cubiX diversified further, with mortgage finance and real estate now above 30% of balances.
- Management reiterated a low-40s efficiency ratio target by end-2027.
Bears still have legitimate ammunition.
- **NII guide:** The 2026 NII range was narrowed to $805-810 million, the lower half of the original $800-830 million range, despite Q2 commentary that the Street was a good starting point.
- **Expense guide:** Expenses are now guided to $460-465 million, above the original $440-460 million ceiling, on technology and incentive compensation. Against $340 million spent through nine months, that implies a noticeable Q4 step-up.
- **Digital asset deposits:** These fell to about $3.1 billion from roughly $3.8 billion in Q2 and $4 billion in Q1, as large banks and exchanges with direct Fed access launch competing 24/7 rails.
- **Credit:** Nonperforming loans of 0.29% are better than Q2 but up from 0.17% a year ago. Reserve coverage has fallen from 534% to 322%, and the multifamily reserve rate jumped to 1.81% from 1.12%. Management also flagged 2027 rate resets as a borrower-stress risk.
- **Capital:** CET1 eased to 12.6%. The call cited 12.8% for Q2, while the release table shows 12.9%. TCE/TA fell to 8.0%, and AOCI losses roughly doubled to $118 million, slowing tangible book value growth even as buybacks continued.
Investor sentiment moved from roughly neutral at -0.05 after the prior report to a more clearly negative -0.23. That is a meaningful but not dramatic deterioration, and it suggests skepticism about guidance and funding mix rather than the quarter itself. Price action has been steadier. Shares are up 4.1% since the open following the July report and sit about 4% above a 200-day moving average near $75.67. That leaves the stock modestly constructive rather than extended. The Earnings Whispers price trend is neutral while AVWAP reads positive, consistent with a stock that has held gains without breaking away.
The bottom line is that Customers Bancorp produced the margin turn, loan acceleration and regulatory clean-up that turnaround skeptics were not fully positioned for. The modest year-over-year growth figure reflects a demanding comparison more than weak execution. The market setup is more complicated than the beat implies, though. A bottom-half NII guide, rising expense commitments, shrinking digital asset deposits and thinner capital and reserve cushions give cautious investors reasons to wait for Q4 proof that the 3.25% margin run rate holds.
Read our earnings preview for Customers Bancorp, Inc.: https://www.earningswhispers.com/article/CUBI/20562
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-22 | |
| Oct-22 | |
| Oct-15 | |
| Oct-13 | |
| Oct-05 | |
| Sep-09 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-13 | |
| Jun-29 | |
| Jun-26 | |
| Jun-09 | |
| Jun-02 |
