Amerant Hits 1% ROA A Quarter Early And Lifts Margin Outlook, But A Shrinking Deposit Base, Lower Tangible Book And Souring Sentiment Complicate The Beat
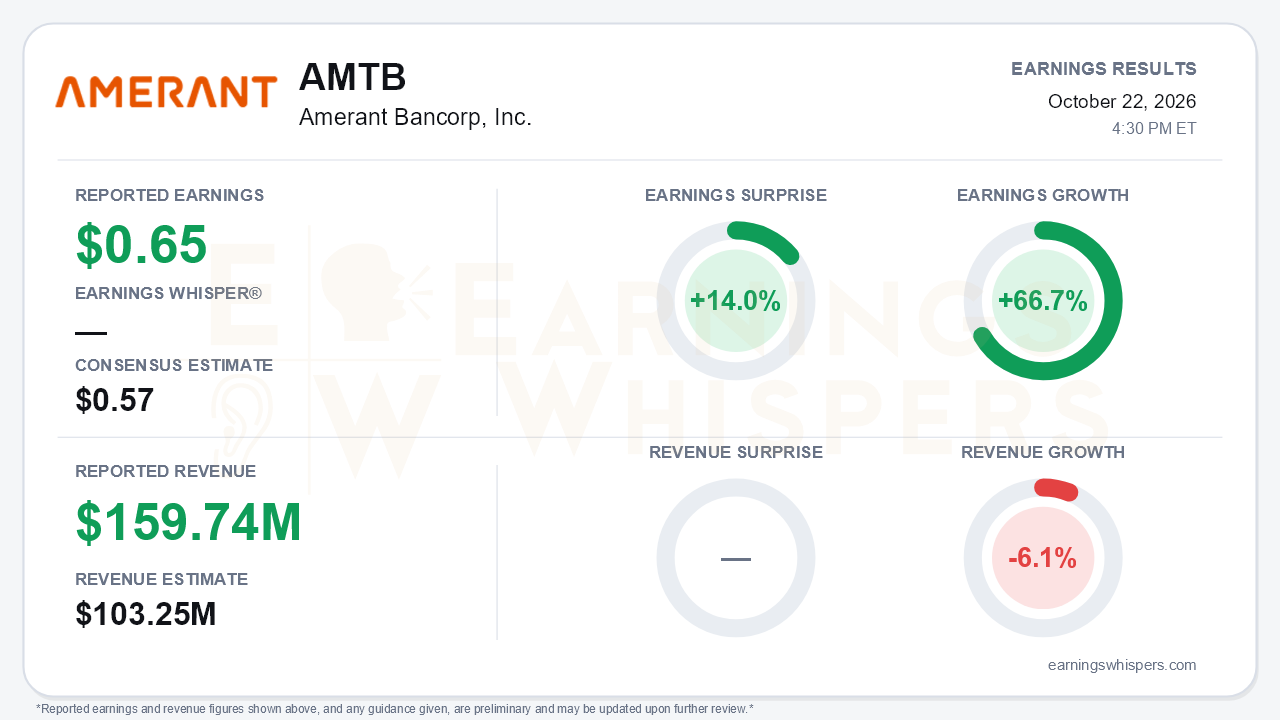
Amerant Bancorp delivered the cleanest evidence yet that its turnaround is producing earnings power. Third-quarter EPS of $0.65 beat the $0.57 consensus by 14.0% and grew 66.7% year over year. The sequential progression is just as telling: $0.07 in 4Q25, then $0.44, $0.53 and now $0.65. Return on assets reached 1.00%, a target management had set for year-end, and ROE improved to 11.29% from 9.23%. Revenue of $159.74 million beat consensus by 54.7%, but it fell 6.1% from a year ago. That points to the central tension. Earnings are accelerating, yet the balance sheet is getting smaller on the funding side, and the earnings gains are coming more from cost, credit and mix than from a larger revenue base.
The year-over-year comparison shows where the EPS growth came from. Net interest income was $90.5 million, still below the $94.2 million of a year ago. The improvement instead came from three sources:
- Provision expense fell to $6.2 million from $14.6 million.
- Noninterest expense dropped to $69.1 million from $77.8 million.
- The diluted share count shrank by roughly 2.3 million.
Sequentially, the story is stronger. NII rose 9.6%, net interest margin expanded to 3.77% from 3.52%, and pre-tax pre-provision net revenue jumped 24.6% to $39.7 million, its best level since 4Q22. The quality of the beat still deserves some scrutiny. About 6 basis points of the margin came from one-time nonaccrual interest recoveries and early-exit fees. Expenses were also flattered by:
- $1.3 million of OREO income;
- a reversal on held-for-sale loan valuations;
- a $1.9 million drop in advertising.
Noninterest income also included a $0.6 million gain on early extinguishment of FHLB advances. Underneath those items, the core drivers improved. Deposit costs fell to 2.07% from 2.21%, loan yields rose to 6.35%, and noninterest-bearing deposits climbed to $2.08 billion. Part of that last gain reflected a roughly $270 million reclassification of low-cost accounts, and management expects more of that migration.
The call kept the growth story credible. Management raised its fourth-quarter NIM guide to 3.65-3.70%, up from about 3.50% on the Q2 call, even after excluding the nonrecurring lift. It reaffirmed its roughly $7.3 billion year-end loan target after gross loans grew $207.8 million. Assets under management recovered with $76.5 million of net new assets following the second-quarter trust departure. Non-Venezuela international deposits rose 12%, led by Argentina and Central America. The tone shifted from stabilization toward sustainable growth, and management framed 1% ROA as a new baseline rather than a peak.
Bears have legitimate ammunition, though, and most of it sits on the funding and capital side:
- **Deposits.** Total deposits fell $109.6 million. Venezuelan deposits dropped $96.8 million after a roughly $500 million Q2 inflow that management called transactional. The fourth-quarter deposit guide was cut sharply to about $8.5 billion from about $9.1 billion as large domestic commercial fund providers exited. With loans growing and deposits shrinking, the loan-to-deposit ratio rose to 85.78% from 82.17%.
- **Tangible book value.** The rate backdrop, including a Fed hike and market yields up more than 100 basis points, pushed accumulated other comprehensive loss to $118.9 million from $23.7 million. Tangible book value per share fell to $20.94 from $22.78, and the TCE ratio slipped to 8.04%.
- **Credit.** The picture is mixed. Non-performing loans fell 12.6% and classified loans fell 22%. However, special mention loans rose 10% on downgrades, specific reserves increased $12.6 million on four commercial relationships, and the Q4 gross charge-off guide moved up to 30-35 basis points from 25-30 basis points.
- **Expenses.** The Q4 expense guide of about $68 million sits above the prior $66-67 million. Management also pointed to an early-2027 run rate of $69.5-70 million as it hires for growth.
Capital actions add a new layer. Management added a $50 million buyback authorization through 2027 and issued $50 million of 7% senior notes. The notes strengthen holding-company liquidity, but at a meaningful coupon. Q3 repurchases were modest at about 1.36x tangible book.
The market setup is more complicated than the surprise implies. Shares have gained 11.5% since the open after the July report, to $29.66, and sit about 19.5% above the 200-day moving average. The stock has clearly been rewarding the profitability recovery, and the Earnings Whispers AVWAP reading remains positive. Investor sentiment moved the other way, falling from a mildly positive 0.21 to -0.56. That is a substantial swing, and it suggests the deposit cut, tangible book erosion and credit migration are weighing on expectations more heavily than the margin beat.
The bottom line is that Amerant's earnings inflection is real and broadening. The margin outlook was raised, returns hit target early, and problem assets are still shrinking. But the quarter also showed a funding base that is less stable than hoped, tangible book exposed to rising rates, and early signs of new credit stress. Whether shrinking deposits and the expected expense step-up can coexist with the guided margin will determine whether 1% ROA proves to be a baseline or a high-water mark.
Read our earnings preview for Amerant Bancorp, Inc.: https://www.earningswhispers.com/article/AMTB/20553
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Sep-30 | |
| Sep-17 | |
| Sep-15 | |
| Sep-14 | |
| Aug-11 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-06 | |
| Jun-26 | |
| May-19 | |
| Apr-25 |
