Ameris Bancorp Posts Five-Year-High EPS, But Slower Loan Growth And Rising Criticized Loans Weigh On The Outlook
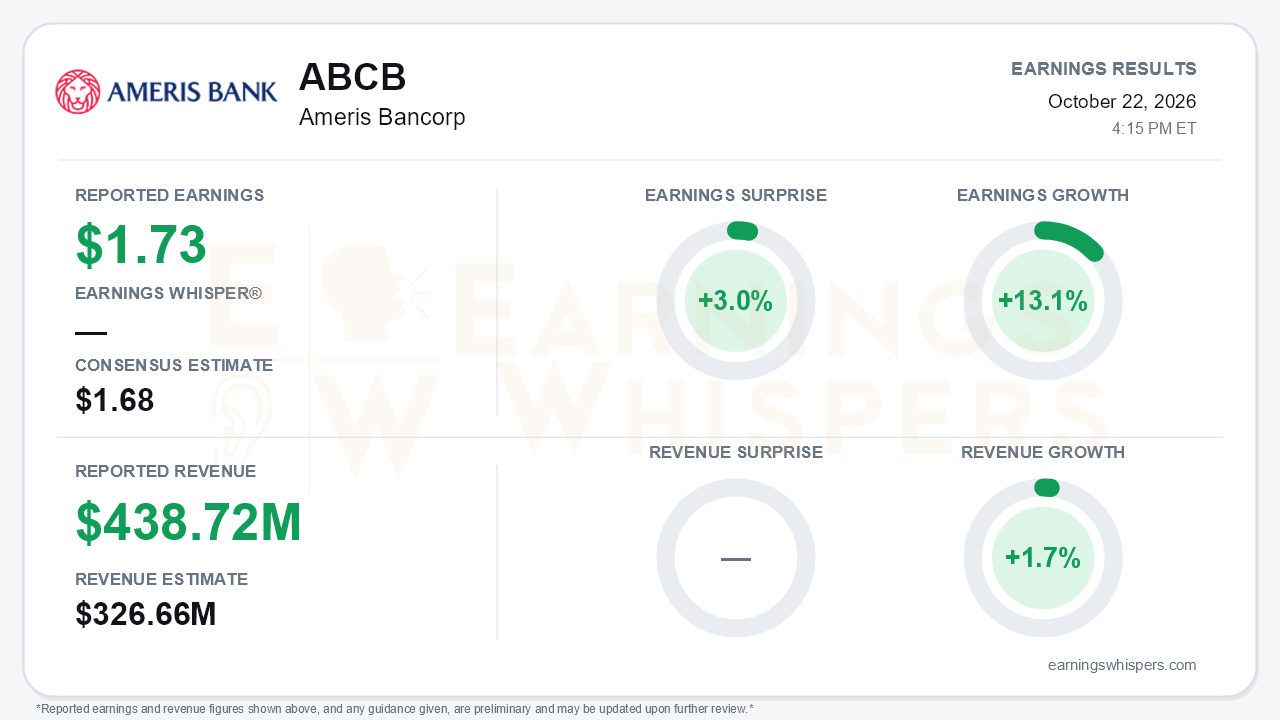
Ameris Bancorp (NYSE: ABCB) earned $1.73 per diluted share in the third quarter. That beat the $1.68 consensus by 3.0% and was 13.1% above the year-ago quarter. GAAP and adjusted EPS were the same this quarter. The result is a clear step up from adjusted EPS of $1.60 in Q2 and $1.63 in Q1, so per-share earnings power accelerated. GAAP net income also recovered sharply from Q2's $0.77, which had been depressed by an $82.5 million litigation accrual.
The central tension is that the earnings line improved while the balance sheet engine slowed and credit indicators drifted the wrong way. Investors have noticed, even if the headline beat does not show it.
The quality of the beat deserves scrutiny. Core drivers were solid:
- Tax-equivalent net interest income rose 2.0% sequentially and 8.2% year over year to $258.6 million.
- Adjusted noninterest expense fell $2.5 million.
- The adjusted efficiency ratio improved to 49.15% from 50.42%.
However, a lighter provision also helped. Credit-loss provisions fell to $12.6 million from $17.3 million, even as criticized assets climbed:
- Special-mention loans rose to $97.1 million from $61.0 million.
- Substandard loans rose to $197.7 million from $174.3 million.
- Nonaccrual portfolio loans increased to $102.4 million from $86.8 million.
- Nonperforming assets excluding GNMA-guaranteed loans rose to 0.40% of assets from 0.35%.
Net charge-offs held at a benign 19 basis points, and management reaffirmed its 20-25 basis point range. Still, its own description of credit as having "normalized some" gives bears legitimate ammunition.
The reported revenue figure also needs context. The normalized $438.72 million reflects gross interest income plus fees. That explains the outsized 34.3% surprise against a $326.66 million consensus. On a net basis, the company's own total revenue was $321.8 million, slightly below Q2. The revenue beat is a definitional artifact, not evidence of a top-line blowout, and the modest 1.7% year-over-year growth is the more telling figure.
The call showed growth losing momentum:
- Loan growth halved to $173.1 million, about 3% annualized versus roughly 6% in prior quarters, because commercial real estate payoffs stayed elevated.
- Average earning-asset growth decelerated to 4.5% annualized from 8.5% in Q2 and 9.7% in Q1.
- Net interest margin slipped a basis point to 3.87%. Interest-bearing deposit costs rose six basis points.
Deposit growth of $319.4 million reversed Q2's decline, but its mix was less flattering. It came from money market accounts and $129.5 million of brokered CDs, while noninterest-bearing balances fell $87.8 million. Despite the September Fed hike, and despite management describing the bank as slightly asset sensitive (about 1 basis point of margin per 25 basis point hike), management flagged possible margin compression over the next few quarters. It cited deposit competition and potential migration out of noninterest-bearing accounts. It also noted aggressive loan pricing by competitors.
Mortgage remains a drag. Production fell 13.7%, the open pipeline shrank to $439.9 million from $609.3 million, and the retail mortgage segment earned $6.2 million versus $18.7 million a year ago. Management expects mortgage to be flat to down in 2027. The offsets came from specialty lending:
- Premium finance loans grew to $1.70 billion from $1.53 billion, and segment profit rose to $8.6 million.
- Warehouse lending and equipment finance both improved.
On the forward-looking side, management:
- Guided to a full-year efficiency ratio of about 50%, versus "slightly above 50%" previously.
- Set a 2027 core expense range of $165-169 million per quarter, which management framed as below consensus assumptions.
- Said the commercial loan pipeline ended the quarter higher than Q2, with production steady at about $2.3 billion.
- Received board approval for a replenished $200 million buyback.
That buyback comes with a caveat: Ameris repurchased no shares in Q3, after buying $75 million in Q1 and $19 million in Q2. The CEO also signaled caution on new projects heading into Q4 and Q1. That suggests a more defensive posture than the record EPS implies.
The market had already been leaning skeptical. Earnings Whispers investor sentiment deteriorated meaningfully, falling from -0.27 to -0.54. Shares traded at $82.37, down 5.4% from the $87.04 open after the July report. They sit about 1.5% below the 200-day moving average of $83.59, having slid from a quarterly intraday high of $93.22 to a $79.52 quarter-end close. The price and AVWAP trend readings remain negative, consistent with a stock that has been distributing despite rising earnings.
The bottom line is that Ameris delivered a cleaner, more profitable quarter, with five-year-high EPS, sub-50% efficiency, and growing tangible book value of $45.65. But the drivers behind that profitability are softening. Loan growth halved, margin is guided toward possible compression, mortgage is shrinking, and criticized loans rose even as provisions fell. Expense discipline and capital return give the bull case real support. Sustaining this earnings level will depend on whether loan growth reaccelerates and credit normalization stays contained, the two questions now driving the stock.
Read our earnings preview for Ameris Bancorp: https://www.earningswhispers.com/article/ABCB/20552
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-01 | |
| Sep-15 | |
| Aug-04 | |
| Jul-31 | |
| Jul-27 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-13 | |
| Jul-02 | |
| Jun-25 | |
| Jun-23 |
