Alpine Income Property Trust Beats And Raises Again, But Loan-Driven Growth, Rising Leverage, And A Flat Run Rate Cloud 2027
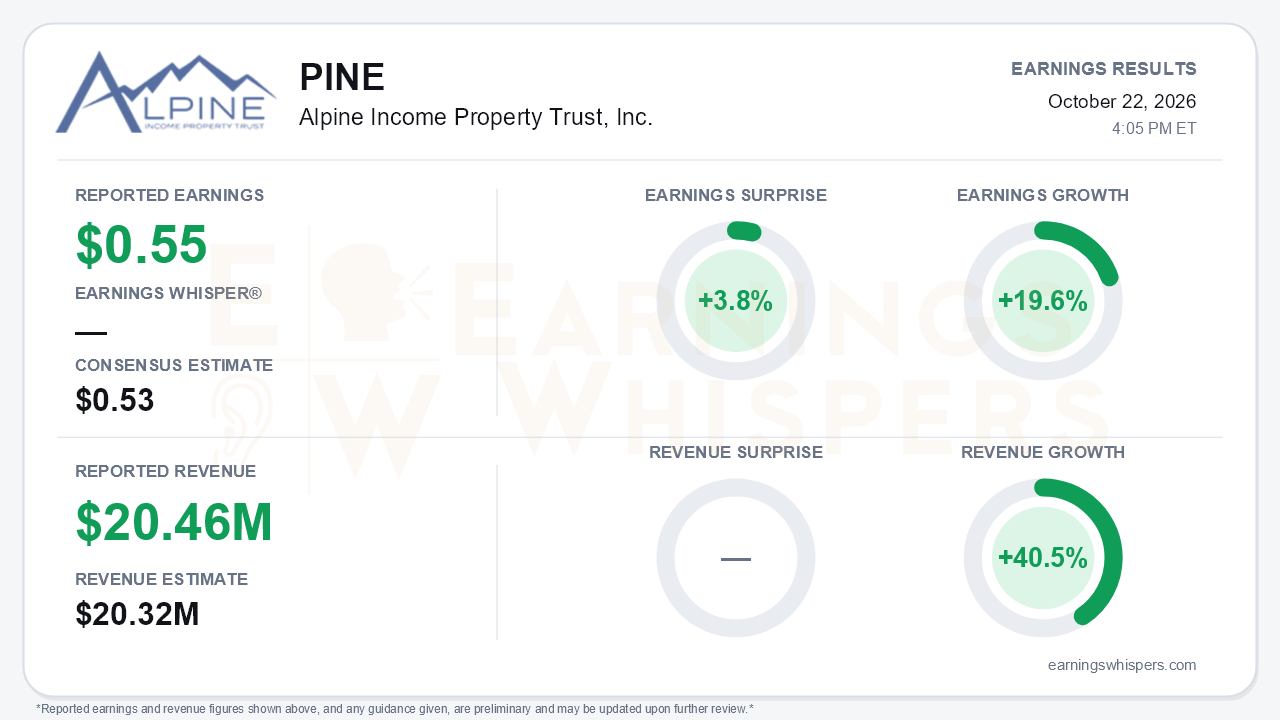
Alpine Income Property Trust (NYSE: PINE) delivered another beat-and-raise quarter. AFFO of $0.55 per share topped the $0.53 consensus by 3.8% and rose 19.6% year over year. Revenue of $20.46 million beat estimates by 0.7% and jumped 40.5%. Management lifted full-year AFFO guidance to $2.20-$2.22 from $2.12-$2.15, the second straight full-range raise. It also nearly doubled its investment volume target to $310-$350 million from $170-$200 million. The headline is clean, but the trajectory beneath it is less so. Earnings growth is decelerating, the sequential run rate has stalled, and the 2027 setup carries financing headwinds that the 2026 raise does not capture. That is the central tension.
The quality of the beat deserves scrutiny. Nearly all of the revenue growth came from the commercial loan book rather than the net lease portfolio. Interest income from commercial loans and investments rose to $7.6 million from $2.3 million a year ago. Lease income grew only about 6%, to $12.8 million from $12.1 million. About $900,000 of third-quarter income was paid-in-kind interest that was earned but not received in cash, and the AFFO reconciliation does not strip it out. That is close to a tenth of AFFO attributable to common stockholders. The GAAP picture did improve meaningfully. PINE swung to net income of $0.18 per diluted share from a loss of $0.09, helped by a small CECL reserve release versus a $1.9 million impairment charge a year earlier.
The call made the deceleration explicit. Third-quarter AFFO of $0.55 trailed the second quarter's $0.58, although roughly $0.02 of that earlier figure was nonrecurring. Year-over-year growth slowed to 19.6% from 32% in the prior quarter. The raised guidance implies a fourth quarter roughly flat at about $0.55. Several forces are offsetting the pending acquisition:
- $17.9 million of early loan repayments in the third quarter;
- another $7.4 million loan maturing in the fourth quarter;
- a rate step-down on the large residential loan.
The loan book shrank to $160.1 million across 11 loans from $167 million across 13 loans. Weighted average lease term also slipped to 8.7 years from 9.2. On the property side, the operating metrics remain healthy. Annualized base rent climbed to $53.9 million from $50 million last quarter and $46.2 million at year-end, occupancy edged up to 99.6%, and third-quarter acquisitions priced at an 8.5% cap rate versus 7.4% in the second quarter.
The forward story now rests on the pending $117.3 million, 13-property industrial portfolio. It is 100% leased under absolute triple-net leases with a 10.2-year weighted average term and no expirations before late 2031. The deal lengthens lease duration and adds rent escalators. However, management framed it as opportunistic, and it moves PINE into a sector outside its retail-focused core. Funding comes from $175 million of new bank commitments: a $100 million term loan plus a $75 million revolver upsize. Those commitments matter because quarter-end liquidity was only $63 million. Bears have legitimate ammunition here:
- Leverage is expected to rise to roughly 7.3x net debt to EBITDA pro forma, from 6.5x, reversing much of last year's deleveraging from 7.7x.
- In January 2027, swaps on $100 million roll up about 150 basis points and $50 million becomes unhedged.
- The CEO signaled lower investment volume next year after deploying roughly the company's market cap in 2026.
Investors are not rewarding the raise. Sentiment was already negative and weakened modestly, to -0.30 from -0.23. Shares have fallen 17.6% since opening at $21.13 after the July report. At $17.42, the stock sits 8.7% below its 200-day moving average of $19.09. The Earnings Whispers price and AVWAP trend readings are both negative, consistent with that sustained selling. The decline also has a direct operating consequence. PINE issued common stock through its at-the-market program at about $20 per share during the quarter, so the current price makes equity a costlier funding source just as leverage climbs. The dividend appears well covered, with a 58.2% AFFO payout ratio on the raised $0.32 quarterly rate.
The bottom line is that PINE executed well in 2026. It posted a record investment year, wider acquisition yields, a cleaner GAAP result, and guidance that keeps moving higher. The market is looking past that to a business whose growth has leaned on high-coupon, partly non-cash loan income that is now running off. Its run rate has flattened at about $0.55, and 2027 brings higher leverage, swap resets, and slower deployment. Until management shows the industrial deal and property acquisitions can offset loan runoff and rising interest costs, the raised outlook is unlikely to settle the debate.
Read our earnings preview for Alpine Income Property Trust, Inc.: https://www.earningswhispers.com/article/PINE/20580
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-12 | |
| Oct-09 | |
| Sep-24 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jun-24 | |
| May-27 | |
| Apr-25 | |
| Apr-23 | |
| Apr-23 | |
| Mar-26 |
