World Acceptance Crushes EPS Consensus On Credit And Cost Discipline, But Slowing Growth Is The Real Story
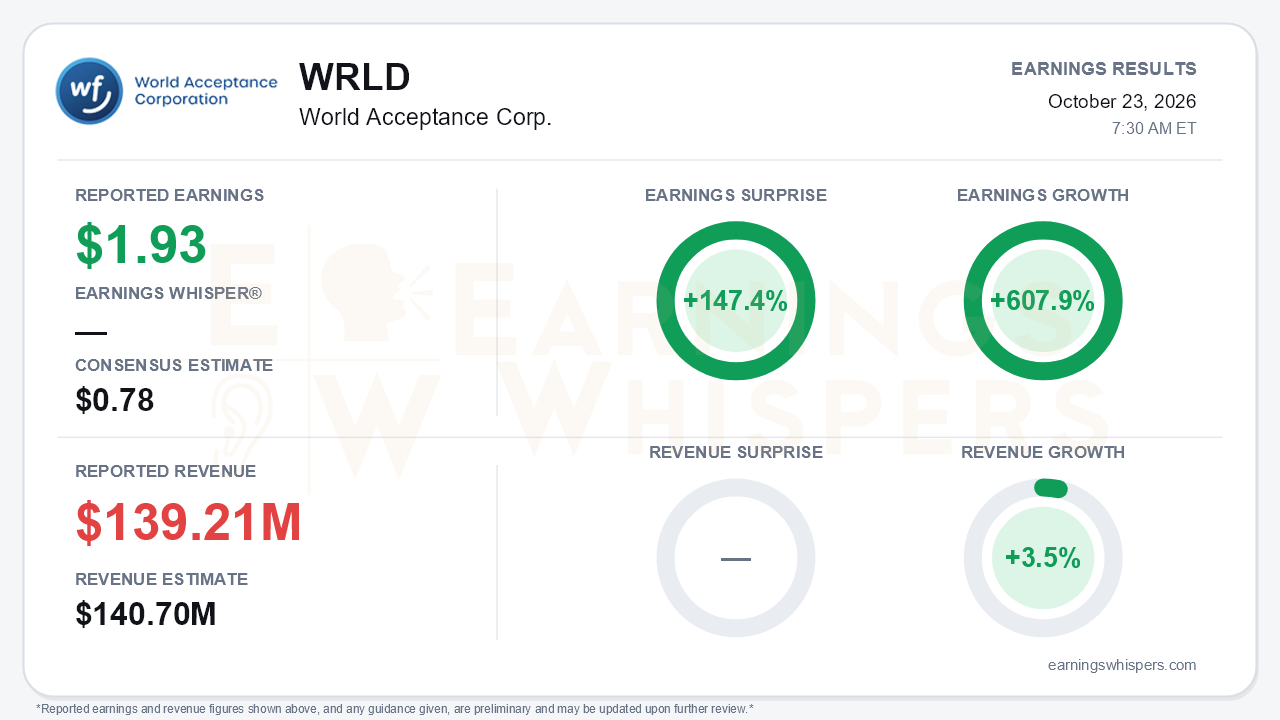
World Acceptance Corp. (NASDAQ: WRLD) delivered an earnings result that bore little resemblance to expectations. Fiscal second-quarter EPS of $1.93 topped the $0.78 consensus by 147.4% and rose 607.9% from a year ago, when the company posted a GAAP net loss of $0.33 per share. Revenue was a different matter. Sales of $139.21 million rose 3.5% but missed the $140.7 million consensus by 1.1%. Earnings Whispers' normalized figures differ slightly from the company's reported $1.92 in GAAP diluted EPS and 3.2% revenue growth. That is the central tension: WRLD is converting a nearly flat loan book into sharply higher profits, while the growth engine management promoted just two quarters ago has stalled.
The quality of the beat deserves scrutiny, because much of it came from below the revenue line. Provision expense fell $3.8 million, or 7.7%, to $46.0 million, mainly because a smaller-growing book required less allowance build. General and administrative expense declined 2.9%, largely from a $4.2 million drop in incentive pay tied to lower share-based compensation. Interest expense fell 18.8%, but only because the prior-year quarter carried $3.7 million in early-call penalties and debt-cost write-offs. Average debt actually rose 13.3% to $582.8 million, and debt-to-equity rose to 1.7:1. Diluted shares fell roughly 10% after aggressive buybacks, adding further lift to per-share results. Operating income as a share of revenue still jumped to 16.8% from 9.7%. The margin improvement is real, but a meaningful portion is non-recurring or financial-engineering driven rather than the product of demand.
Credit is the cleaner positive. Front-end delinquency (0-60 days) improved to 18.9% from 20.0%, and 61-plus-day delinquency eased to 5.4% from 5.8%. This extends the improvement seen in the first quarter. However, the quarter's annualized net charge-off rate actually rose to 17.6% from 17.1%, even though the six-month rate improved to 17.9% from 18.3%. Credit is better, not fixed. Management conceded that elevated gas prices are still squeezing its core borrower and said credit might have improved more without them.
The operating trends show a company that deliberately traded growth for quality. After tightening new-customer underwriting at the end of the prior fiscal year, new-customer originations fell 18.1% and former-customer volume fell 9.9%. Only refinancing of existing customers grew, up 4.4%. The customer base shrank 5.4% over twelve months, versus 6.2% growth a year earlier. Same-store gross loans inched up just 0.1%. Revenue gains came mainly from a 158-basis-point yield increase as the mix shifted toward smaller, higher-yielding loans, a lever with natural limits. The forward message also softened. Last spring management targeted mid-single-digit-or-higher loan growth and roughly 5.4% growth in interest, fee and insurance revenue. Now it expects no dramatic change in the growth trajectory near term.
There are catalysts. Underwriting has been modestly loosened versus the March quarter, and advertising rose 36.7% to fund new-customer acquisition, so the company is at least priming the funnel. A credit card pilot remains in testing, with a scale decision expected in one to two quarters. Leadership has also stabilized, with John Calmes formalized as President and CEO after an interim period. On capital returns, the release disclosed $25.0 million in second-quarter buybacks, or 3.0% of shares, though the call offered little forward commentary. Only about $25.0 million of authorization remains, plus $47.5 million of credit-facility capacity subject to board approval. Bears have legitimate ammunition here: rising leverage and dwindling authorization make another year of double-digit share shrinkage unlikely.
The market had already cooled on the story heading into the print. Shares closed at $169.66, down 9.1% from the $186.59 open after the July report. They sit 22.0% below the $217.63 inter-earnings high set on that same report day, so the post-report spike has been fully unwound. The stock entered this release just 3.1% above its quarterly low of $164.50 and 4.3% above its 200-day moving average of $162.69. Investor sentiment was solidly positive at 0.48, and expectations do not appear to have collapsed. The internal trend readings are mixed, with sequential growth positive while AVWAP remains negative.
The bottom line is that WRLD's quarter showcased disciplined credit, tighter costs and a big EPS beat. Those gains came alongside a revenue miss, a shrinking customer base and a walk-back of near-term growth ambitions. Easy comparisons and buybacks flattered the earnings line. The next leg of the story depends on whether loosened underwriting can rebuild new-customer volume without reversing the credit gains, a test management itself is not promising to pass quickly.
Read our earnings preview for World Acceptance Corp.: https://www.earningswhispers.com/article/WRLD/20623
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-16 | |
| Sep-21 | |
| Jul-24 | |
| Jul-24 | |
| Jul-24 | |
| Jul-24 | |
| Jul-17 | |
| Apr-30 | |
| Apr-30 | |
| Apr-23 | |
| Apr-13 | |
| Feb-17 |
