Primis Misses On EPS As Mortgage Slump Overshadows Its Strongest Core Margin Yet
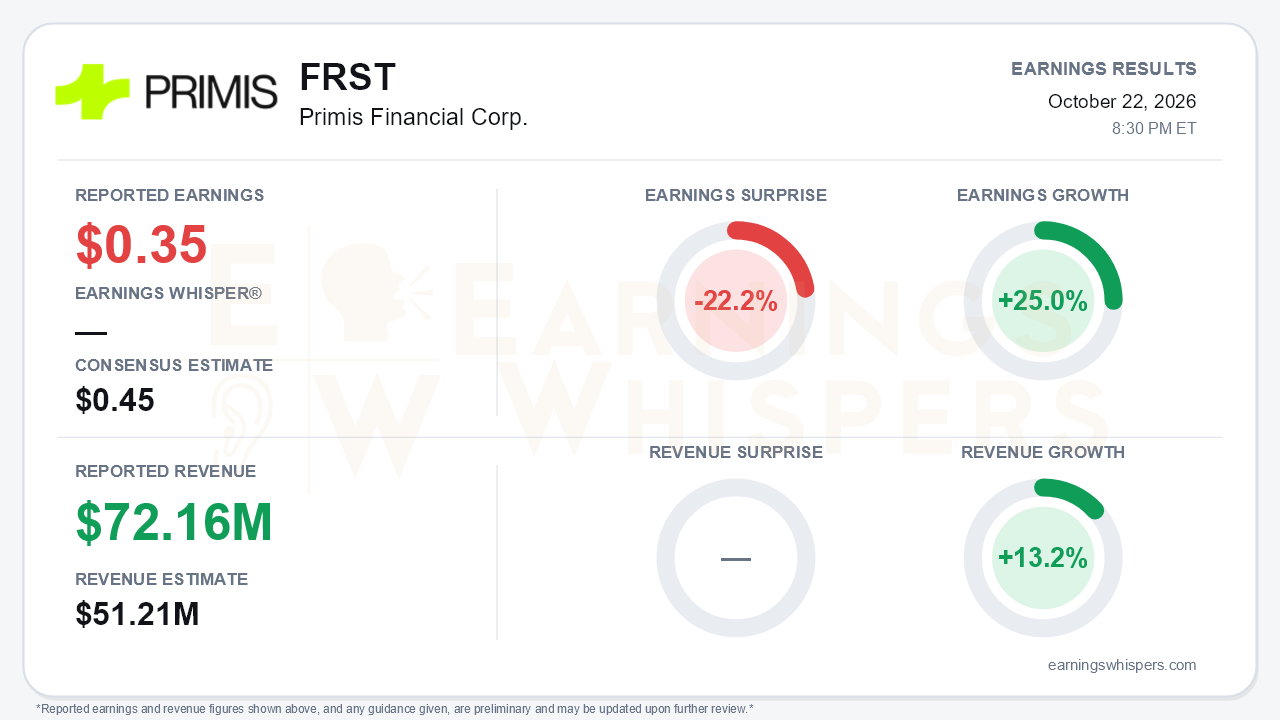
Primis Financial Corp. (NASDAQ: FRST) reported third-quarter earnings of $0.35 per share, 22.2% below the $0.45 consensus, even as earnings grew 25.0% from a year ago. Revenue of $72.16 million beat the $51.21 million consensus by 40.9% and rose 13.2% year over year. That revenue beat should be read cautiously. The reported figure tracks total interest and noninterest income, which is a broader measure than the net revenue a bank keeps after funding costs. The central tension is clear: the core bank had its best margin quarter in years, but a rate-driven collapse in mortgage activity left management short of its 1% ROAA target. That target had been reiterated on every prior call.
On an operating basis, the trajectory improved. Operating EPS of $0.35 compared with $0.23 in the second quarter and $0.28 a year earlier. Pre-tax pre-provision operating earnings rose to $12.0 million from $8.7 million. Net interest income climbed to $36.3 million from $33.8 million sequentially and $29.0 million a year ago. Reported NIM reached 3.66%, up from 3.45% in Q2 and 3.18% a year earlier.
The quality of the quarter deserves some scrutiny. Roughly $0.7 million of interest recoveries on a previously charged-off loan lifted NIM by about 7 basis points, putting core NIM at 3.59%. Another $0.9 million of loan recoveries and a $0.4 million BOLI payout flowed through noninterest income. A sharply lower provision also helped, falling to $1.1 million from $5.5 million in Q2. Still, even the 3.59% core margin cleared management's prior 3.45-3.50% guide by a wide margin. GAAP and operating results were identical this quarter, so the miss reflects operating shortfalls rather than accounting noise.
Mortgage is where the quarter broke down. Mortgage rates rose from 6.43% to 7.28%, which cut the retail pipeline by 37%. Mortgage banking income fell to $8.0 million from $11.4 million in Q2, and that figure includes a $2.5 million pipeline value reset. Primis Mortgage swung to a small pre-tax loss. The release puts it at about $0.3 million and the call cited roughly $200,000, versus $1.9 million of profit a year ago. Management cut its annualized volume outlook to about $1.1 billion from $1.6-1.8 billion and lowered the division's expected ROA contribution to about 10 basis points. CEO Dennis Zember argued the bank would have hit 1% ROAA in a steady mortgage environment. That claim is plausible, but it remains a counterfactual.
Balance-sheet growth is also cooling. Loans held for investment were essentially flat sequentially at $3.5 billion. Full-year loan growth guidance slipped to roughly 8-8.5%, and management expects core bank loans to be flat in Q4 because of a large payoff, with warehouse balances likely to sag. Deposits grew only 4% year over year, with full-year guidance of 3-5%. The loan-to-deposit ratio sits near 101%, and FHLB advances of $220 million remain well above the $85 million of a year ago. Management also flagged intense loan pricing competition and tighter Panacea spreads.
On the positive side, the call raised the margin outlook to further incremental expansion from loan repricing over the next two to three quarters. That replaces the earlier stance of flat plus or minus a basis point or two. Management also identified $4 million of annualized mortgage fixed-cost cuts and about $3 million of vendor savings starting in early 2027. It promised a strong Q4 deposit quarter without brokered funding. Credit trends were constructive overall:
- NPAs excluding SBA guarantees fell to 1.43% from 2.35% in Q1.
- Substandard loans dropped to $84 million from $139 million a year earlier.
- Tangible book value rose 18% to $13.81.
Bears do have ammunition here. Special mention loans of $75.7 million are far above the $7.0 million of a year ago, and pass/watch balances roughly doubled sequentially.
Investor sentiment improved meaningfully heading into the report, rising from -0.24 to essentially neutral. Expectations have thawed but have not turned bullish. Shares at $15.94 are up 3.9% since the opening after the July report. They trade 7.9% above the 200-day moving average and 5.5% below the 52-week high of $16.88 set in August. The internal trend readings are mixed, with momentum positive while AVWAP remains negative. That fits a stock that has rallied but has not held its highs.
The bottom line is that Primis delivered a cleaner, more profitable core bank than a year ago, backed by a margin outlook that was actually raised. However, the EPS miss, the reduced mortgage and loan-growth outlooks, and thin deposit growth push the 1% ROAA goal further out. The investment case now rests on whether margin expansion and cost cuts can carry earnings while mortgage stays depressed.
Read our earnings preview for Primis Financial Corp.: https://www.earningswhispers.com/article/FRST/20568
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-14 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-10 | |
| Jun-30 | |
| May-27 | |
| May-01 | |
| Apr-25 | |
| Apr-23 | |
| Apr-23 | |
| Apr-07 |
