SLB Matches The Whisper As Middle East Rebound Lifts Q3, But A Trimmed Q4 Outlook Tests The 2027 Upcycle Story
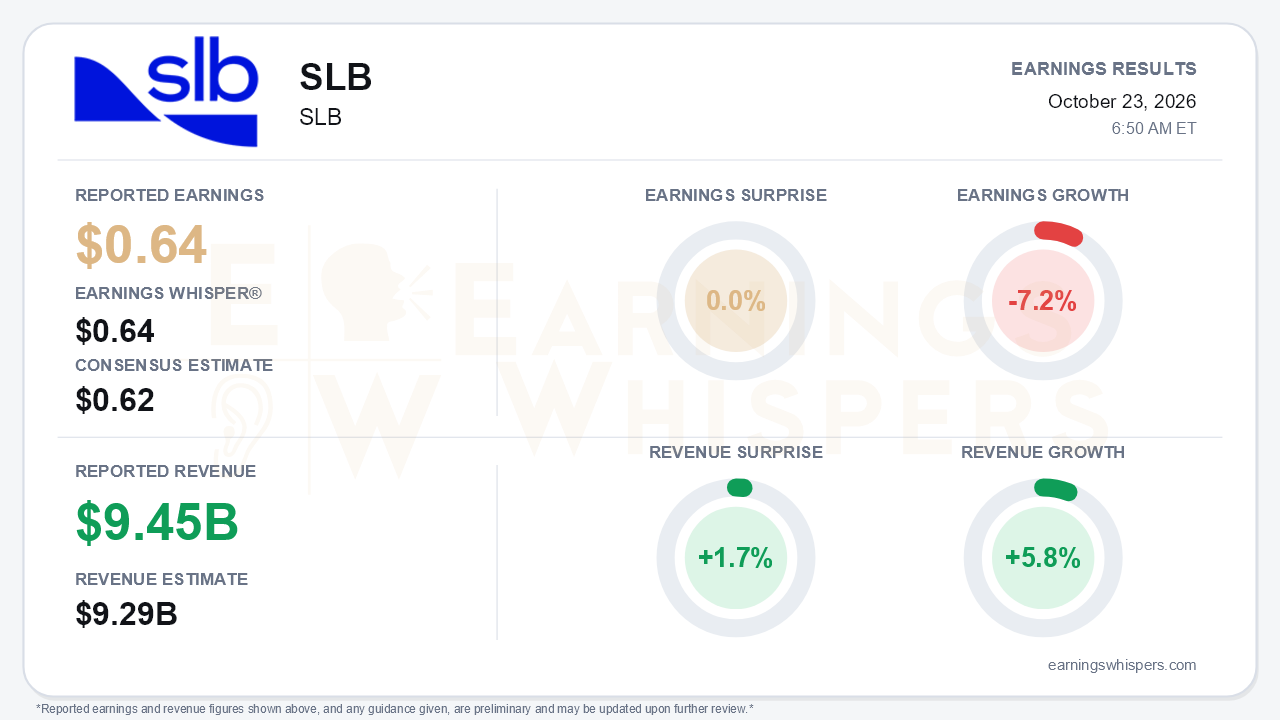
SLB delivered third-quarter earnings of $0.64 per share excluding charges, exactly matching the Earnings Whisper number and two cents above the $0.62 consensus. Revenue of $9.449 billion topped the $9.29 billion consensus by 1.7% and grew 5.8% year over year, yet earnings fell 7.2% from a year ago. That gap is the central tension. Sequentially the quarter was a clear improvement: adjusted EPS climbed 16% from $0.55, revenue rose 5% against the 3-4% management had guided on the July call, and margins expanded across every Core division. On a year-over-year basis, however, SLB is still producing less profit from more revenue, and the forward outlook was trimmed even as management's rhetoric about 2027 became more emphatic.
The quality of the top line deserves scrutiny. ChampionX contributed $956 million in the quarter versus $579 million a year earlier. Excluding that acquisition, total revenue rose only 2%, international revenue was flat, and Core revenue was essentially unchanged. Pretax segment operating margin of 16.7% improved 104 basis points sequentially but remains 153 basis points below last year's 18.2%, and adjusted EBITDA of $2.07 billion was flat year over year despite the acquired revenue. The drag is concentrated in the Middle East, where revenue rebounded 13% sequentially to about $1.9 billion but is still 12% below a year ago, pulling Well Construction and Reservoir Performance margins down more than 220 basis points each year over year. On a GAAP basis, EPS fell to $0.49, weighed down by a $187 million non-cash pension settlement charge worth $0.12 per share.
Beneath the headline, the growth engines are increasingly outside the traditional Middle East franchise. North America revenue rose 13% year over year on a pro forma basis, driven by U.S. land production chemicals and artificial lift, and ChampionX posted its highest revenue since the acquisition along with a fourth consecutive quarter of margin expansion. Latin America grew 16% pro forma on offshore activity in Brazil, Guyana and Mexico. Data Center Solutions revenue reached $230 million, up 23% sequentially and 76% year over year, and management reaffirmed targets of a $1 billion run rate exiting 2026 and more than $2 billion exiting 2027. Digital was raised to double-digit growth for 2026 with EBITDA margins above 35%, versus January's guide of roughly 9%, although the sequential dip in Digital revenue and flat ARR of $1.04 billion show that progress there is uneven.
The call preserved a credible growth story for 2027. Management moved from saying the market was starting to show upcycle characteristics to stating that the cycle has started, and it offered a first 2027 view of mid-single-digit oilfield services market growth even with a flat Middle East, with SLB's Core expected to outperform. Concrete support came from four Aramco integrated well construction contracts covering more than 450 wells, the Rovuma LNG subsea award, an expectation that subsea bookings will exceed the $9 billion two-year target, and Venezuela revenue on track to more than double this year. The near term is softer. Renewed Middle East disruptions late in the quarter led management to assume Q4 regional revenue flat at about $1.9 billion, down from the $2.1-2.2 billion assumed in July. Fourth-quarter revenue is now guided to roughly $10 billion rather than to surpass it, and EBITDA margin expansion of 100-150 basis points implies roughly 23-23.4%, short of the approximately 24% previously signaled. Well Construction and Reservoir Performance are guided essentially flat, and management acknowledged ongoing pricing pressure in large tenders along with cost inflation.
The balance sheet is also carrying more of the strategy. Net debt rose to $9.25 billion from $7.4 billion at year-end, as buybacks of $1.76 billion year to date outpaced free cash flow of $1.52 billion, and the roughly $3.4 billion Kelvion purchase is still to come. Third-quarter free cash flow of $828 million was a solid improvement, but the expected Q4 step-up depends partly on the timing of collections in certain countries.
The market had already been skeptical. Shares entered the report at $49.55, about 1% below the opening price after the July report and 3.2% under their 200-day moving average. They have given back much of the run to a 52-week high of $60.46 on August 31 and sit only 5% above the October 15 low of $47.17. Investor sentiment was essentially unchanged and slightly negative. The Earnings Whispers trend signals are mixed, with sequential growth and momentum readings positive while AVWAP remains negative.
The bottom line is that SLB delivered a quarter that met elevated expectations and showed genuine sequential recovery, but organic growth remains thin, year-over-year margins are still compressed, and the Q4 guide was cut on renewed Middle East uncertainty. Bulls can point to a broadening 2027 pipeline and a fast-growing data center business; bears have legitimate ammunition in the guidance reset and rising leverage. The investment case now rests on whether the 2027 upcycle arrives on schedule.
Read our earnings preview for SLB: https://www.earningswhispers.com/article/SLB/20613
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 43 min | |
| 1 hour | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours | |
| 8 hours | |
| Oct-08 | |
| Oct-07 | |
| Sep-29 | |
| Sep-29 | |
| Sep-28 | |
| Sep-24 | |
| Sep-23 |
