Byline Bancorp Beats On Margin Strength And A Lower Tax Rate, But Flat Loans, Rising NPLs And A Higher Expense Guide Temper The Record Quarter
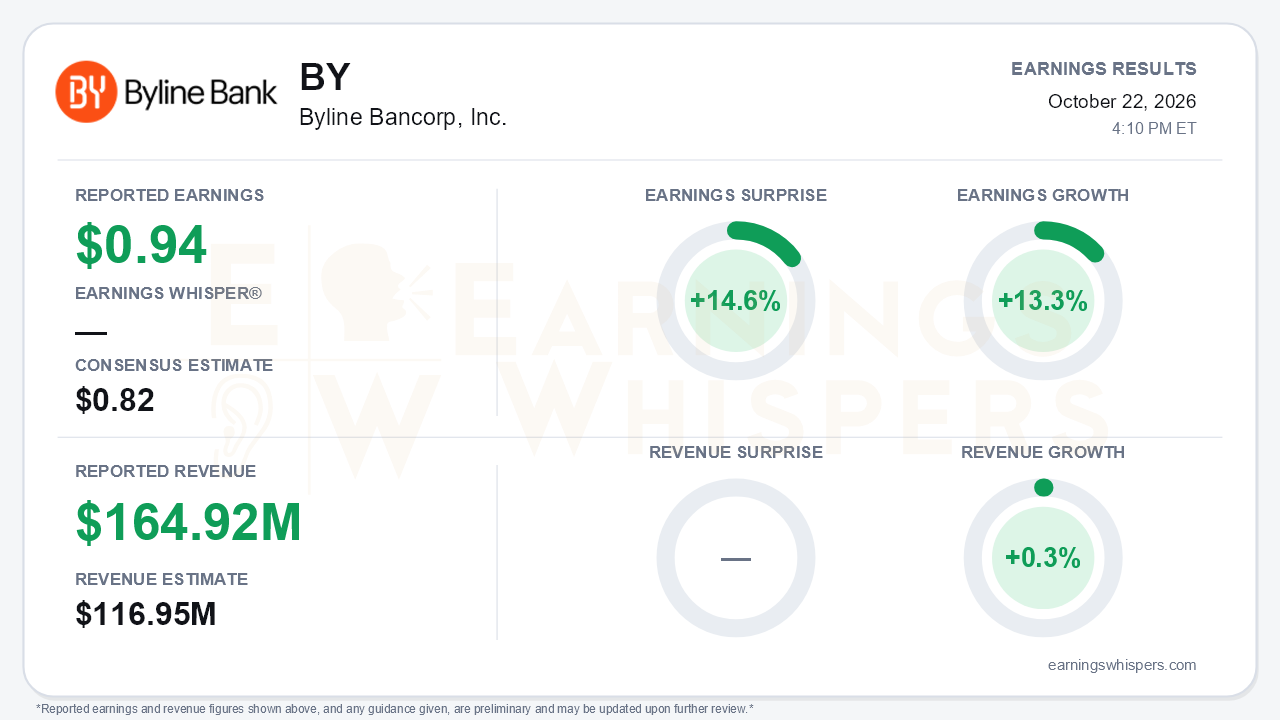
Byline Bancorp delivered a clean headline beat in the third quarter. Earnings of $0.94 per share topped the $0.82 consensus by 14.6% and grew 13.3% year over year. That marks a third straight quarter of sequential improvement, from $0.83 in Q1 to $0.90 in Q2 to $0.94 now. The beat is real, but the engine behind it is narrower than the record labels suggest. Net interest margin and capital return did the heavy lifting. Loan growth, credit trends and the expense outlook moved the other way. That is the central tension: Byline is earning more on a balance sheet that is not growing, while some credit indicators deteriorate underneath.
The revenue figures need context. The supplied revenue of $164.92 million, up 0.3% year over year, appears to combine gross interest income and non-interest income. The 41.0% beat against a $116.95 million consensus likely reflects a basis mismatch rather than a genuine blowout. Byline's own measure, net interest income plus fee income, was a record $121.0 million, up 2.8% sequentially and 4.6% year over year. That is solid but unspectacular.
The quality of the EPS beat also deserves scrutiny. Pre-tax, pre-provision income was essentially flat at $61.2 million versus Q2, and pre-tax income rose only about $0.4 million. The sequential EPS gain came largely from three sources:
- a lower effective tax rate of 23.3%, versus 25.7%, helped by purchased renewable energy tax credits;
- a slightly smaller provision;
- a shrinking share count after roughly $20 million of buybacks.
The margin story is the strongest part of the quarter. NIM expanded five basis points to 4.33%, and the improvement was better than it looks. Purchase accounting accretion contributed only six basis points, down from 11, so the core margin rose roughly 10 basis points. That gain came from higher securities yields and a $268.7 million reduction in wholesale funding. Deposits grew at an 8.5% annualized pace, which management said was close to double digits excluding brokered paydowns. That growth pushed the loan-to-deposit ratio down to 93.2% from 96.1%. Deposit costs rose only three basis points to 1.95%.
Management framed the balance sheet as asset-sensitive in a rising-rate environment. About $350 million a quarter of fixed-rate loans are repricing from roughly 5.15% to 7%–7.25%. Rate hikes late in the quarter are not yet fully reflected. That supports the raised Q4 net interest income guide of $103–105 million, the third consecutive step-up.
Bears have legitimate ammunition elsewhere. Loans fell about 1% to $7.5 billion as payoffs climbed to $396 million and line utilization slipped to 57% from 61%. That happened even though originations jumped 55% to $362 million. Management admitted it underestimated payoffs. It now guides Q4 loans flat, a retreat from Q2's expectation that payoffs would normalize, while still targeting mid-single-digit growth in 2027.
Credit and costs also moved the wrong way:
- Non-performing loans rose 23% sequentially to 1.14% of loans, driven by two credits: a solar loan and a C&I loan to a distressed consumer debt buyer.
- Reserve coverage of NPLs dropped to 133% from 162%.
- Net charge-offs rose to 31 basis points, within the 30–40 basis point guide.
- The Q4 expense outlook moved up to $62–64 million from a $59–60 million quarterly run rate, after salaries already drove a 147 basis point rise in the efficiency ratio to 48.4%.
- The head of commercial banking and the chief credit officer both retire at year-end. That transition arrives just as NPLs are rising.
There are offsets. Criticized and classified loans fell for a third straight quarter to 3.1%. CET1 rose to 13.29%. The dividend increased 16.7% to $0.14.
The forward catalysts are strategic and rate-driven. The Illinois State Bancorp acquisition adds core deposits and market presence, with closing expected in 2027. Management now expects to cross the $10 billion asset threshold in 2027, which pushes the roughly $3.5–4 million annualized Durbin interchange hit to the second half of 2028. The flip side of higher rates is that management flagged possible softness in CRE transaction volume and valuations next year.
Investors have not embraced the story. Earnings Whispers sentiment was already negative entering the report and weakened further, from -0.19 to -0.29. The shares, at $37.99, are down about 1% from the open following the July report, despite sequential earnings gains. The stock remains roughly 9% above its 200-day moving average, so the longer-term trend is intact even as near-term price action has stalled. The AVWAP reading is negative, consistent with a stock that has gone nowhere for a quarter.
The bottom line is that Byline's beat rests on genuine margin expansion and disciplined funding, aided by tax credits and buybacks, while the growth and credit picture softened. A rising-rate repricing tailwind and the Illinois State deal give the bull case substance. Flat loans, higher expenses, climbing NPLs and credit leadership turnover explain why sentiment cooled even as earnings hit a record.
Read our earnings preview for Byline Bancorp, Inc.: https://www.earningswhispers.com/article/BY/20559
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-08 | |
| Oct-06 | |
| Oct-01 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-09 | |
| Apr-25 | |
| Apr-23 | |
| Apr-23 | |
| Apr-07 | |
| Apr-03 |
