GrafTech Beats And Calls A Pricing Inflection, But $9 Million Of EBITDA Still Can't Cover The Interest Bill
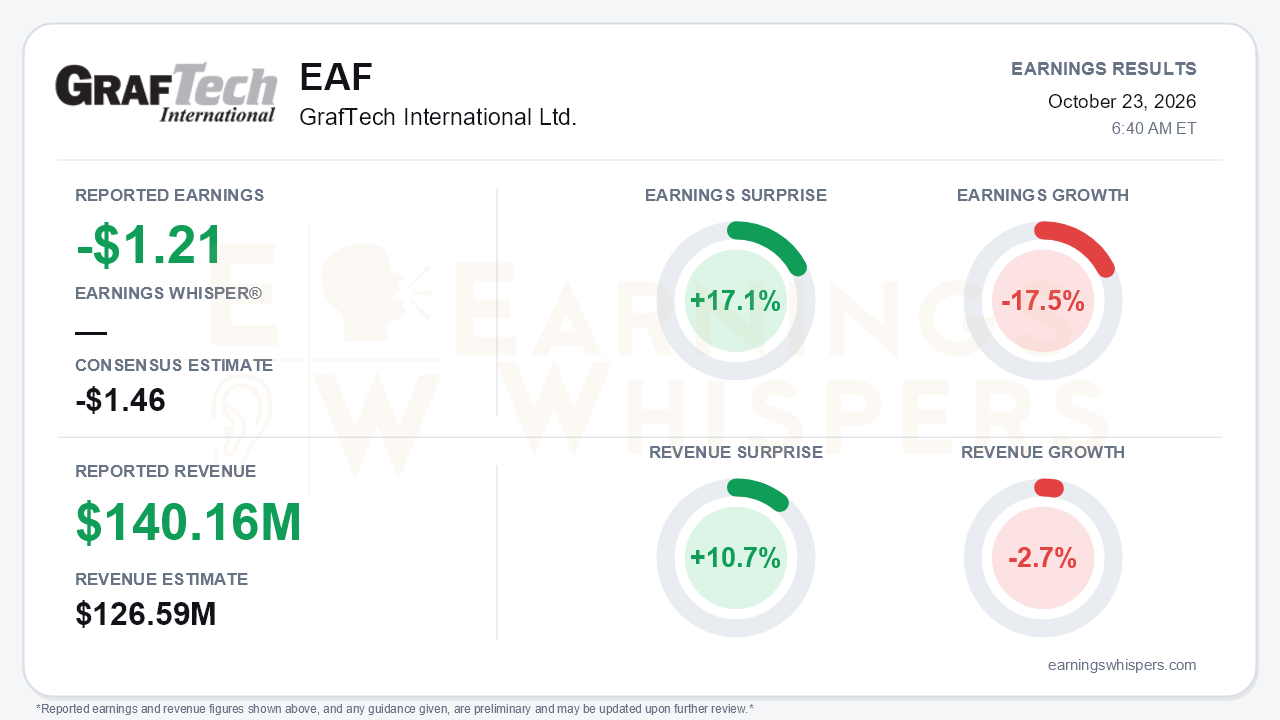
GrafTech International (NYSE: EAF) delivered a clean beat on a still-deeply unprofitable quarter. The adjusted loss of $1.21 per share was 17.1% better than the -$1.46 consensus, and revenue of $140.16 million beat the $126.59 million estimate by 10.7%. Year over year, however, the picture is weaker. Earnings fell 17.5% as the adjusted loss widened from $1.03, and revenue slipped 2.7%. The more important development is not the beat but the shift in management's message. After three straight quarters of realized pricing stuck near $3,900 per metric ton, GrafTech explicitly guided to a mid-single-digit sequential price increase in the fourth quarter. It also paired that guide with the closure of its highest-cost plant. That is the central tension: the commercial and cost story is finally turning, while the balance sheet keeps absorbing the cost of getting there.
The quality of the quarter deserves scrutiny. On a GAAP basis, the net loss widened to $47 million, or $1.76 per share, versus $28 million a year ago. The gap includes $14 million of mostly non-cash restructuring charges tied to the Monterrey, Mexico closure. Adjusted EBITDA of $9 million trailed the $13 million posted a year earlier because realized price was down 7% year over year. Sequentially, though, the trajectory is real: adjusted EBITDA has climbed from -$22 million in Q4 2025 to -$14 million, then $2 million, and now $9 million. Cash cost of goods sold per ton fell to $3,653 from $3,795 a year ago, although it rose from Q2's $3,517 as production dropped 19% sequentially and utilization fell to 64% from 74% during maintenance. Adjusted free cash flow improved to -$16 million from -$75 million in Q2. Even so, it was still negative, with an $11 million inventory build that management says should reverse in the fourth quarter.
The call marked a clear step up in tone. Just a year ago management said 2026 pricing would be no better than 2025. Now it says realized pricing has reached an inflection point. Customer commitments secured in Q3 and early Q4 carry higher prices than earlier ones. A second 30% price increase announced in September applies to all 2027 negotiations, and the CEO described 2027 pricing as margin-accretive despite input inflation. Supporting the argument, merchant needle coke prices have risen to roughly $1,700-$2,000 per ton from $1,000-$1,200 at the start of the year, and Chinese electrode exports are down about 10%. Volume guidance of 5-10% growth was reaffirmed, with year-to-date volume up 7%. Management also reaffirmed its targets for a low-single-digit decline in cash cost per ton and roughly $35 million of capex.
The Monterrey closure is the most tangible catalyst. It shrinks capacity to about 127,000 tons and targets $20-$25 million in annual cash savings, with the full benefit in 2028. It should also reduce capex by roughly $5 million from 2027 and release $20-$25 million of working capital. A separate collaboration with Antora Energy on thermal batteries puts stranded St. Mary's assets to work. Bears have legitimate ammunition, however:
- The closure requires $20-$25 million of one-time cash costs, mostly through 2027.
- Preliminary U.S. anti-dumping determinations on China and India came in below expectations, and the final ruling slipped to Q1 2027.
- European energy contracts reset higher in 2027.
- Safety metrics deteriorated.
Most importantly, Q3 interest expense of nearly $26 million is roughly three times adjusted EBITDA. Liquidity has drifted from $340 million at year-end to $242 million, against $1.09 billion of net debt and a $388 million stockholders' deficit. The saving grace is that there are substantially no maturities until December 2029. That date sets the window in which the pricing recovery has to show up in cash.
Investor sentiment improved meaningfully into the report, moving from modestly negative (-0.16) to slightly positive (+0.05). That suggests expectations for a turn were already building. Price action has been far more volatile than the fundamentals. Shares bottomed at $5.71 on September 9, spiked to $11.89 by September 23 around the price-increase and closure announcements, and then gave back most of the move. At $7.45, the stock is only 2.8% above where it opened after the July report and sits 13.7% below its 200-day moving average of $8.63. The AVWAP reading remains negative, consistent with a stock that has not held its September enthusiasm.
The bottom line is that GrafTech has moved from hoping for a pricing recovery to guiding for one, and the Monterrey closure gives the cost story a concrete anchor. The beat and the sequential EBITDA climb make the narrative credible. Still, the company is generating single-digit EBITDA against a roughly $100 million annual interest run rate and steadily declining liquidity. The fourth-quarter price increase and the reception of the 30% hike in 2027 negotiations now matter far more than this quarter's surprise.
Read our earnings preview for GrafTech International Ltd.: https://www.earningswhispers.com/article/EAF/20603
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 6 hours | |
| 15 hours | |
| 15 hours | |
| Oct-01 | |
| Sep-11 | |
| Sep-10 | |
| Sep-08 | |
| Sep-01 | |
| Aug-31 | |
| Jul-24 | |
| Jul-24 | |
| Jul-22 | |
| Jul-02 | |
| May-27 | |
| May-02 |
