Balchem's Record Q3 Beats On Margins And Cash Flow, But Cooling Sales Growth Is The Tension To Watch
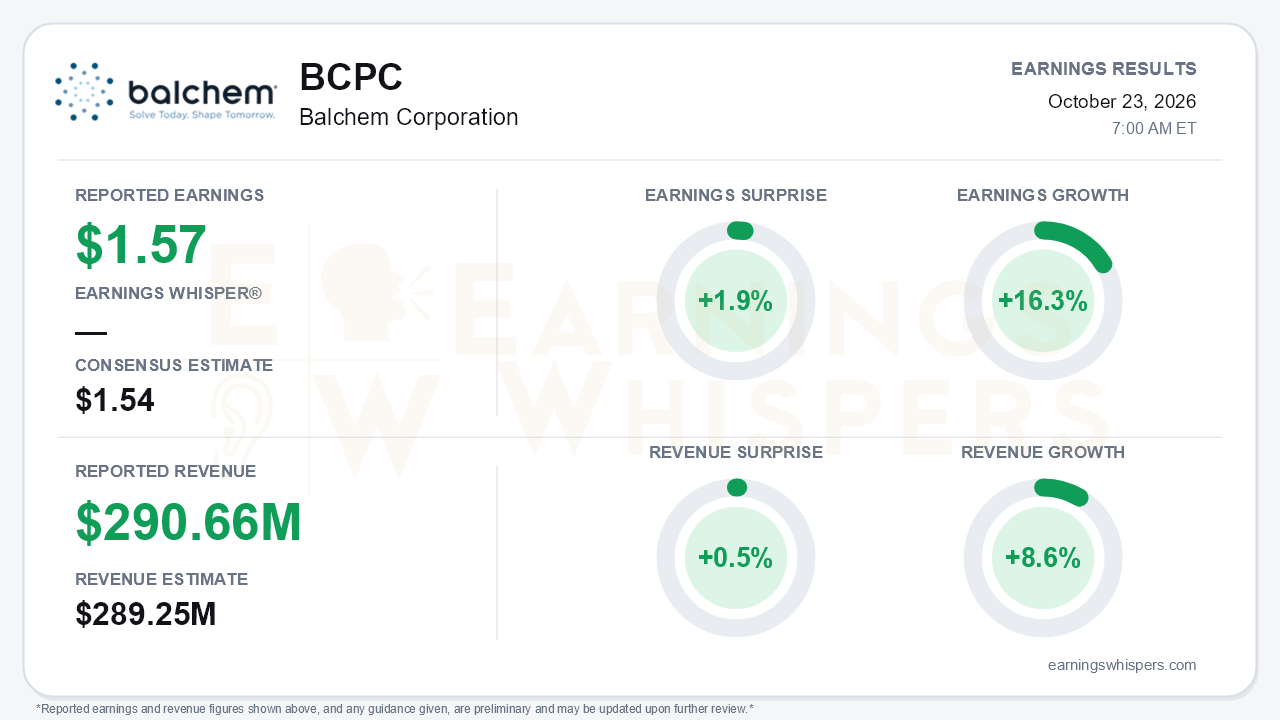
Balchem delivered a record third quarter that won on profitability more than volume. Adjusted EPS of $1.57 topped the $1.54 consensus by 1.9%, and revenue of $290.66 million edged past the $289.25 million estimate by 0.5%. Earnings grew 16.3% year over year on 8.6% revenue growth. That gap between bottom-line and top-line growth defines the quarter. Gross margin, adjusted EBITDA margin and free cash flow all improved, while sales growth slowed in every segment from the second quarter's pace. The beats themselves were narrow. The more meaningful development is that Balchem is converting slower growth into faster earnings.
The beat holds up reasonably well under scrutiny. GAAP EPS rose to $1.46 from $1.24, and GAAP net earnings climbed 16.0%. A slightly lower GAAP tax rate (22.2% versus 22.6%) helped at the margin, but the adjusted figures apply a 22.6% rate in both periods, so the non-GAAP growth was not tax-driven. Two other contributors deserve mention:
- Share repurchases reduced the diluted share count by roughly 1.7% year over year.
- Operating expenses benefited from net favorable discrete items.
The core driver was operational. Gross margin expanded 70 basis points to 36.4%, compared with only 10 basis points of expansion in Q2, on mix and manufacturing efficiencies. Adjusted EBITDA reached a record $80.3 million, up 12.4%, with a 27.6% margin versus 27.4% in each of the first two quarters. Free cash flow of $57.9 million was a step change from $36 million in Q2 and $34 million in Q1. Net leverage fell to just 0.2x even after $28 million of buybacks in the quarter.
The call made the deceleration explicit. Consolidated sales growth slowed to 8.6% from 11.2% in Q2, and each segment cooled:
- **Human Nutrition and Health:** sales grew 8.1%, down from 10.0% in Q2 and 12.7% in Q4 of fiscal 2025.
- **Animal Nutrition and Health:** sales growth eased to 11.7% from 15%, with sales dipping sequentially to $63 million.
- **Specialty Products:** growth roughly halved to 4.5% from 8.9%, and sales fell to $37 million from $41 million in Q2.
The profit story ran the other way. Animal Nutrition operating earnings jumped 82.8% to $6.8 million, building on 48.7% growth in Q2, helped by ruminant penetration, US monogastric pricing and gains from EU anti-dumping duties. That increase comes off a small base, but the trajectory is real. Management's tone was upbeat. It also noted that the margin-rate pressure it had flagged earlier from Middle East-driven inflation has largely not materialized: raw-material pass-through is break-even year to date, and favorable mix is absorbing the rest.
The forward catalysts are more scientific and regulatory than financial:
- **VitaCholine:** the MD Anderson-led ApoE4 choline pilot study, flagged as pending on prior calls, is now published and could lead to a larger adult-cognition trial.
- **K2VITAL Delta:** the roughly 400-subject DANCODE trial in Circulation supports a cardiovascular benefit.
- **Animal Nutrition:** a next-generation encapsulated methionine launched October 1.
- **Trade protection:** a US anti-dumping petition on choline should get a preliminary ruling near year-end.
Bears still have legitimate ammunition. Inventory rose to $177 million from $131 million at year-end, which management attributed to inflation, growth, deliberate safety stock against geopolitical disruption, and pre-launch builds. Year-to-date working-capital changes consumed $31.5 million, versus $12.9 million a year ago. Management also called high oil prices a net negative, said EU duty circumvention continues, and expects Q4 to be sequentially lower on seasonality. No formal guidance was offered beyond a reaffirmed 22.5% to 23% tax rate.
Investor sentiment remains firmly negative but improved meaningfully, rising from -0.73 at the prior report to -0.61. That skepticism sits awkwardly with a company that has extended its adjusted EBITDA growth streak to 29 consecutive quarters. The stock has drifted higher, up 6.2% from the open after the July report to $173.23 entering earnings. Shares sit 2.6% above their 200-day moving average, but they have not held the August 24 peak of $182.99 and remain 5.3% below it. The Earnings Whispers trend signals lean positive, with sequential growth, momentum and AVWAP readings favorable, while price trend is only neutral. That pattern fits a stock grinding upward rather than being re-rated.
The bottom line is that Balchem's quarter was higher quality than its narrow beats suggest: margins, cash generation and balance-sheet flexibility all improved, and the clinical pipeline gained tangible support. The open question is whether earnings can keep outrunning a top line that has now slowed for a quarter across all three segments, while inventory builds and oil-linked costs linger. Until revenue growth stabilizes, cautious sentiment has a reasonable basis, even as the fundamental evidence keeps leaning the company's way.
Read our earnings preview for Balchem Corporation: https://www.earningswhispers.com/article/BCPC/20602
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-23 | |
| Oct-23 | |
| Oct-09 | |
| Sep-09 | |
| Aug-18 | |
| Jul-31 | |
| Jul-31 | |
| Jul-17 | |
| Jun-26 | |
| May-27 | |
| Apr-30 | |
| Apr-25 | |
| Apr-22 | |
| Apr-16 | |
| Apr-10 |
