First Western Beats On Accelerating Loan Growth, But A Tax Credit And Wholesale Funding Did Some Of The Lifting
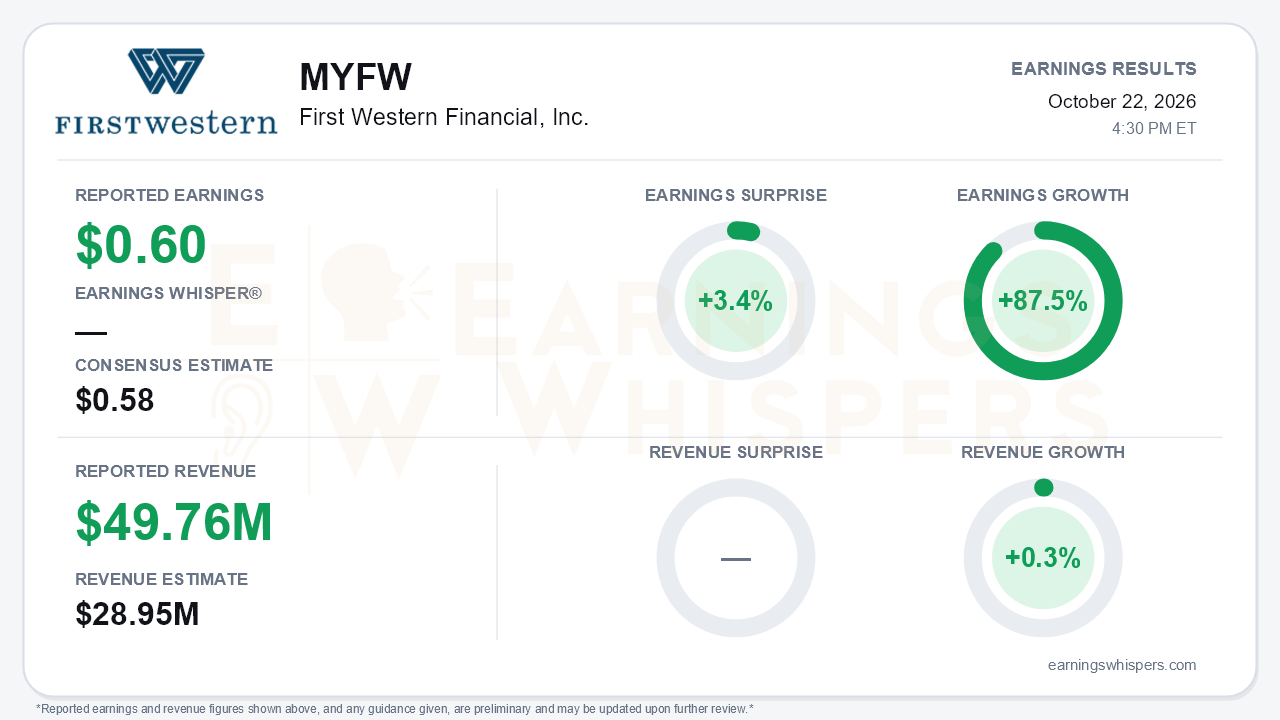
First Western Financial (NASDAQ: MYFW) earned $0.60 per diluted share in the third quarter, beating the $0.58 consensus by 3.4%. Earnings grew 87.5% from $0.32 a year ago and rose from $0.57 in the second quarter. Net income available to common shareholders reached $6.0 million, versus $3.2 million a year earlier. The bigger story is the loan book. Loans held for investment grew $95 million, or 3.5%, in the quarter, compared with just $23 million in Q2. On that basis, management raised its growth framing to roughly 10% for 2026 and about a 15% run rate into 2027. This was the most constructive quarter of the year operationally, but the headline beat deserves some scrutiny.
Start with what is behind the earnings beat. Pre-tax income actually slipped to $7.28 million from $7.40 million in Q2. A $0.6 million provision replaced the prior quarter's $0.5 million release. The per-share gain came from a lower tax bill. Tax expense fell $0.4 million because of a purchased clean fuel tax credit. That is worth roughly $0.04 per share, which is more than the size of the beat. Management pointed to a normalized tax rate of about 23%.
The core engine is still clearly improving:
- Net interest income rose 5.5% sequentially and 17.9% year over year, to $23.0 million.
- Pre-tax, pre-provision income climbed 14.5% sequentially.
- The efficiency ratio improved to 72.2% from 74.0%.
The reported revenue figures need context. Earnings Whispers' $49.76 million revenue figure, up 0.3% year over year, reflects gross interest and fee income. The consensus appears to be built on net revenue, and the company's own gross revenue measure was $28.9 million. That makes the 71.9% revenue surprise a basis mismatch rather than a genuine blowout. On a net basis, gross revenue grew 9.9% year over year, so growth is better than the 0.3% headline suggests.
The call added real substance to the growth story:
- **Loan production:** jumped to $163 million from $115 million.
- **New-production yields:** rose to 6.79% from 6.37%, about 53 basis points above payoff yields.
- **Margin:** net interest margin reached 2.95%. Year-to-date expansion of 24 basis points nearly matches 2025's 26 basis points, even though management earlier cautioned that 2026 might fall short of that.
- **Fees:** trust and investment management fees rose 2.6% sequentially, which management described as the first such trend in years.
- **Credit:** non-performing assets fell to 0.39% of assets from 0.50%.
- **Targets:** management reaffirmed its 1% ROA target for 2027 and added a new medium-term line of sight to 1.5% ROA, drawn from an internal three-year forecast. Tone was the most confident of the year, with management saying "the flywheel has begun."
Bears still have legitimate ammunition.
- **Slowing margin gains.** Quarterly NIM increments have shrunk from 17 to 10 to 9 to 5 basis points. Cost of funds rose 2 basis points after declining in Q2, and the spot deposit cost moved up to 2.86% from 2.80%.
- **Funding gap.** Deposits grew $70 million against $95 million of loan growth. FHLB borrowings jumped to $150.9 million from $36.4 million. Year-over-year deposit growth slowed to 2.5% from double digits in Q2.
- **Thinner capital and reserves.** Bank CET1 fell to 10.79% from 11.37%. The $10 million subordinated note redemption lowered consolidated total capital to 11.80% from 12.47%. Allowance coverage drifted down to 74 basis points.
- **Weaker fees and higher costs.** Noninterest income fell 9.4% as mortgage gain-on-sale weakened under higher rates. Management also described competitors pricing loans at 90 to 95 basis points over Treasuries, and expenses have settled near $21 million a quarter.
The September Fed hike cuts both ways. Management expects roughly $1 billion of floating-rate loans and bonds to benefit starting in Q4, and $370 million of loans mature or reprice through 2027. The same move pressures deposit costs and mortgage activity.
Investors have not embraced the story. Earnings Whispers sentiment, already negative before the report, weakened from -0.17 to -0.28, a meaningful but not dramatic shift. At $29.98, shares are 5.3% below the open following the July report. They remain about 4.6% above the 200-day moving average of $28.65. The stock is trading modestly above book value of $29.48, with tangible book value at $26.28, up 11% year over year. AVWAP trend readings remain negative.
The bottom line is that First Western delivered the operating acceleration it has been promising: faster loan growth, better new-loan pricing, continued margin expansion and steadily compounding book value. The EPS beat itself, however, leaned on a one-time tax credit. Growth is increasingly funded with borrowings rather than deposits. Margin gains are slowing just as the rate backdrop turns. Expanding the loan book is now the easy part. Holding NIM gains as funding costs rise is the harder test, and the souring sentiment suggests investors want proof before paying for the 1.5% ROA ambition.
Read our earnings preview for First Western Financial, Inc.: https://www.earningswhispers.com/article/MYFW/20578
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-22 | |
| Oct-22 | |
| Oct-08 | |
| Sep-15 | |
| Aug-21 | |
| Jul-30 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-09 | |
| May-11 | |
| Apr-25 | |
| Apr-23 | |
| Apr-23 |
