Glacier Bancorp Crosses 4% Margin A Quarter Early And Raises Repricing Outlook, But Shares And Sentiment Still Lag
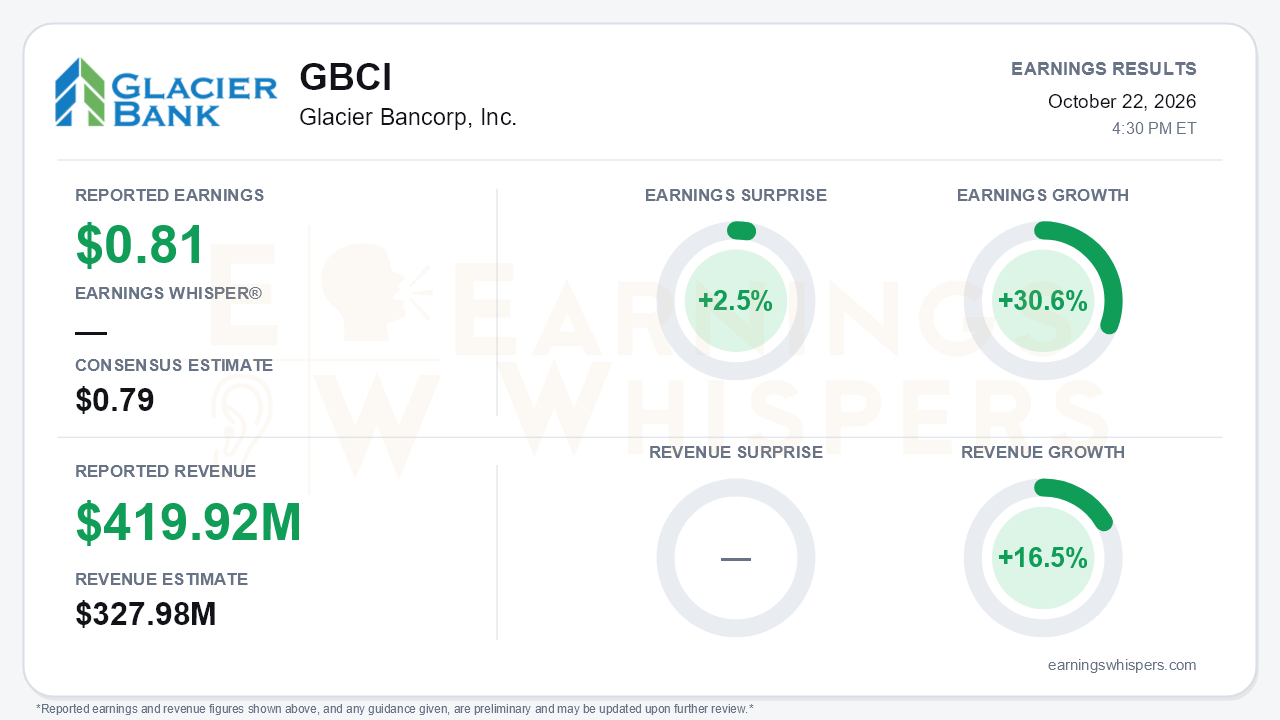
Glacier Bancorp (NYSE: GBCI) delivered the quarter its margin story has been building toward. Operating EPS of $0.81 beat the $0.79 consensus by 2.5% and rose 30.6% year over year. GAAP net income hit a record $104.6 million, the company's first quarter above $100 million. The supplied revenue figure of $419.92 million topped the $327.98 million consensus by 28.0% and grew 16.5%. On the release's own presentation, net interest income plus fee income came to $329.8 million, which makes net interest income the more telling gauge. It rose 29% year over year and 5% sequentially to $290 million. The bigger news is the margin. Net interest margin reached 4.01%, its eleventh consecutive expansion. Management had guided in the second quarter to reach 4% only in early Q4, so the milestone arrived a quarter ahead of plan.
The beat itself was narrow, but the quality is reasonably clean. Core NIM, which strips out purchase accounting and non-accrual effects, rose 9 basis points to 3.95%, so the expansion was not an accretion artifact. Loan yields climbed 10 basis points to 6.22% while core deposit costs slipped a basis point to 1.17%. The efficiency ratio improved to 56.08% from 62.05% a year ago, and ROA rose to 1.31%. Two items deserve scrutiny:
- **Deposit growth was flattered.** The headline 10% annualized deposit growth includes a temporary quarter-end deposit that the company expects to largely leave in Q4. Excluding it, deposits grew a more ordinary 5% annualized and non-interest-bearing balances 11%.
- **Credit is stable sequentially but elevated year over year.** Non-performing assets of $90.6 million edged down from Q2 but are 67% higher than a year ago. Net charge-offs doubled to $6.0 million, though $3.5 million of that was deposit overdrafts. Early-stage delinquencies fell to 0.27% overall, yet first-lien 1-4 family delinquencies roughly tripled sequentially to $22.1 million.
The call strengthened the forward margin case more than the quarter itself did. About $3.5 billion of loans are now expected to reprice 125-150 basis points higher over the next year. In Q1 the figure was $3 billion at 75-100 basis points. Securities runoff is being reinvested roughly 350 basis points above maturing yields, and new production is coming on at 6.74%. Management now describes the balance sheet as modestly asset-sensitive and frames Fed hikes as a net positive, assuming a 20-25% total deposit beta. It reiterated a 4-4.5% historical NIM range and suggested the current environment could push toward the upper end. Capital return also became more concrete. The dividend rose 6% to $0.35, and buybacks and special dividends are now explicitly under consideration.
The rate of improvement, however, is moderating at the margins:
- **Deposit costs.** The outlook shifted from "stable" last quarter to drifting higher, with spot costs at 1.20%. Management expects Q4 NIM expansion to fall short of roughly 10 basis points.
- **Loan growth.** It slowed to 5% annualized from 6%, with seasonal softness expected into Q4 and Q1. The low-to-mid single-digit guide was only maintained, and the quarter's growth was concentrated almost entirely in commercial real estate.
- **Expenses.** Core operating expense landed at the high end of guidance on performance compensation, and Q4 is likely to do the same, though the 54-55% Q4 efficiency target was reaffirmed.
- **Fees and M&A.** Fee income dipped about $1.8 million on a non-recurring item. M&A commentary was absent after muted pipelines in Q2.
That is the central tension. The margin engine is running ahead of schedule and the repricing runway has lengthened, but the easy quarterly gains are giving way to slower increments. Sequential operating EPS gains have narrowed from $0.06 to $0.05.
The market has not yet paid for the improvement. Investor sentiment remains negative, though it improved modestly from -0.286 to -0.251, a shift too small to signal a real change in positioning. At $47.81, shares are 3.7% below the $49.64 open after the July report. They sit just 0.3% above the 200-day moving average of $47.65, and the Earnings Whispers price and AVWAP trend readings remain negative. The release shows the stock closed September at $43.20 after trading as high as $54.58 during the quarter, so the current price reflects a partial rebound. The supplied inter-earnings range data is harder to read: it places both the $48.45 high and $45.84 low on the post-report session, which sits inside the quarter's wider band. Either way, the stock is trading near its long-term trend line rather than breaking clear of it.
The bottom line is that Glacier's quarter validated its repricing thesis earlier than promised and extended its visibility into 2027. Investors remain skeptical, and the next leg depends on whether deposit-cost creep, slower loan growth and elevated nonperformers stay contained enough to let the $3.5 billion repricing tailwind reach the bottom line.
Read our earnings preview for Glacier Bancorp, Inc.: https://www.earningswhispers.com/article/GBCI/20569
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-22 | |
| Oct-22 | |
| Sep-28 | |
| Sep-22 | |
| Aug-31 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jun-30 | |
| Jun-23 | |
| Apr-25 | |
| Apr-23 | |
| Apr-23 | |
| Apr-06 |
