Comfort Systems Posts A Record $17.8 Billion Backlog And Raises Guidance Again As Margins Slip And Shares Sit Near 30% Lower
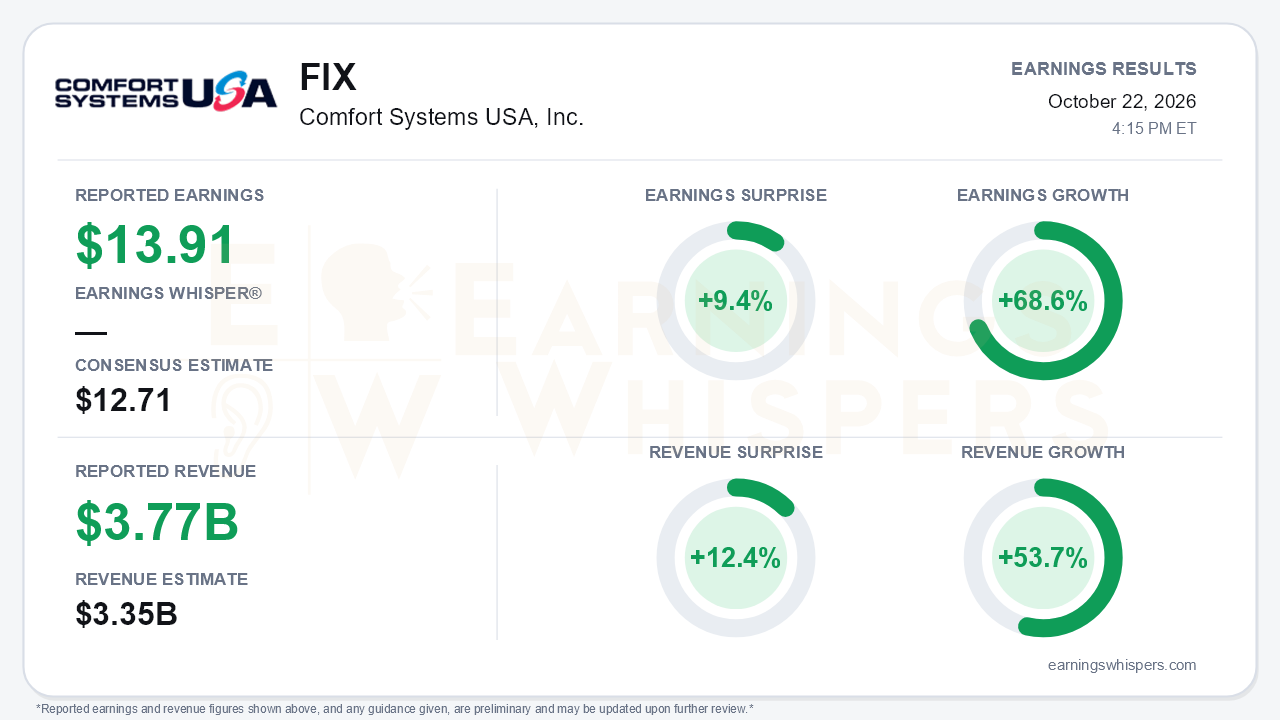
Comfort Systems USA delivered another emphatic beat, and the real headline sits beneath the earnings line. Third-quarter EPS of $13.91 topped the $12.71 consensus by 9.4% and grew 68.6% year over year. Revenue of $3.766 billion beat the $3.35 billion estimate by 12.4% and rose 53.7%. Backlog then jumped $3.8 billion in a single quarter to $17.81 billion, up from $14.06 billion in June and $9.38 billion a year ago. Management called it the largest quarterly booking surge in company history. That is the central tension of the report. The demand story has rarely looked stronger, yet the stock has fallen roughly 30% since the last report, and the quarter carried the first visible signs of sequential margin dilution.
The quality of the beat holds up well. The upside came from operations rather than financial engineering. Gross margin held at 24.8% year over year, while SG&A fell to 8.3% of revenue from 9.4%. That leverage lifted operating margin to 16.6% from 15.5% and Adjusted EBITDA margin to 17.7% from 16.9%. Some help came from below the operating line:
- Interest income rose to $14.5 million from $3.4 million.
- Earn-out charges were smaller than a year ago.
Those tailwinds were partly offset by a higher effective tax rate. Sequentially, the earnings line kept climbing, with EPS of $10.51 in Q1, $12.53 in Q2 and $13.91 now. Cash generation was striking, with $1.01 billion of operating cash flow and $806 million of free cash flow. Investors should temper that figure for two reasons:
- About $166 million of tax payments were deferred into the fourth quarter.
- Favorable payment terms from technology customers helped. Billings in excess of costs nearly doubled from year-end to $3.87 billion.
The call pointed to a business still accelerating at the top line. Management raised its 2026 same-store revenue growth outlook to the mid-40% range. That is the fourth consecutive increase from a starting point in the mid-to-high teens. It also introduced an initial 2027 same-store target of mid-20% growth. Electrical revenue rose 85% and mechanical 43%. Service revenue growth improved to 13% from 7% in Q2. Backlog duration has stretched to roughly 18 to 24 months, which improves visibility. Management's tone was the most emphatic yet: it said labor, not demand, is the binding constraint on growth.
Margins are where bears have legitimate ammunition. Gross margin slid to 24.8% from 25.9% in Q2 and 26.3% in Q1. Electrical gross margin fell to 24.3% from 26.4% in Q2. Management cited three causes:
- A roughly two-point heavier equipment and material mix.
- About $12 million in higher purchase-accounting adjustments.
- Contingencies on early-stage jobs.
Notably, management declined to promise margin expansion and guided only to the "strong ranges" of recent quarters. The benefit from estimate changes also shrank, which suggests earlier profit tailwinds are normalizing.
The forward catalysts are substantial:
- Modular capacity is now targeted at about 6 million square feet by end-2027, up from 5 million by late summer 2027.
- Modular work has begun for a frontier AI lab and colocation providers, though it is not yet programmatic.
- Boyce Electrical and Neopod add more than $100 million in annual revenue.
- The quarterly dividend rose to $1.00, and the company repurchased about $200 million of stock.
The risks are concentrated and real. Technology now accounts for 59% of revenue versus 42% a year ago. Management is increasing credit scrutiny of newer data center counterparties. Political talk of data center moratoriums has not yet affected projects. Management also warned that a booking quarter this large could mean lighter bookings ahead. Separately, CFO Bill George, a longtime leader of M&A and operations, will retire after the 2026 results and be succeeded by Julie Shaeff.
The market setup is more complicated than the surprise implies. Shares closed at $1,279.37, down 29.8% from the $1,821.33 open after the July report and about 19.8% below the 200-day moving average. Earnings Whispers price and AVWAP trend readings remain negative. Investor sentiment cooled from 0.24 to roughly neutral at 0.01. That suggests enthusiasm faded considerably heading into the print even as fundamentals strengthened. The selloff appears to reflect worries about data center concentration, margin durability and the sustainability of AI-driven construction spending more than anything in the reported numbers.
The bottom line is that Comfort Systems delivered accelerating growth, a step-change in backlog, a fourth guidance raise and 2027 visibility that few contractors can match. The flaws were real but modest: sequential margin slippage, flattered cash flow and rising customer concentration. Those flaws, not the demand picture, now define the debate. With shares well below trend and sentiment near neutral, expectations have reset meaningfully lower. Whether that reset proves an overreaction depends largely on margins stabilizing within management's stated ranges as the backlog converts.
Read our earnings preview for Comfort Systems USA, Inc.: https://www.earningswhispers.com/article/FIX/20621
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-16 | |
| Sep-17 | |
| Aug-30 | |
| Aug-13 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 |
