Kilroy Realty Misses By A Penny As A Leasing Surge Collides With 2027 Earnings Headwinds
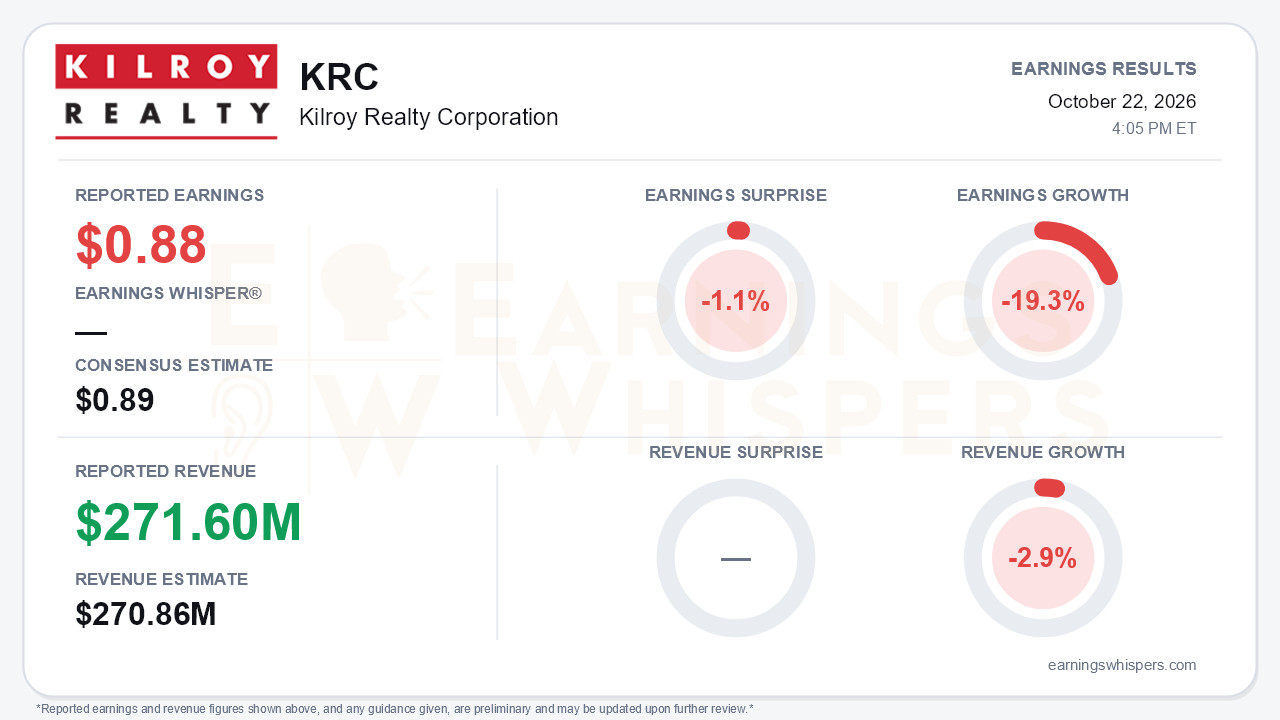
Kilroy Realty (NYSE: KRC) delivered a quarter where the headline and the underlying trend point in opposite directions. Third-quarter FFO of $0.88 per share missed the $0.89 consensus by 1.1% and fell 19.3% from a year ago. Revenue of $271.6 million edged past the $270.86 million estimate by 0.3% but declined 2.9% year over year. Read only the numbers and this is a shrinking office REIT that came in slightly light. Read the leasing data and it is arguably the strongest operating quarter of Kilroy's recovery. That is the central tension: leasing is recovering faster than earnings can, and the bridge between the two runs through a difficult 2027.
The quality of the earnings decline deserves scrutiny, because little of it reflects deteriorating leasing economics. Interest expense rose to $39.4 million from $32.2 million. Interest income fell to $0.6 million from $3.1 million after cash balances were drawn down to repay debt. Real estate taxes climbed about $4.4 million. On a GAAP basis, net income available to common stockholders dropped to $0.13 per share from $1.31. The prior-year figure was inflated by $110.5 million of property-sale gains, so that comparison overstates the deterioration. Share repurchases of $72.7 million this year trimmed the diluted count and softened the per-share damage. Still, the financing drag is real, and the reported operating trends were not clean. Cash same-property NOI fell 1.5% in the quarter, versus gains of 1.5% in Q2 and 1.8% in Q1. Physical occupancy slipped again to 76.9%, from 77.0% in Q2 and 77.6% in Q1.
The forward indicators tell a much better story. Kilroy signed roughly 815,000 square feet of leases, compared with 376,000 in Q2 and 568,000 in Q1. That lifted year-to-date volume 44% to 1.75 million square feet. Leased occupancy jumped 150 basis points to 83.0%, and all five regions gained more than 100 basis points. Rent spreads continued a striking reversal:
- GAAP and cash re-leasing spreads reached 30.6% and 9.7%.
- That compares with 21% and 6.1% in Q2.
- In Q1, spreads were negative 10.6% and negative 16.8%.
The signed-not-commenced pool expanded to 1.4 million square feet and $101 million of annualized base rent, up from $78 million. About $48 million of that rent is slated to commence by year-end 2027. Management cited accelerating early renewals, scarcity of large blocks, and new demand from robotics and defense/aerospace users. The 243,000-square-foot, 12-year Box renewal and progress past the letter-of-intent stage at Kilroy Oyster Point Phase 2 added tangible evidence. The forward pipeline grew another 20% sequentially after a 34% gain in Q2.
Guidance was effectively narrowed rather than meaningfully raised. Full-year FFO is now $3.55 to $3.59, versus $3.49 to $3.63, nudging the midpoint up $0.01. Cash same-property NOI guidance tightened to 0.75% to 1.0%. Lower lease termination fees and higher G&A partly offset better development NOI. The implied fourth quarter of roughly $0.86 continues a sequential slide from $0.92 in Q2 and $0.88 in Q3. Bears have legitimate ammunition for 2027:
- Capitalization of the Flower Mart project now ends in January 2027, a second delay that adds about $37 million of annual expense.
- $395 million of debt carrying a 3.8% rate will likely refinance higher.
- DirecTV is expected to largely vacate 484,000 square feet carrying $16 million of rent in late 2027.
- The abrupt August departure of the CFO leaves an interim finance chief in place during this transition.
On the positive side, the $19.5 million East Village land sale lifts land under contract to $185 million. That offers some capital flexibility, though management flagged higher rates as a watch item for transaction closings.
Investors have turned more skeptical. Earnings Whispers sentiment swung from a modestly positive 0.16 before the prior report to a negative -0.19, a meaningful shift. Price action has been more forgiving. At $37.27, shares are only 2.2% below the open following the July report and sit 7.7% above the 200-day moving average of $34.59. The post-report session was volatile, trading between $36.09 and $37.83, and the stock finished closer to the high. Trend readings are mixed, with price trend negative while AVWAP remains positive.
The bottom line is that Kilroy's quarter was weak on reported earnings but strong on the leasing metrics that drive future earnings. The call preserved a credible recovery story built on spreads, leased occupancy, and a growing rent backlog. That story still has to absorb lost capitalized interest, refinancing costs, and a large 2027 move-out before it shows up in FFO. The market appears willing to wait for that payoff, while sentiment shows investors are less convinced.
Read our earnings preview for Kilroy Realty Corporation: https://www.earningswhispers.com/article/KRC/20574
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-24 | |
| Oct-22 | |
| Oct-22 | |
| Sep-24 | |
| Sep-15 | |
| Sep-08 | |
| Aug-11 | |
| Jul-31 | |
| Jul-27 | |
| Jul-27 | |
| Jul-01 | |
| Jun-24 | |
| Jun-17 | |
| May-19 | |
| Apr-29 |
