Preferred Bank Edges Past EPS Estimates, But A Fresh $56.7 Million Nonaccrual Reverses Its Credit Cleanup And Squeezes The Margin
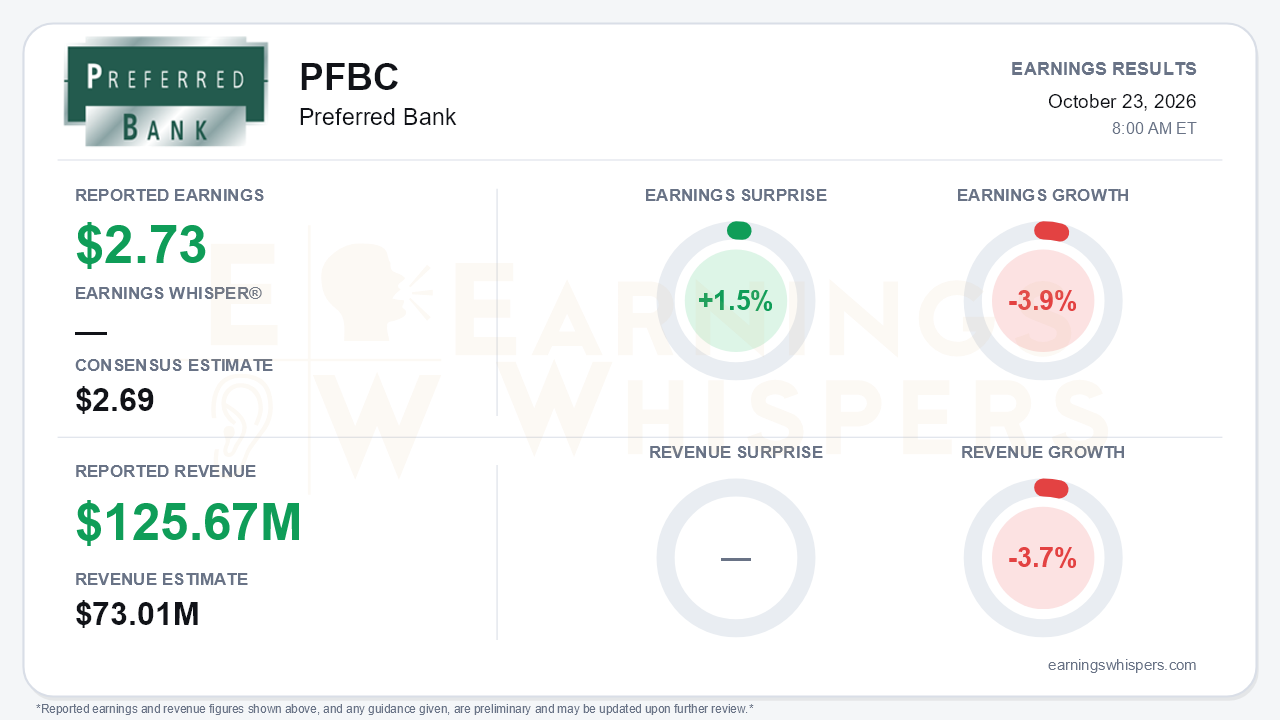
Preferred Bank (NASDAQ: PFBC) earned $2.73 per diluted share in the third quarter, topping the $2.69 consensus by 1.5%. Earnings still fell 3.9% from a year ago and slipped from $2.78 in the second quarter. Net income was $32.9 million. The modest beat came from fee income and expense control, not from the bank's core spread engine. The central development is credit. Last quarter the bank shrank its problem-loan book. This quarter it added a large new nonaccrual, which cost interest income and pushed nonperforming balances to a new high for the year.
The quality of the beat deserves scrutiny. Net interest income fell to $66.7 million from $70.0 million in Q2 and $71.3 million a year earlier. Three factors drove the decline:
- **Interest reversal:** the bank reversed $2.1 million of interest after moving a $56.7 million mixed-use loan and four others totaling $13.5 million to nonaccrual.
- **Tough comparison:** Q2 had benefited from $2.9 million of interest recoveries.
- **Debt costs:** subordinated debt converted from a 3.375% fixed rate to a floating SOFR-based coupon of 6.44%, and its interest expense jumped to $2.6 million from $1.5 million.
As a result, net interest margin fell to 3.49% from 3.73% in Q2 and 3.92% a year ago. Loan yields fell to 6.82% from 7.20%, while total deposit costs eased only slightly, to 3.04%.
What carried the quarter were the other lines:
- **Fee income:** noninterest income rose to $5.0 million, helped by $3.2 million of letter-of-credit fees and a $431,000 gain on a called security.
- **Expenses:** noninterest expense fell $1.6 million sequentially, mainly from lower personnel costs, and the efficiency ratio improved to 30.9%.
A note on revenue: the reported $125.67 million and its large surprise versus the $73.01 million consensus reflect gross interest income plus fees. Net interest income plus noninterest income was roughly $71.7 million, and that spread-based figure fell year over year. Investors should not read the 72.1% revenue surprise as a fundamental beat.
Asset quality is where the story turned. Nonaccrual loans plus loans 90 or more days past due rose to $109.4 million, excluding loans held for sale. That compares with $98.9 million in June and $51.3 million at year-end 2025. Allowance coverage of nonperforming loans thinned to 0.75x, versus 4.24x a year ago. Other real estate owned rose to $11.5 million from $3.0 million.
Management offered real mitigants:
- The $56.7 million loan was moved to held for sale and is under contract to be sold at par, with closing expected in late October.
- Average loan-to-value on the problem commercial real estate cohort is 60.8%, and management sees no significant loss content.
- Net charge-offs were essentially zero.
Still, CEO Li Yu conceded that resolutions are progressing "slower than we had hoped." Several credits scheduled for this quarter have slipped to Q4 or Q1 2027 because they sit in bankruptcy courts. Legal fees tied to these loans are inflating professional-services expense.
The call material supplied for this quarter is effectively a duplicate of the Q2 call. There is therefore no genuinely new call-over-call evidence, and the forward commentary dates from July. That July framing was already cautious:
- **Margin:** NIM guided to the mid-3.50s for Q3, with compression flagged into next year.
- **Deposits:** $1.5 billion of CDs repricing slightly higher, plus funding competition that now includes deposits moving into equities.
- **Loans:** growth described as "a lot tougher" because of non-bank competition.
Q3 largely bore that out. Loans held for investment declined $41 million after the held-for-sale transfer, and deposits grew a modest $77.7 million. By our rough estimate, excluding the reversal would put the margin near or slightly above the guided range. The underlying trend is still lower.
The release did add two incremental positives:
- **Rates:** management expects the recent Fed rate increase to help an asset-sensitive balance sheet.
- **Loan pipeline:** the CEO cited a stronger pipeline that he hopes will produce solid fourth-quarter loan growth.
The rate increase cuts both ways. Accumulated other comprehensive loss widened to $46.7 million from $20.0 million, although capital remains solid at a 10.13% tangible common equity ratio and 11.26% CET1. Share count was flat, so buybacks the call flagged as an option were not used this quarter.
Investors have grown warier. Earnings Whispers sentiment, already slightly negative at -0.12 after the prior report, fell to -0.26. That is a meaningful deterioration, though not a collapse. Price action has been less dramatic. At $106.72, shares are down just 0.8% since opening at $107.63 after the July report, and they sit about 8.8% above the 200-day moving average of $98.07. Trend readings are mostly neutral, with AVWAP still positive. The market has held up the stock even as sentiment soured.
The bottom line is that Preferred Bank delivered a technical beat built on fees and cost discipline, while its two most important drivers moved the wrong way: margin and credit. Profitability remains strong, with a 16.18% return on equity and a sub-31% efficiency ratio. The par sale of the $56.7 million loan, the timing of the bankruptcy-delayed resolutions, and whether the promised loan pipeline shows up will determine whether this quarter marks a temporary setback or a lower earnings base.
Read our earnings preview for Preferred Bank: https://www.earningswhispers.com/article/PFBC/20610
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-23 | |
| Oct-23 | |
| Oct-07 | |
| Sep-16 | |
| Jul-22 | |
| Jul-22 | |
| Jul-22 | |
| Jul-09 | |
| Jun-17 | |
| May-20 | |
| Apr-23 | |
| Apr-22 | |
| Apr-22 | |
| Apr-20 |
