Silvercrest's Global Build-Out Faces Its First Revenue Test As Margins Stay Squeezed
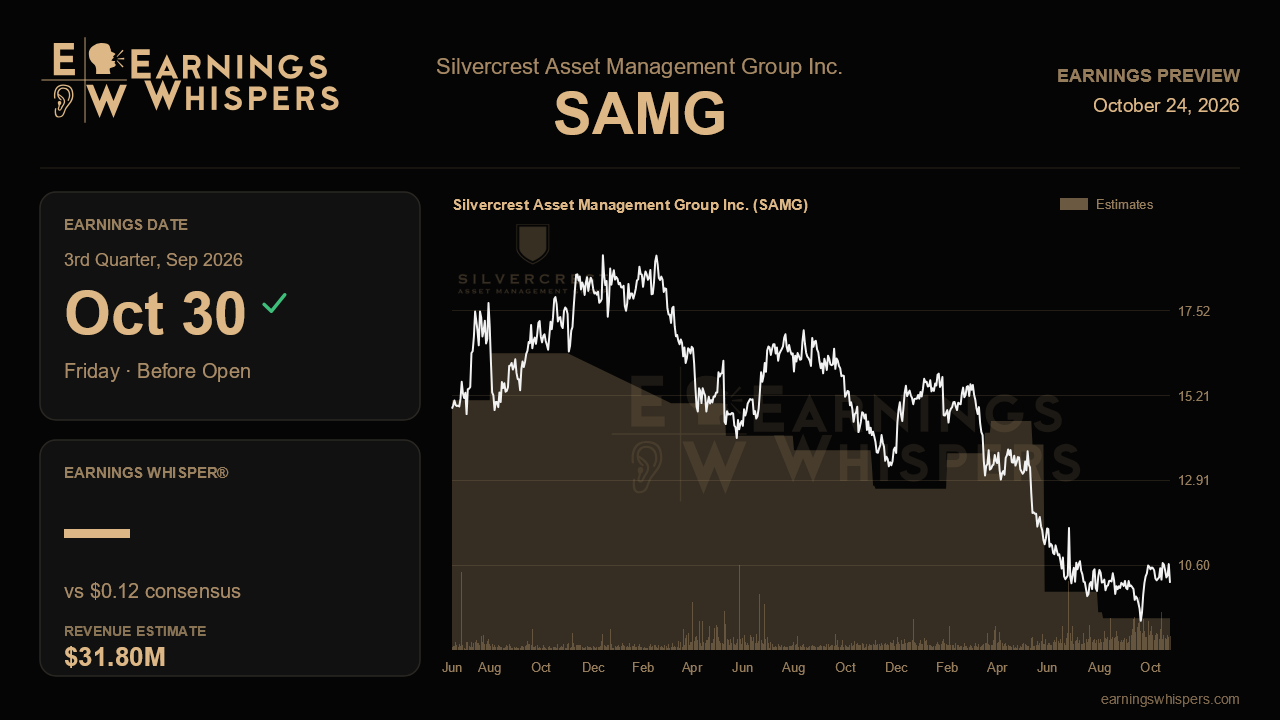
Silvercrest Asset Management spent last quarter telling investors that its expensive global expansion was finally crossing over from the cost phase into the revenue phase. Discretionary assets under management hit a record $24.7 billion at the end of June, an Australian client had just committed roughly US$350 million to the global value strategy, and the regulatory plumbing for European and Australian distribution was nearly finished. The third-quarter report, due before the open on October 30, is the first real chance to see whether that confidence shows up in the income statement, or whether the build-out remains a story told mostly in slides and asset totals.
The Street is not expecting much yet. Consensus calls for earnings of $0.12 per share on revenue of $31.8 million. That revenue figure implies growth of just 1.6% from a year ago, essentially flat. The earnings estimate implies a decline of nearly 37% from the $0.19 posted in the same quarter of 2025. The sequential picture is a little friendlier. Revenue would rise about $1 million from the second quarter's $30.8 million, and earnings would tick up from $0.10. Management did not offer formal numerical guidance, so the bar is set by the call's narrative rather than a stated range.
The arithmetic behind a sequential improvement is fairly straightforward. Silvercrest bills largely on assets, and management acknowledged that second-quarter revenue lagged because average AUM trailed the recovery. With the quarter opening at an all-time high and the Australian mandate funding around the turn of the quarter, fee revenue should benefit from a full period at higher asset levels. A revenue print at or above consensus would be the cleanest validation of the revenue-phase thesis. A miss would suggest market moves, value-book outflows or fee mix are eating more of the gains than the headline AUM implies. One wrinkle deserves attention. Management flagged a one-time reclassification of non-discretionary assets that will make total AUM look noticeably smaller this quarter. It carries no revenue effect, but it could make the release look worse at a glance than the business actually is.
The tougher question is margins. Adjusted EBITDA margin slid to 11.2% last quarter from 15.7% for full-year 2025. Compensation ran at roughly two-thirds of revenue, well above the firm's historical mid-50s model. G&A was up more than 19% year over year on travel and professional fees tied to the global push. Management said global administrative and legal costs should decline meaningfully as the setup work wraps up. Fresh equity grants under an expanded incentive plan, however, could keep compensation elevated. Investors should want evidence that G&A has stopped climbing and that the margin has at least stabilized. Another step down would undercut the idea that the heavy spending is behind the company. Cash, which fell to $20.7 million from $44.1 million at year-end alongside $9.5 million of borrowings, is also worth checking for signs of stabilization.
The pipeline matters too. Organic new client flows accelerated to $111 million last quarter. Management described an institutional pipeline in the billions, along with new consultant ratings, a Dublin office head and portfolio manager, and an expected Irish MiFID license by the end of the third quarter. Confirmation that the license is in hand, plus any additional funded mandates, would move the story from promise toward proof. Continued institutional outflows from the value book would temper it.
Sentiment has warmed but remains cautious, with bearish readings easing to about 52% from 70% before the last report. The stock has only matched the market since then, rising 2.5%, and at $10.12 it sits well below its 200-day average of $12.12. It trades in the middle of its post-earnings range, with no breakout in sight. That leaves room for a positive surprise, but only if the numbers back up the narrative. The central issue is simple. Silvercrest needs to show that record assets and new mandates are finally lifting revenue faster than the global build-out lifts costs. Without that, the revenue phase will look like just more of the cost phase.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-23 | |
| Sep-11 | |
| Aug-12 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-27 | |
| Jul-23 | |
| Jul-01 | |
| Jun-24 | |
| May-12 | |
| May-11 | |
| May-11 | |
| May-05 |
