Medifast Beats And Guides To A Fourth-Quarter Profit, But Cost Cuts Are Doing The Work While Coaches And Revenue Keep Shrinking
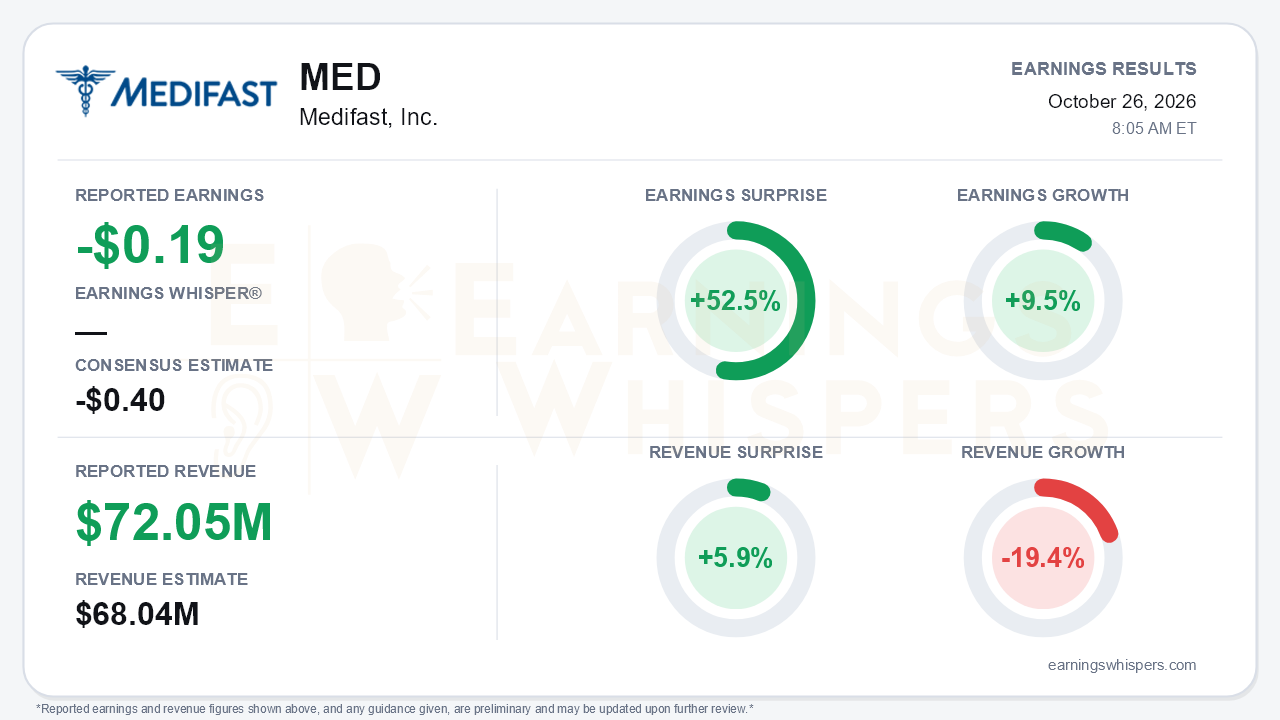
Medifast cleared a low bar with room to spare. The company posted an adjusted loss of $0.19 per share on revenue of $72.05 million for the September quarter. That beat the consensus estimate of a $0.40 loss by 52.5% and topped the $68.04 million revenue consensus by 5.9%. Adjusted earnings improved 9.5% from a year ago, and management guided to a profit in the fourth quarter. Revenue, however, fell 19.4% year over year. That is the central tension: Medifast is engineering its way back to profitability through cost removal and per-coach productivity, while the base of the business keeps getting smaller.
The quality of the beat deserves scrutiny. The GAAP loss widened sharply to $17.5 million, or $1.57 per share, from $0.21 a year ago. The difference reflects $15.4 million of Catalyst restructuring charges tied to closing distribution facilities, sunsetting internal software and resizing the organization to current revenue. Excluding those charges, the core improvement is real but modest:
- Adjusted gross margin rose 220 basis points to 71.7%.
- Adjusted SG&A fell 16.0%.
- The adjusted operating loss improved only 3.2%, to $4.0 million.
- Adjusted EBITDA excluding interest income was $1.9 million versus $1.7 million.
Adjusted SG&A still rose 310 basis points as a share of revenue, partly because of roughly 3 points of convention costs. In other words, the beat against consensus says more about how cautious estimates were than about a step change in operating economics. Management also noted that revenue merely landed in line with its own guidance.
The operating picture beneath the numbers is mixed. Active earning coaches fell to 10,200, down from 11,700 in the second quarter, 14,000 in the first and 19,500 a year ago, a 47.7% annual decline. Management expects the count to keep falling through year-end, citing client-acquisition pressure from GLP-1 medications. Revenue per coach jumped 54.1% to $7,064, extending an acceleration from +6.2%, +19.2% and +41% over the prior three quarters. But the company itself attributes that gain largely to the shrinking coach base. Sequential productivity growth also slowed to about 8% from 20% in the second quarter. CEO Nick Johnson argued that improving productivity has historically preceded coach and revenue growth. That may prove true, but the productivity tailwind is visibly losing speed just as the coach decline continues.
Guidance cuts both ways. Fourth-quarter EPS of $0.00 to $0.25 and new adjusted EBITDA targets (fourth quarter $2 million to $6 million; full year $10 million to $14 million, excluding interest income) give the turnaround a concrete profitability marker. The low end of full-year revenue guidance rose to $280-$300 million from $270-$300 million. Yet the implied fourth-quarter revenue range of $55-$75 million centers near $65 million, another sequential step down after revenue broke below the roughly $75-76 million plateau of the prior three quarters. That sits awkwardly with management's description of revenue as stabilizing around $75 million. A $20 million-wide quarterly range also signals limited visibility.
The new product and field initiatives are now in market and gave the call its constructive elements:
- Trilivy Reset Fuelings reached 95% of active coaches by September.
- A revised compensation plan launched August 1, alongside the Coach Hub training system.
- Select coach leaders are investing their own capital in the company.
Bears have legitimate ammunition elsewhere. Management again declined to quantify Catalyst savings despite a prior commitment to do so, and the Q&A drew a single analyst. The balance sheet removes any urgency: cash and investments rose to $172.5 million with no debt, up steadily from $167.3 million at year-end.
Investor sentiment improved modestly ahead of the report, rising from 0.26 to 0.36, and remains positive. Price action has been more sober. Shares closed the pre-report snapshot at $11.87, down 1.3% from the $12.03 open following the August report. They have given back most of the spike to a 52-week high of $13.45 that came the same day. The stock sat 11.7% below that high and just 5.4% above its inter-earnings low of $11.26, trading about 5% above its $11.30 200-day moving average. The Earnings Whispers trend readings are mixed: price trend is positive, while sequential growth and AVWAP remain negative.
The bottom line is that Medifast delivered a cleaner-than-expected adjusted quarter and a credible path to fourth-quarter profitability, backed by a cash-rich balance sheet. But profitability is being restored by shrinking the cost base to fit a shrinking business, not by growth. Until the coach count stops falling and revenue stops stepping down, the beat reads as successful cost execution rather than evidence that the metabolic-health pivot has turned demand.
Read our earnings preview for Medifast, Inc.: https://www.earningswhispers.com/article/MED/20636
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| 6 hours | |
| 6 hours | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Oct-01 | |
| Sep-29 | |
| Sep-02 | |
| Aug-27 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 |
