Fox Must Prove 40% Profit Growth Is More Than A Peak As Shares Outrun Market
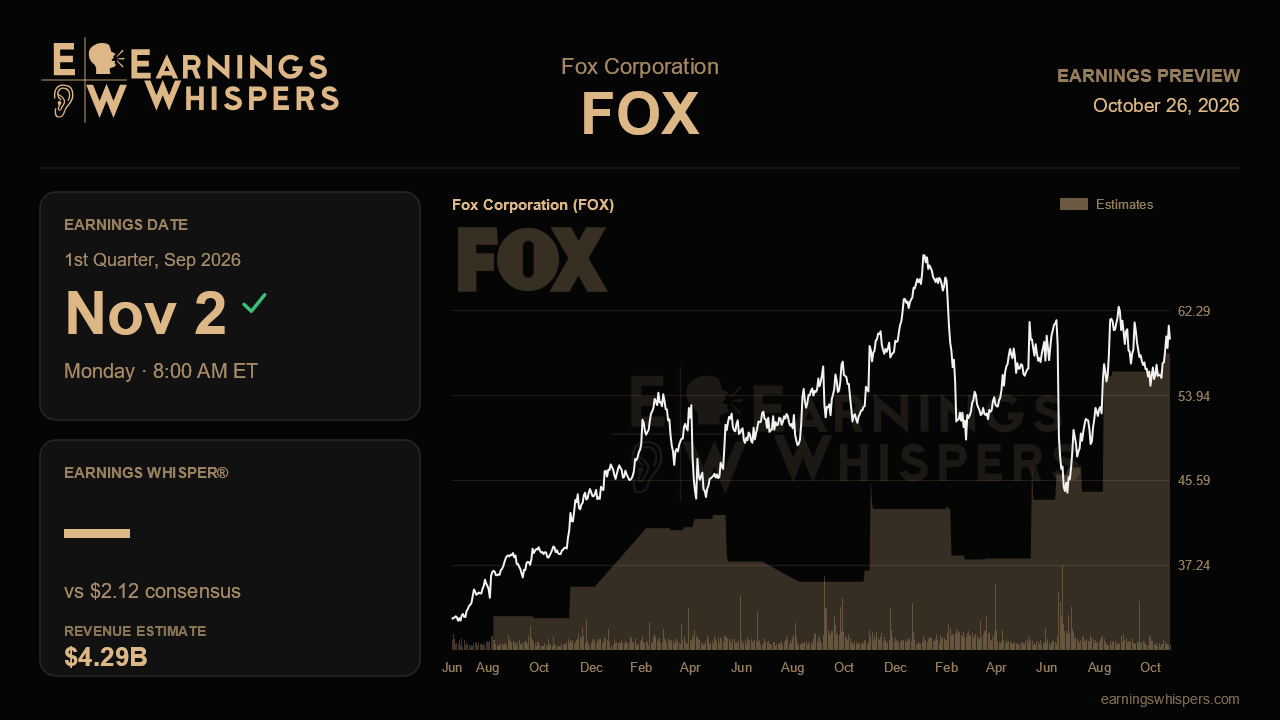
Fox Corporation heads into its next report with Wall Street asking it to do something harder than grow: it needs to convert a sizable jump in revenue into an even larger jump in profit. Analysts are looking for earnings of $2.12 per share, up about 40% from the $1.51 earned in the same quarter a year ago, on revenue of roughly $4.29 billion, a gain of nearly 15%. That gap between top-line and bottom-line growth is the story. Consensus is not just betting on more advertising and distribution dollars flowing in. It is betting that a large share of those incremental dollars falls straight through to earnings.
The sequential picture sharpens the point. Last quarter Fox reported $1.79 per share on $4.21 billion in revenue. The Street now expects revenue to tick up only about 2% from that level, while earnings per share climb roughly 18%. In other words, the forecast leans heavily on margin improvement rather than on a surge in sales. For a company whose results are driven by FOX News, FOX Sports, the broadcast network and its owned television stations, that kind of leverage typically depends on two things: strong pricing for advertising inventory and disciplined control over programming and rights costs. If revenue lands near forecasts but expenses run hotter, the earnings figure could fall short even in a quarter that looks healthy on the surface.
Without fresh formal guidance to anchor expectations, the consensus numbers effectively serve as the bar, and it is a demanding one. The most useful evidence in the release will be the mix of growth. Advertising strength tends to be more volatile and more exposed to the economic cycle, while affiliate and distribution fees are steadier and more predictable. A beat powered largely by advertising would be welcome but could raise questions about durability. A beat underpinned by resilient distribution revenue alongside contained costs would make the case that Fox's earnings power has stepped up structurally rather than temporarily. Comments on cost trends in the sports and news operations, where content spending is the largest lever, will matter as much as the headline figures.
The mood around the stock has shifted markedly. Sentiment readings have climbed to solidly bullish territory from a barely positive level ahead of the prior report, and the market has backed that optimism with real money. Shares have gained about 10.7% since the last earnings release while the S&P 500 slipped 1.3%, a 12-point outperformance. That rally means investors are no longer approaching Fox with skepticism. Expectations have moved up alongside the share price, which narrows the margin for a merely adequate quarter.
The chart reflects a stock consolidating gains rather than chasing new highs. At $59.46, shares sit comfortably above their 200-day moving average of $56.19, a sign the longer-term trend remains constructive. They are also trading in the upper half of their post-earnings range between $53.01 and $62.93, though still more than 5% below the top of that band, so a breakout is not imminent. Notably, the current range is far tighter than the swing from $44.08 to $61.96 in the prior quarter, suggesting investors have settled on a higher valuation and are waiting for confirmation.
That confirmation hinges on operating leverage. If Fox can show that roughly 15% revenue growth translates into something close to 40% earnings growth, with costs holding steady and distribution revenue providing a firm base, the recent rerating looks justified and the stock has room to challenge its range high. If the profit expansion proves thinner than hoped, the bullish shift in sentiment leaves little cushion, and the market may decide the easy gains have already been made.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 10 hours | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-13 | |
| Oct-12 | |
| Oct-02 | |
| Sep-30 | |
| Sep-24 | |
| Sep-23 | |
| Sep-18 | |
| Sep-14 | |
| Sep-03 | |
| Aug-31 |
