Check Point's Rally Meets Its Trough Quarter As Q4 Rebound Story Faces Proof
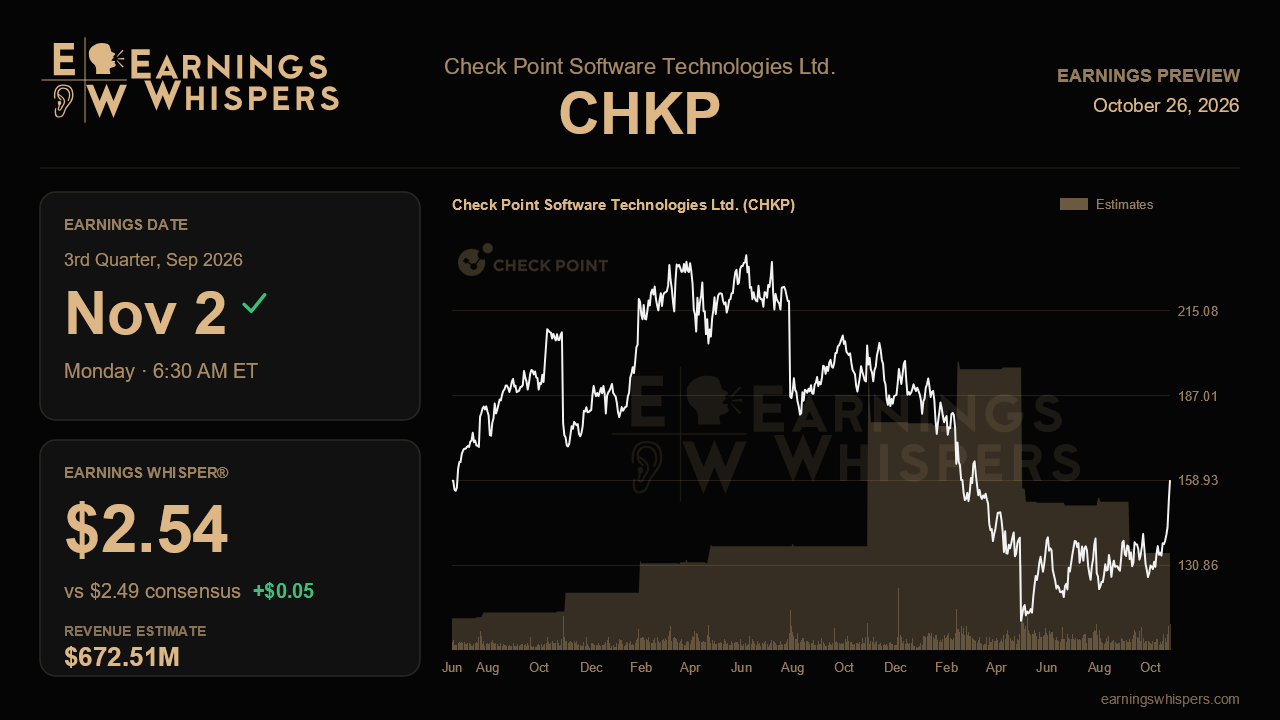
Check Point Software heads into its third-quarter report with an unusual mismatch between the business and the stock. Management told investors last quarter that this period would be the low point, with firewall and appliance sales still shrinking under the weight of a self-inflicted sales reorganization. The market has since bid the shares up more than 29%, roughly 26 percentage points ahead of the S&P 500. So the question on November 2 is less about whether the trough arrives on schedule and more about whether Check Point can show that the recovery it promised for the fourth quarter is real.
The Street is looking for non-GAAP earnings of $2.49 a share on revenue of about $672.5 million, which would be essentially flat with the year-ago quarter and a slight 0.7% decline. Management guided to $2.42 to $2.53 in earnings and an unusually wide $600 million to $685 million in revenue. Consensus therefore sits in the upper half of the earnings range and near the top of the revenue range. That is notable because estimates have already come down meaningfully since the guidance was issued, when analysts were still modeling $2.58 and nearly $699 million. The whisper number of $2.54 sits a nickel above consensus and just above the top of management's range, suggesting traders expect the company's habit of conservative guidance to hold, though the gap is modest.
The heart of this report is the split between Check Point's two businesses. Subscription revenue accelerated to 12% growth last quarter, and the emerging portfolio of email security, exposure management and AI security kept growing ARR above 40%. Product revenue, meanwhile, fell 14%, and management guided to a similar decline this quarter. A product number that is no worse than that, paired with subscription growth holding in the low double digits, would validate the idea that the reorganization damage has been contained. A deeper product slide, or any cooling in subscriptions, would undercut the one engine that has been carrying the story. Calculated billings, which slid from 20% growth a year ago to roughly flat, deserve close attention as the best forward signal of whether demand is stabilizing.
The fourth quarter looms over everything. The reaffirmed full-year guidance of $2.77 billion to $2.85 billion, already trimmed in the spring, implies a record quarter of about $800 million and roughly 6.5% growth, built partly on deals pushed out of the third quarter. That makes the company's commentary on pipeline conversion and those slipped deals more important than the headline numbers. Another reaffirmation with confident detail would support the rebound narrative. Any narrowing toward the low end, or vague language about deal timing, would signal that the back-end loading was too ambitious. Gross margin is a secondary swing factor, having dipped to 87% on higher memory costs, and investors will want to know whether component inflation is also making customers hesitate on hardware purchases.
Sentiment has shifted from clearly bearish heading into last quarter to nearly neutral now, and the stock is trading at $159, well above its 200-day average near $142 and within a dollar of its post-earnings high of $159.84. That puts the shares right at the edge of a breakout, but it also means some of the recovery is already priced in. The early payoff from roughly 300 new sales hires, the AI Network Firewall launch and an expanded $2 billion buyback are supportive, though the hiring benefit is explicitly a 2027 story.
Ultimately, this report will be judged on credibility. If Check Point confirms that the third quarter marked the bottom and lays out a convincing path to that record fourth quarter, the rally has a foundation. If the rebound starts to drift further out, a stock pressing against its highs leaves little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 5 hours | |
| 7 hours | |
| Oct-14 | |
| Oct-01 | |
| Sep-14 | |
| Sep-11 | |
| Sep-11 | |
| Sep-11 | |
| Sep-10 | |
| Sep-02 | |
| Aug-03 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-27 |
