Check Point Matches Consensus But Misses The Whisper As Q4 Rebound Slips And Guidance Is Cut Again
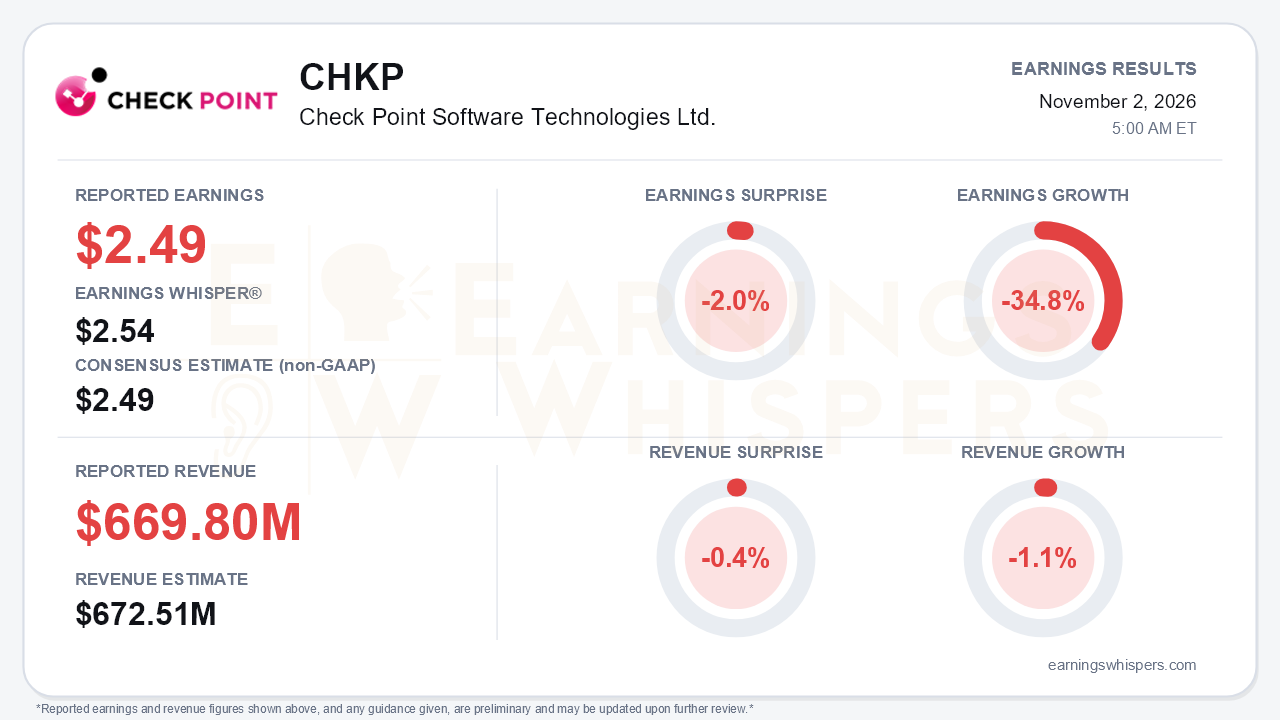
Check Point Software reported third-quarter non-GAAP earnings of $2.49 per share, exactly matching consensus but falling 2.0% short of the $2.54 Earnings Whisper number. Revenue of $669.8 million missed the $672.51 million consensus by 0.4%. Earnings fell 34.8% year over year and revenue slipped 1.1%. Management called the quarter in line and declared it the revenue trough. The more consequential news came on the call, where the company walked back the fourth-quarter product rebound it had promised in July and cut full-year guidance again. That is the central tension: a stock that rallied hard toward a recovery now has to absorb a recovery pushed further out.
The steep year-over-year EPS decline is mostly an artifact. Last year's third quarter included a tax-settlement benefit of about $1.47 per share, and excluding it, non-GAAP EPS rose 1%. Even so, the quality of that modest gain deserves scrutiny. Diluted shares fell from 109.5 million to 101.9 million on continued buybacks, with $325 million repurchased in the quarter. Financial income rose to $41.5 million from $28.7 million, helped by proceeds from the $2 billion convertible offering. R&D expense was reduced by a $25 million credit under Israel's new R&D incentive law. Even with that help, non-GAAP operating income fell to $250.7 million from $281.9 million. Operating performance shrank; financial engineering and a new subsidy held EPS flat.
The revenue mix explains the pressure. Security subscriptions grew 11% to $339 million and now exceed half of revenue. Products and licenses, however, fell to $105.5 million from $130.4 million, and software updates and maintenance declined to $225.7 million from $241.7 million. Subscription growth has eased from 12% in the second quarter, and management guided to further deceleration in the fourth. Calculated billings fell 5%. Non-GAAP operating margin has stepped down every quarter, from 41% in the fourth quarter of 2025 to 40%, 39% and now 37.4%. Memory costs are holding gross margin near 87%, and management expects that pressure to persist into 2027.
Guidance carries the heaviest weight. Fourth-quarter revenue is now guided at $720-770 million, roughly flat year over year. In July, management had implied about 6.5% growth and said product would be "back to growth." The reason given is that several large refresh deals with existing customers slipped into 2027. Full-year revenue guidance has now fallen from $2.83-2.95 billion in February, to $2.77-2.85 billion, to $2.732-2.782 billion. Adjusted free cash flow guidance moved to $1.136-1.166 billion, and the EPS midpoint dipped to $10.31 from $10.45. Management's tone shifted from "significant improvement" to "cautiously optimistic" about a "more gradual" recovery, and the CEO acknowledged the recovery "is taking longer than anticipated."
The growth story is not broken, and the call preserved credible pieces of it. Emerging technologies are compounding: email, CTEM and AI security ARR grew more than 38%, and their calculated billings accelerated to 47% from 35%. Email security ARR passed $200 million, hitting the year's target. New wins include an eight-figure deal with a Fortune 200 energy company and a seven-figure AI security contract covering more than 80,000 employees. Management framed 2027 subscription revenue above $1.5 billion and has added dozens of sellers. A 12-20% firewall price increase took effect October 4. The CFO sized it at up to roughly three points of growth, though historically slightly less than half has been realized. Bears have legitimate ammunition, however:
- Raising prices into soft appliance demand could further delay refreshes.
- Up to $50 million of incremental shekel-driven opex is flagged for 2027.
- Analysts pressed on a "legacy" perception and on difficulty winning new logos.
The market setup is more complicated than an in-line print implies. Shares opened at $123.03 after the July report, bottomed at $122.16 on August 3, and climbed 23.6% to $152.11 by October 30. That leaves them 7.7% above the 200-day moving average and about 6% below the October 26 high of $162.44. Price and AVWAP trend readings were positive heading in. Investor sentiment remained negative but improved meaningfully, moving from -0.22 to -0.09. In short, expectations had been rebuilding toward exactly the fourth-quarter rebound that management just deferred.
The bottom line is that Check Point delivered a clean-looking quarter built on buybacks, interest income and an R&D subsidy, while the core firewall franchise, billings and margins kept weakening. The fast-growing emerging-tech portfolio and the price increase give the recovery thesis real support, but the recovery now looks like a 2027 story rather than a fourth-quarter one. The February 10 Capital Markets Day becomes the next major test of whether management can rebuild credibility after repeated guidance cuts.
Read our earnings preview for Check Point Software Technologies Ltd.: https://www.earningswhispers.com/article/CHKP/21343
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours | |
| 7 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| 9 hours | |
| 10 hours | |
| Oct-29 | |
| Oct-26 | |
| Oct-26 | |
| Oct-14 | |
| Oct-01 |
