Tempus AI Faces A Higher Bar On Profitability After A 46% Post-Earnings Rally
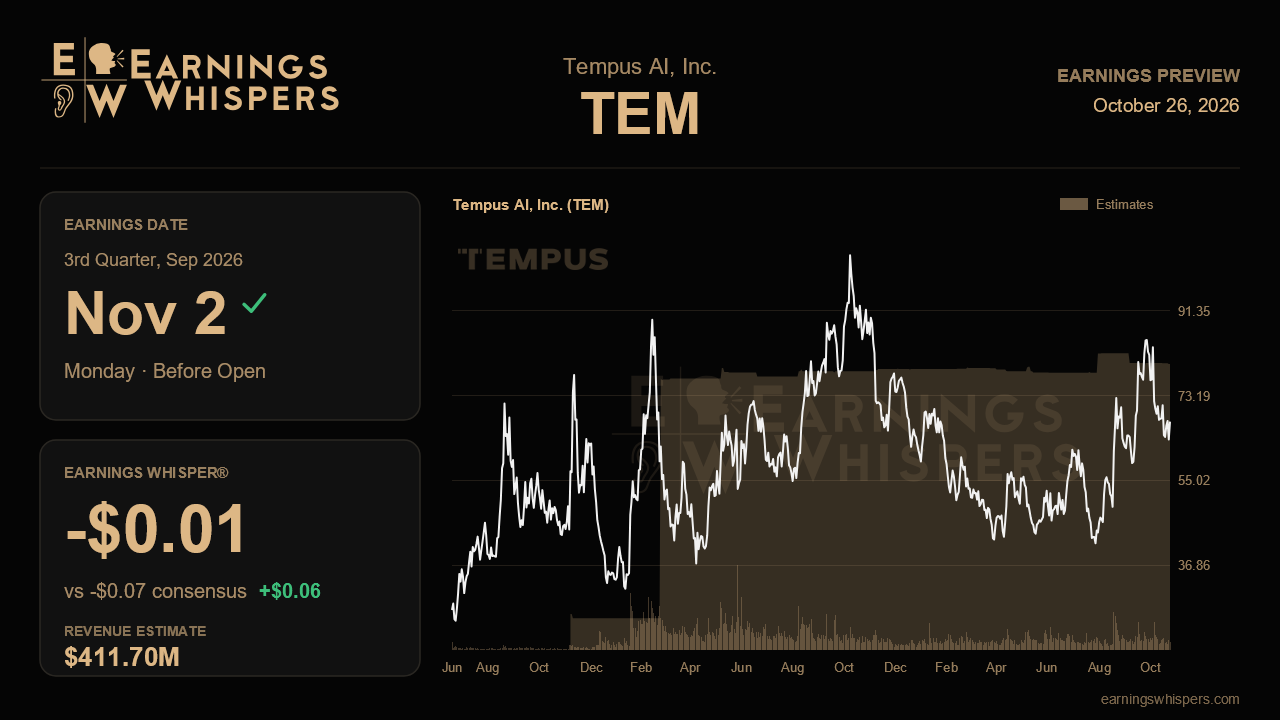
Three months ago Tempus AI posted its first quarter of GAAP net income, raised its full-year outlook for the second time, and agreed to buy Personalis to push deeper into minimal residual disease testing. The market loved it. Shares have climbed about 46% since that report while the S&P 500 barely moved. The third-quarter release, due before the open on November 2, now has to show that the profitability inflection was a durable turn and not a one-quarter event, and it has to do so with expectations that have quietly moved higher.
Wall Street is looking for revenue of about $411.7 million, up roughly 23% from $334.2 million a year ago and a solid sequential step from the $382.5 million reported last quarter. Consensus calls for a non-GAAP loss of 7 cents a share, a sharp narrowing from the 31-cent loss a year earlier. The whisper number sits at a loss of just a penny, meaningfully better than consensus. That gap matters for a company hovering near breakeven: it suggests the real bar is something close to profitability, and a print merely in line with the published estimate could feel like a letdown.
Management's own framing reinforces that bar. Full-year revenue guidance stands at $1.595 billion to $1.605 billion, and the Street's $1.59 billion estimate sits just below the bottom of that range. In other words, analysts are not yet fully underwriting the company's outlook, which leaves room for upside if the quarter lands cleanly. Tempus also lifted its adjusted EBITDA target to roughly $65 million for the year and committed to positive free cash flow by year-end. Having burned more than $70 million in operating cash in the first quarter before improving to a $7.5 million outflow in the second, the company needs to show another clear step toward cash generation for that promise to remain credible.
The operating details will tell the more important story. Headline growth slowed last quarter to 22% from 36% as the Ambry acquisition rolled into the comparison base and hereditary testing grew only 5% against an unusually strong year-ago period. Management called that deceleration comp-driven, and the evidence for that claim lies beneath the surface: core oncology unit growth, which accelerated to 31%, should stay strong, and the algorithm attach rate, which rose to 45% from 40%, should keep climbing. Data and services is the other pillar. Insights revenue grew 36% with roughly $200 million of bookings, aided by new deals with BioNTech and others, but the broader data line cooled to 28% from about 40%. Another quarter of healthy bookings would ease concerns that pharma demand is merely lumpy. MRD volumes, which have risen from about 4,700 tests to 9,000 over two quarters, are a key proof point for the Personalis thesis.
The risk ledger has shifted too. The Personalis transaction carries a $46 stock floor, which looked uncomfortable when shares traded below it; with the stock now near $68, that worry has largely faded, though investors will want clarity on timing and financing. The whole-genome ramp and its possible cannibalization of exome work remain early questions. Sentiment is less bearish than it was before the last report, and the stock sits well above its 200-day moving average, though still about 24% below its post-earnings high of $89.09, a sign of how volatile the climb has been.
The central issue is whether Tempus can pair roughly 23% growth with a near-breakeven bottom line and visible progress toward free cash flow. If it does, and reaffirms or nudges up guidance, the improving narrative stays intact. If profitability slips back or bookings soften, a stock that has already rewarded the story could give back some of its gains.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| 10 hours | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-19 | |
| Oct-15 | |
| Oct-13 | |
| Oct-13 | |
| Oct-09 | |
| Oct-07 | |
| Oct-06 | |
| Oct-01 | |
| Oct-01 | |
| Sep-28 |
