Tempus AI Crosses Into Non-GAAP Profit As EBITDA Inflects, But An In-Line Top Line And A Barely Moved Guide Temper The Beat
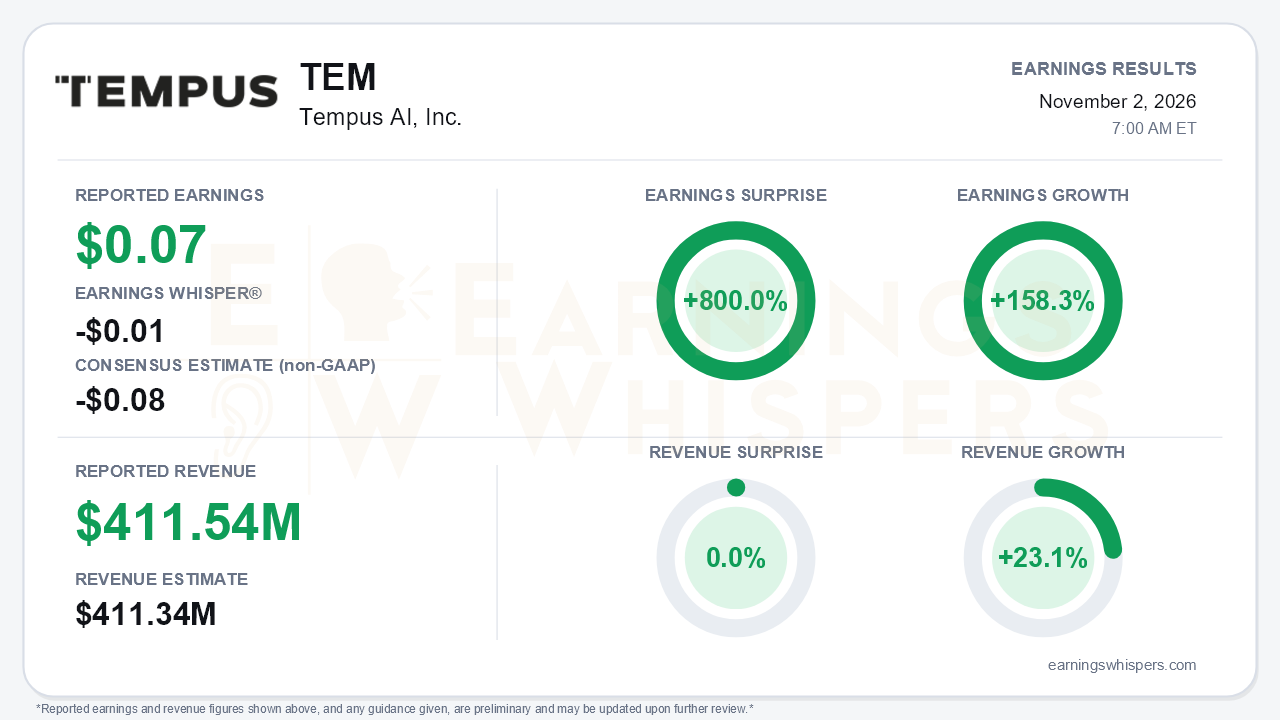
Tempus AI delivered the profitability inflection investors have waited for, but not the top-line upside that usually accompanies a beat of this size. The company reported non-GAAP earnings of $0.07 per share, against a consensus estimate of a $0.08 loss and an Earnings Whisper number of a $0.01 loss. That is an 800.0% surprise and 158.3% growth from the $0.11 loss a year ago. Revenue of $411.54 million rose 23.1% year over year but only matched the $411.34 million consensus. That is the central tension: the earnings story improved sharply, while the revenue story mostly met expectations.
The quality of the beat deserves scrutiny, though it holds up better than the GAAP line suggests. The GAAP net loss narrowed to $14.9 million from $80.0 million. However, that figure was flattered by $42.8 million of unrealized gains on marketable securities, and GAAP operating loss improved only modestly, to $56.9 million from $61.0 million. Stock-based compensation rose to $48.1 million from $34.0 million. The non-GAAP figures do strip out the fair-value gains, so the swing to $13.4 million of non-GAAP net income reflects operating leverage rather than mark-to-market noise. That leverage was real. Gross margin expanded to 64.8% from 62.8%, and Data & Applications gross margin rose to 71.5% from 68.5%. Adjusted EBITDA reached $25.6 million, up from $8 million in Q2 and a $3 million loss in Q1, which management characterized as having "made the turn." Cash burn also improved, with nine-month operating cash use falling to $71.6 million from $181.3 million.
Beneath the headline, growth was uneven. Total growth of 23% edged up from 22% in Q2 but sits well below Q1's 36%, now that the Ambry acquisition comparisons have lapped. Oncology remains the engine:
- Unit growth accelerated to 32%, from 31% in Q2 and 28% in Q1.
- Oncology revenue grew 28% to $172.6 million.
- MRD volume reached roughly 12,000 tests, up 300%.
Hereditary was the drag, with revenue up just 3%. Management pointed to unit growth recovering to low double digits in September and October. Data & Applications grew 33%, faster than Q2's 28%. Yet Insights, the core data-licensing line, slowed to 29% from 36% in Q2 and 44% in Q1, a three-quarter deceleration bears will not ignore. Related-party revenue from Pathos also accounted for $22.1 million of the segment's $108.1 million. In addition, Tempus accepted $17.5 million of Pathos preferred stock in lieu of receivables this year, a detail that complicates the read on data revenue quality.
The forward catalysts are substantial. Year-to-date data bookings now exceed $550 million, driven by:
- a BMS license worth up to $137.5 million over five years;
- a $55 million Alzheimer's dataset deal, paid by Pathos, that is the company's first large non-oncology license;
- a Merck/Moderna collaboration supporting potential commercialization of their individualized neoantigen therapy.
FDA-based pricing for the XT tumor-only test takes effect January 1, 2027. Management cited a roughly $80 million revenue uplift, slightly trimmed from about $85 million last quarter. The risks are equally concrete. The Personalis deal, expected to close late in Q4, brings MRD tests that currently lose money per test. Full MRD sales expansion hinges on reimbursement that may not arrive until mid-2027. Proposed lab fee schedule cuts were also raised on the call, though management sees minimal impact on hereditary pricing.
Guidance is where the market setup gets more complicated than the surprise implies. Tempus described its outlook as an increase, but it effectively narrowed the range. The low end rose to $1.60 billion, the top stayed at $1.605 billion, and the midpoint moved up only about $2.5 million. Full-year adjusted EBITDA guidance held at roughly $65 million despite the Q3 outperformance. With $30.8 million earned through nine months, that implies about $34 million in Q4, continued progress but not a raise. Management's policy of reinvesting roughly two-thirds of incremental gross profit explicitly caps near-term margin drop-through.
Investors entered the report with sentiment still negative but improving, moving to -0.33 from -0.41 at the prior report. That is a modest shift that hardly signals euphoria. Price action was far more emphatic. Shares rose 56.2% from the $46.24 open after the July report to $72.22 and sit about 27% above the $57 200-day moving average. The stock nonetheless entered earnings nearly 19% below its September 29 high of $89.09, meaning it had already given back a sizable portion of its run. The Earnings Whispers trend signals are uniformly positive, consistent with that improved but cooling trajectory.
The bottom line is that Tempus produced a genuine profitability inflection, accelerating oncology volume, and a deepening pharma data franchise, which together form a credible growth story. However, revenue only matched consensus, Insights growth keeps slowing, the guidance change was more of a narrowing than a raise, and Personalis will add cash burn. After a 56% move since the last report, the burden now shifts to the 2027 pricing uplift and MRD reimbursement turning those bookings into accelerating revenue.
Read our earnings preview for Tempus AI, Inc.: https://www.earningswhispers.com/article/TEM/21357
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 9 hours | |
| 10 hours | |
| Oct-31 | |
| Oct-29 | |
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-23 |
