Backblaze Must Prove Its AI Pivot Is Real After A 59% Post-Earnings Collapse
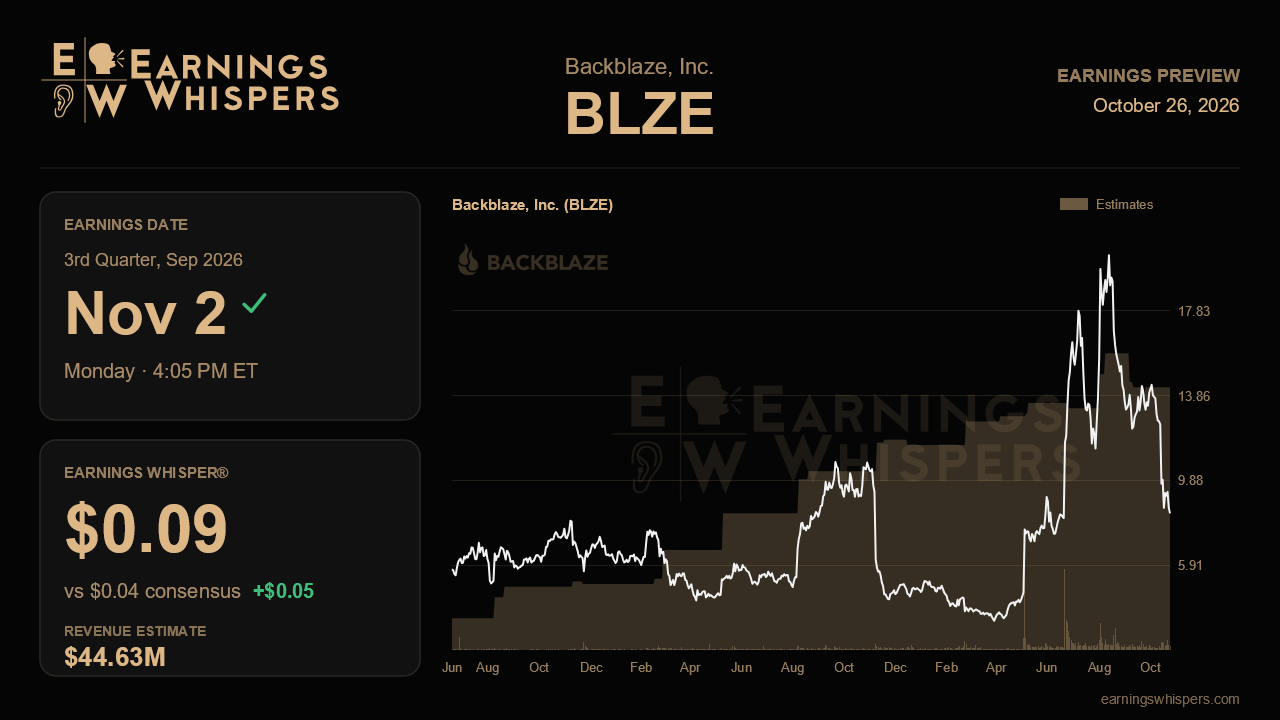
Backblaze delivered its best quarter in years last time out, then watched its stock lose more than half its value. That disconnect makes the November 2 report, due after the close, unusually important. Management called the second quarter pivotal. It cited a $335 million, five-plus-year CoreWeave agreement, accelerating growth in its B2 cloud storage business and a second consecutive guidance raise. The market has since treated those claims with deep skepticism, and this report is the first real chance to show the inflection is more than a one-quarter event.
The bar on the headline numbers is clear. Analysts expect revenue of $44.6 million, up about 20% from a year ago. That would extend the acceleration from 12% growth in the first quarter and 18% in the second. The estimate sits right at the midpoint of management's $44.4 million to $44.8 million guidance, so the Street has moved up to the company's outlook rather than beyond it. On earnings, consensus calls for a non-GAAP profit of 4 cents a share, compared with a 3-cent loss last quarter and a 7-cent loss a year ago. The Earnings Whisper of 9 cents is meaningfully higher. That suggests some investors expect profitability to beat forecasts again, after adjusted EBITDA margin came in 700 basis points above guidance last quarter.
The operating details will matter more than the top line. Backblaze beat its revenue range by $2.5 million last quarter, so landing only inside the range now could read as a slowdown. B2 growth of 34% was the strongest in seven quarters. Roughly eight points of that came from the May 1 price increase, which caused less churn than management had feared. Keeping B2 growth in the mid-30s, with no delayed churn showing up, would support management's early view that B2 can grow more than 40% in 2027. The count of customers paying $50,000 or more a year, which rose 57% to 235, is another useful gauge of whether the revamped sales team keeps producing larger deals. Net revenue retention slipped slightly to 113%. Any further erosion there would challenge the idea that existing customers are expanding as fast as new ones are signing.
The costs of growth are the other half of the story. Management guided full-year adjusted EBITDA margin to 27% to 29% and expects capital spending to reach 55% to 65% of revenue this year, funded largely through capital leases. It also warned that gross margin, 63% last quarter, could fall a few hundred basis points as depreciation on capacity for committed deals arrives before the revenue. Investors will want to know how big that dip is and how long it lasts. The CoreWeave contract also brings $22 million of warrant-related contra-revenue and more customer concentration, and its minimum commitment does not kick in until around mid-2027. Updates on remaining performance obligations, which jumped by about $320 million last quarter, and on the new capital-light managed storage model would help show whether the backlog is turning into revenue on schedule.
Sentiment has clearly soured. Bearish readings deepened to about 43% from roughly 18% before the last report. The stock trades at $8.34, just above its post-earnings low of $8.32 and below its 200-day moving average of $9.09. That is a long way from the $23.99 peak reached after the last report. In effect, the market has priced in serious doubt about the durability, funding or profitability of the AI-driven growth.
That makes the central question simple. Can Backblaze show that its big AI contracts are producing sustained B2 acceleration without margins and capital needs getting out of hand? Results at the high end of guidance, steady B2 growth, contained gross margin pressure and confirmation of the full-year targets would support the narrative management laid out last quarter. A merely in-line quarter with fuzzy answers on spending and the ramp would likely keep the skeptics in charge.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-12 | |
| Oct-01 | |
| Sep-29 | |
| Sep-14 | |
| Sep-09 | |
| Aug-19 | |
| Aug-18 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-31 | |
| Jul-30 | |
| Jul-23 |
