Boise Cascade's Hardie Transition Meets Plywood Strength In A Guided-Down Quarter
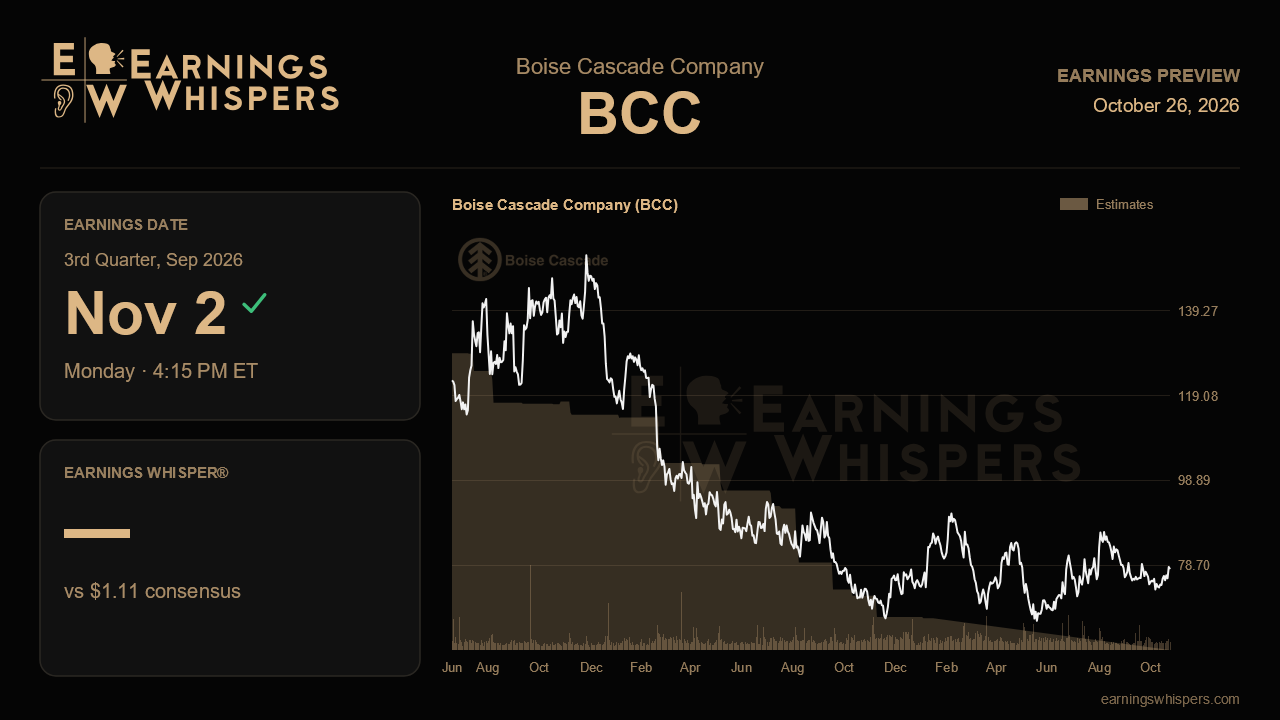
Boise Cascade heads into its third-quarter report with two stories pulling in opposite directions. Its manufacturing arm is enjoying its best pricing backdrop in more than a year, while its distribution business is deliberately absorbing a costly changeover to become James Hardie's sole nationwide partner. Management told investors three months ago that the quarter would be softer than the second. The question now is whether the step-down lands where the company said it would, and whether the long-term payoff from the Hardie deal starts to look tangible.
The Street expects earnings of $1.11 a share, which would be up about 91% from the $0.58 earned a year ago, yet well below the $1.63 posted last quarter. Both points matter. The year-over-year jump reflects how depressed wood products profits were last fall, when segment EBITDA was just $14.5 million and plywood sold for about $325 per thousand square feet. The sequential decline is built into management's own guidance, which called for Building Materials Distribution EBITDA of $53 million to $68 million versus $85.6 million in the second quarter, and Wood Products EBITDA of $42 million to $57 million against $52.4 million. Consensus appears to sit roughly in line with the middle of that framework rather than anticipating upside, so the bar is realistic but not generous.
The distribution segment is the bigger swing factor. Management attributed about two-thirds of the expected BMD decline to the supplier transition, as legacy decking and siding inventory is wound down ahead of the Hardie, AZEK and TimberTech lineup. Decking accounts for roughly 90% of the affected revenue, so commentary on how quickly that business is being replaced will be critical. A result at or above the top of the EBITDA range, with gross margin holding near the upper end of the 14.0% to 14.75% guide, would suggest the friction is manageable. A figure near the bottom, or signs that freight and fuel costs are widening the hit, would raise doubts about how deep and how long this transition really runs. Since Hardie's financial support only began on October 1, the fourth-quarter outlook may be more revealing than the quarter just ended. Management already warned that normal conditions would not return by early 2027, so any change to that timeline will register.
In Wood Products, the task is to show that the pricing inflection is durable while volumes cool. Plywood reached $393 last quarter, helped by sharply lower Brazilian imports and new tariffs, and the first engineered wood price increase in several quarters, about 3%, was supposed to phase in through early next year. Management also flagged that second-quarter EWP volumes were pulled forward ahead of that hike, and guided to a mid-single-digit volume decline as builders trim closings and dealers carry less inventory. Evidence that realized EWP prices are sticking despite weaker orders would validate last quarter's optimism. Slippage in plywood pricing or deeper volume erosion would challenge it.
The market has not been patient. Shares are down about 6% since the last report, trailing a flat S&P 500, and at $77.74 sit just above the 200-day moving average, in the lower half of a post-earnings range between roughly $72 and $88. Sentiment has improved modestly to 14.4% bullish from 9.1% a quarter ago, which hints that some investors see the guided dip as a buying opportunity rather than a warning.
Ultimately, this report is about credibility. If Boise Cascade lands within its guidance, demonstrates pricing traction in engineered wood, and offers a clearer roadmap for the Hardie ramp, the soft quarter can be framed as a planned investment. If the transition costs run hotter than promised while housing demand fades, the medium-term case becomes much harder to defend.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-20 | |
| Oct-08 | |
| Sep-24 | |
| Aug-07 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 | |
| Jul-30 | |
| Jul-21 | |
| Jun-18 | |
| May-04 | |
| May-04 | |
| Apr-30 |
