Allison Transmission Faces Seasonal Off-Highway Trough As Investors Test Its Guidance Raise
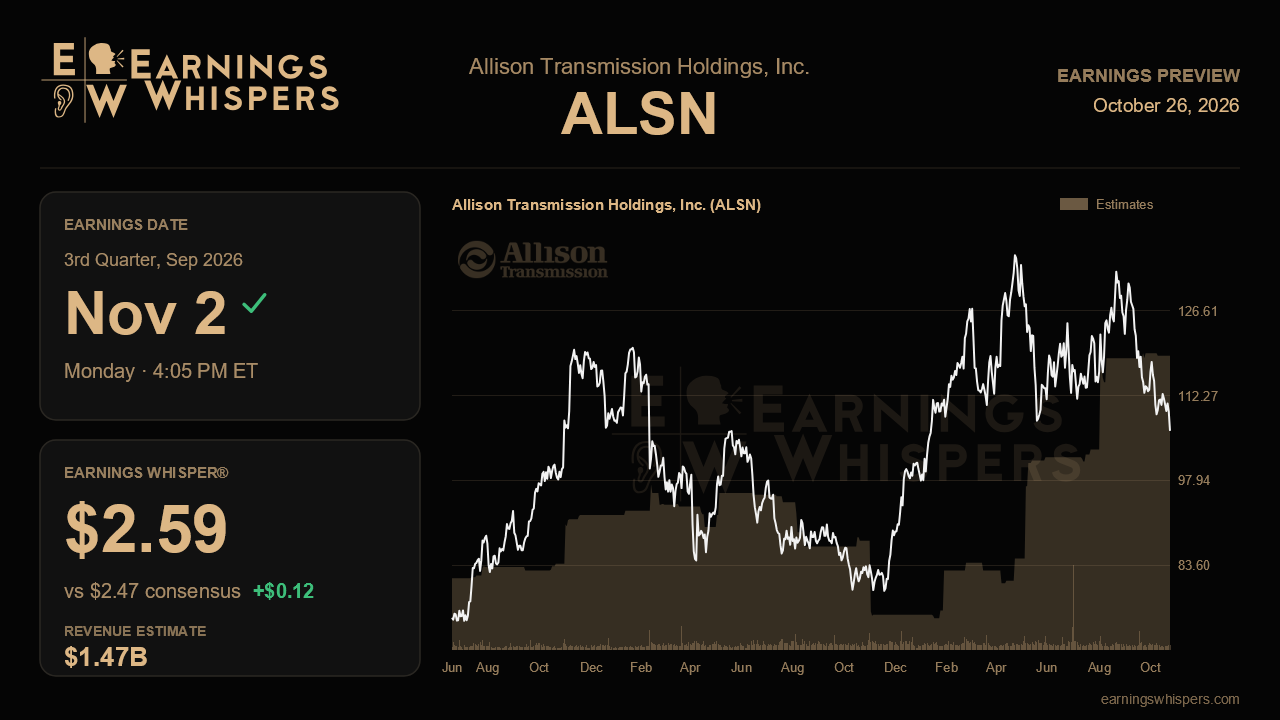
Allison Transmission heads into its third-quarter report with a curious disconnect. Three months ago management delivered its first guidance raise since closing the Dana off-highway acquisition, backed by record defense orders, record free cash flow and the first real pickup in North American medium-duty demand in a year. Yet the stock has fallen almost 10% since then while the S&P 500 went nowhere. The report after the close on November 2 has to show whether that optimism was justified or whether the market is right to discount it.
The Street expects earnings of $2.47 a share on revenue of about $1.47 billion. The year-over-year comparisons are flattering: revenue up roughly 112% and EPS up about 52%. But they mostly reflect the acquired off-highway business, which is absent from last year's $693 million base. The more useful comparison is sequential. Consensus implies a drop from the $1.57 billion and $2.73 a share posted in the second quarter. That is consistent with management's own warning that the third quarter is the off-highway unit's weakest, because European summer shutdowns idle roughly half of that business. The whisper number of $2.59 sits about 5% above consensus, so the informal bar is higher than the published one.
Guidance frames the setup. Management lifted full-year revenue to $5.8 billion to $6.0 billion from $5.575 billion to $5.925 billion. It also raised adjusted EBITDA to $1.465 billion to $1.575 billion, implying a margin of about 26%, and adjusted free cash flow to $745 million to $865 million. Consensus revenue of $5.79 billion sits just below the bottom of that range, so analysts have not fully bought the raise. A quarter that keeps the company on track for the midpoint would challenge that skepticism. A reaffirmation paired with soft commentary would confirm it.
The operating test centers on the legacy transmission business, which management credited for most of the raise. North American on-highway revenue jumped 15% sequentially in the second quarter after a long stretch of very soft conditions. The key question is whether that was a genuine turn or a one-quarter bounce. Defense matters too. It has grown at rates near or above 50% for three straight quarters, and the French PL-6T program, the $250 million BAE Hagglunds 4040MX order and the GDELS Eagle award add to the outlook. Most of those deliveries come later, so this quarter's evidence will show up in demand commentary rather than revenue. The EPA 2027 emissions proposal, which could trigger a pre-buy late this year, remains an open variable.
Margins are where the quarter could go wrong. Material costs ran up by a mid-teens percentage, with aluminum alone jumping about 25% in a single quarter. Management said price recovery lags by six to twelve months, so third-quarter transmission margins are likely to bear the full weight before relief arrives. Add lower seasonal off-highway volume, and gross margin could look uncomfortable even if revenue lands on target. Signs of early progress on the $120 million synergy plan, along with free cash flow helped by the lower capex budget, would ease that concern.
Sentiment has improved meaningfully from a near-neutral reading before the last report, even as the shares slid. At $106.32 the stock sits well below its 200-day average of $118.30 and barely above its post-earnings low of $105.10, a level that also held last quarter. That makes the area a support zone the report will either defend or break. In the end, the story hinges on one question: whether transmission demand and pricing are strong enough to absorb commodity inflation and the off-highway seasonal dip while keeping the raised full-year outlook intact.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 11 hours | |
| Oct-23 | |
| Oct-19 | |
| Oct-02 | |
| Aug-11 | |
| Aug-03 | |
| Aug-03 | |
| Jul-22 | |
| Jul-20 | |
| Jun-30 | |
| Jun-26 | |
| Jun-16 | |
| Jun-16 | |
| Jun-09 | |
| May-20 |
