Celanese Faces A Post-Windfall Test As Plant Closures And Raw Costs Squeeze Third Quarter
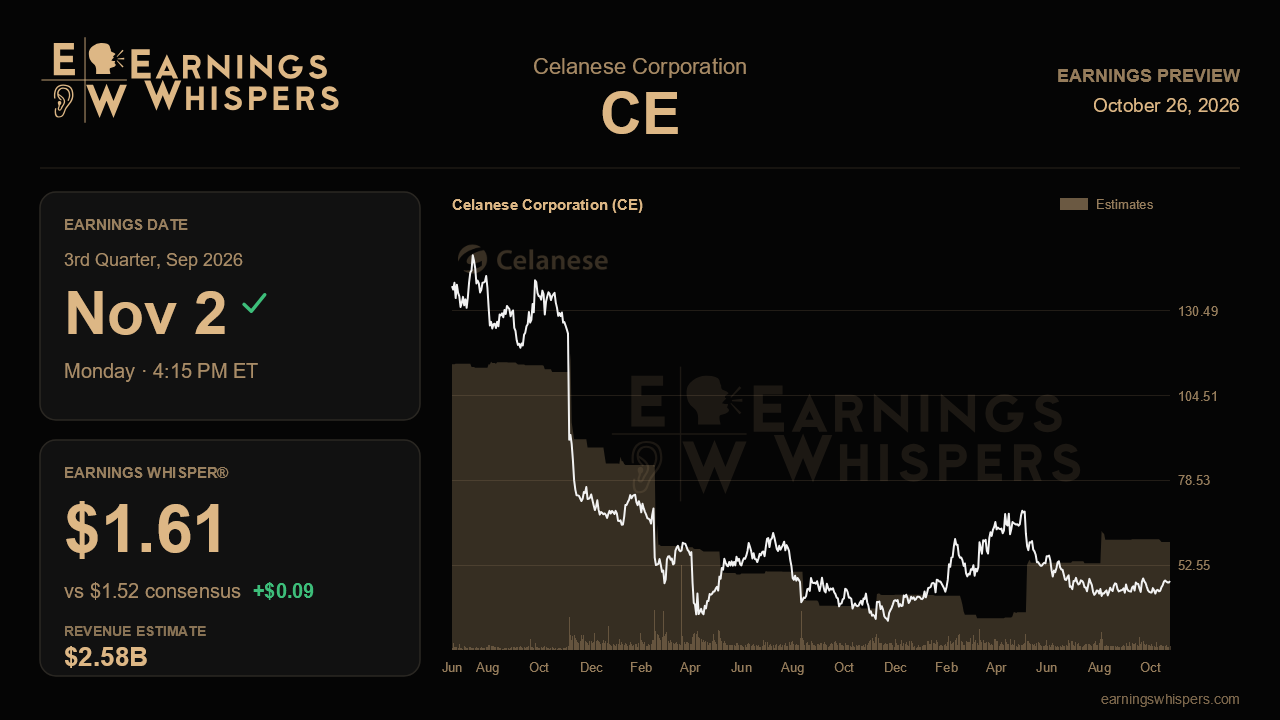
Celanese enters its third-quarter report with an unusual problem: it has to show that a weaker quarter is actually a healthy one. The second quarter was flattered by a supply-driven windfall in acetyls that management had openly planned for, and the company has already warned that the follow-up would step down on plant-closure timing, inventory absorption and a soft patch at its Ibn Sina joint venture. The question on November 2 is whether the drop looks like the scheduled, temporary dip management described or the start of something less tidy.
Wall Street expects earnings of $1.52 a share on revenue of about $2.58 billion. That would be a big retreat from the $2.45 earned last quarter, yet still roughly 13% above the year-ago $1.34 on revenue growth near 7%, which is respectable progress for a company working through soft auto and acetate tow markets. Management guided to $1.35 to $1.75, so consensus sits comfortably inside the range and a touch below its midpoint. Notably, the Street stood at $1.66 when that guidance landed, meaning analysts have since trimmed numbers toward the middle. The whisper number of $1.61 sits above both consensus and the midpoint, suggesting the informal bar is a bit higher than the published one.
The call last quarter offered a clear map of what should move the numbers. Accelerating the shutdown of acetate tow capacity pulled forward roughly $20 million of second-half absorption costs, and the equity income shortfall at Ibn Sina, about $10 million for the year, was expected to land mostly in this quarter. Those are mechanical items, and a result near guidance would validate the view that the step-down is about timing rather than demand. The more important swing factor is Engineered Materials. Management raised its framing to roughly 15% adjusted EBIT growth for the year, built on pricing secured late in the second quarter, while conceding that raw material inflation would pressure third-quarter margins. If pricing holds and margins compress only modestly from the second-quarter peak, the 15% target looks credible. A sharper squeeze, or flat volumes deteriorating further on auto builds, would challenge it.
In acetyls, the windfall is fading by design as customers find non-Middle East supply and Asian spreads have already reverted. What matters is how much of the new business won on reliability of supply sticks once the scramble ends, and how quickly Western margins normalize. Investors should also look for early signs that data center content, which management says now carries roughly three times the content opportunity, and medical drug delivery are contributing measurable sales rather than talking points. Cash is the other pillar: the company recast free cash flow as a sustainable $700 million to $800 million baseline, and with net debt targeted near $10 billion by year-end, any working-capital release and an update on the promised divestiture by year-end will carry weight.
Sentiment has swung from mildly bearish before the last report to mildly bullish now, and the stock has risen about 5% since then while the S&P 500 slipped, an outperformance of more than seven points. Context matters, though. Shares at $47.71 remain below the 200-day moving average near $51.50 and far beneath the prior quarter's high above $66, and they sit a few percent under the post-earnings high of $49.67 rather than pressing it. This is a recovery, not a vote of full confidence.
Ultimately, the report will be judged on whether the effectively reaffirmed $6 full-year earnings outlook survives the quarter intact. Hitting guidance with Engineered Materials pricing holding against raw costs, and cash generation tracking the new baseline, would confirm that the coiled-spring narrative is real. A miss driven by margins rather than the flagged timing items would suggest the second quarter was the high-water mark, not a preview.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-22 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Oct-09 | |
| Oct-09 | |
| Oct-02 | |
| Sep-24 | |
| Sep-21 | |
| Sep-16 | |
| Aug-31 | |
| Aug-25 | |
| Aug-21 | |
| Aug-17 |
