Celanese Tops EPS Estimates On Pricing And Cash, But Fading Acetyl Margins Cap The Upside
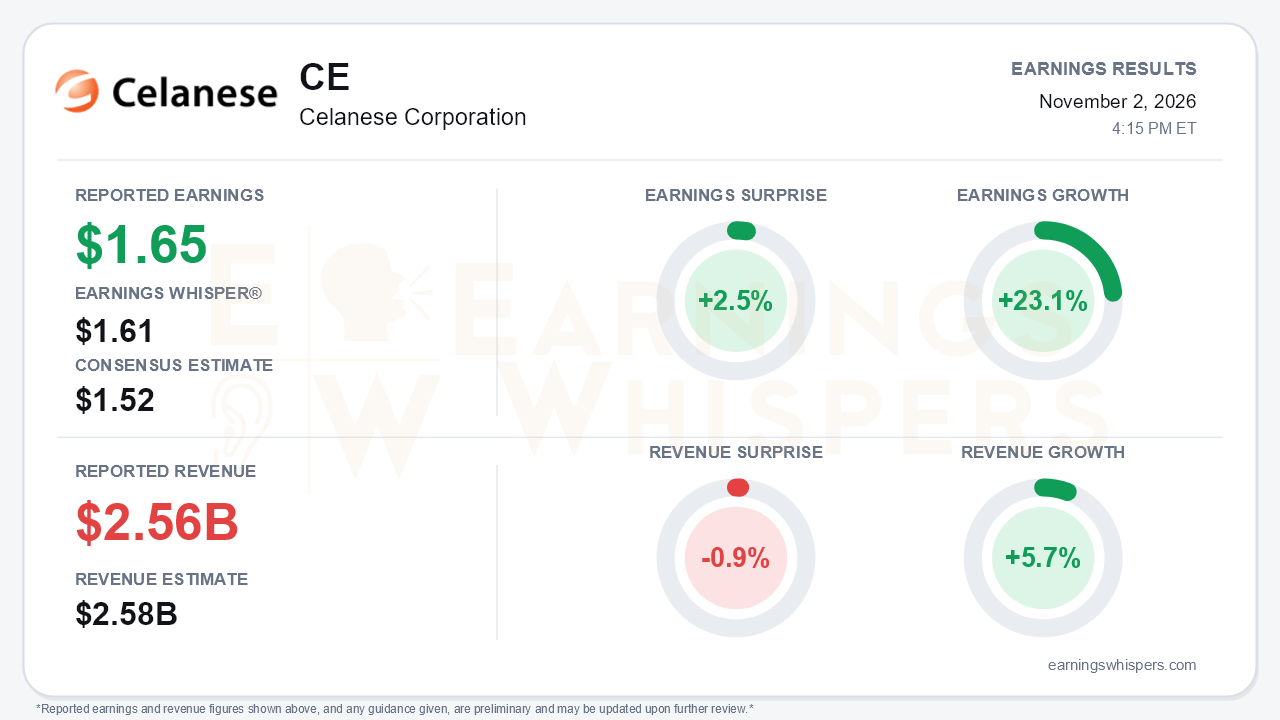
Celanese delivered a cleaner quarter than its recent history might suggest. The upside, however, came mostly from pricing and cash, not volume. Adjusted EPS of $1.65 beat the $1.52 consensus and edged past the $1.61 Earnings Whisper number, a 2.5% surprise. Earnings grew 23.1% from a year ago. Revenue of $2.556 billion rose 5.7% but missed the $2.58 billion consensus by 0.9%. That is the central tension. Celanese is converting a price-led recovery into real cash and deleveraging, while the conditions that inflated second-quarter acetyl profits are clearly unwinding. Growth also decelerated. Adjusted EPS fell from $2.45 in the second quarter. Year-over-year sales growth slowed from 9% in Q2 to 6%, and the year-over-year EPS gain was far narrower than the second quarter's jump from $1.43 to $2.45.
The quality of the beat deserves scrutiny. Company-wide, price contributed 10 points of year-over-year sales growth while volume subtracted 4. In the Acetyl Chain, sales rose 14% entirely on price, with volume flat, as management cited 'pricing favorability and incremental spot opportunities' offsetting 'modest demand softness.' Sequentially, that tailwind is already reversing. Acetyl price fell 5% and volume fell 4%. Segment adjusted EBIT dropped from $321 million to $236 million, and its margin slid from 24.2% to 19.5%. Engineered Materials held up better. Adjusted EBIT rose to $209 million from $200 million a year ago, despite a 7% sequential volume decline driven by automotive. On a GAAP basis, diluted EPS from continuing operations was $0.68, compared with a $12.39 loss a year earlier that was dominated by a $1.5 billion impairment. That loss-to-profit swing is real. Still, $87 million of exit and shutdown costs sit between the GAAP and adjusted figures.
Cash was the standout. Free cash flow of $461 million, aided by working-capital timing, lifted the year-to-date total to $604 million. Management raised its full-year free cash flow outlook to $750-$800 million. Net debt has fallen to $10.18 billion from $11.34 billion at year-end, and the company expects to exit 2026 near 4.7x net debt-to-operating EBITDA. That leverage is still heavy, but it is trending the right way. The Nutrinova stake sale to Mitsui for about $152 million moves divestiture proceeds toward roughly $650 million by year-end against a $1 billion target for 2027.
The call preserved a credible growth story in Engineered Materials while signaling new pressure in acetyls. Management now frames 2026 Engineered Materials EBITDA growth at about 20% excluding Micromax, up from earlier commentary. AI data-center electronics demand is still accelerating, with fourth-quarter orders holding at third-quarter levels. Three capacity projects in Asia and Europe remain on track to commercialize in the first half of 2027. The weaker side of the call:
- Acetyl margins are coming off through the fourth quarter.
- An unplanned outage at a key Chinese supplier will lower operating rates.
- The 2026 nylon inventory benefit was trimmed from $45 million to about $30 million on softer demand.
- A fresh wave of methanol and European energy inflation is expected to hit Engineered Materials in early 2027, forcing another round of price increases.
Management also declined to say whether 2026 acetyl earnings were 'over-earned.' Bears have legitimate ammunition there.
The guidance math reinforces that caution. Full-year adjusted EPS guidance of $6.00-$6.25, roughly in line with expectations, implies about $1.05-$1.30 in the fourth quarter. That is a meaningful step down from $1.65, though still well above the $0.67 earned a year ago. The 2027 free cash flow framework of $700-$800 million, supported by about $100 million of cost and interest savings, gives the stock a floor narrative that does not depend on acetyl spot conditions.
Investor sentiment shifted meaningfully, moving from mildly negative at -0.16 before the prior report to modestly positive at +0.21. Price action has been more restrained. Shares are up 5.9% since the post-August open, to $47.94, but remain 7.1% below the 200-day moving average of $51.58. Most of the Earnings Whispers trend readings are neutral, with AVWAP the notable positive. That pattern fits a stock that has stabilized but has not been re-rated. The December 9 investor event is the next clear catalyst for a longer-term earnings framework.
The bottom line is that Celanese beat on the metrics it controls best: pricing discipline, cost actions, and cash conversion. The headline nonetheless masks decelerating growth and an acetyl profit peak that is visibly fading. Deleveraging and Engineered Materials growth make the story sturdier than a year ago, but improving sentiment is running ahead of a stock that still trades below its long-term trend.
Read our earnings preview for Celanese Corporation: https://www.earningswhispers.com/article/CE/21376
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Oct-09 | |
| Oct-09 | |
| Oct-02 |
