Calix Needs Its Software Surge To Outrun A Memory-Driven Margin Trough
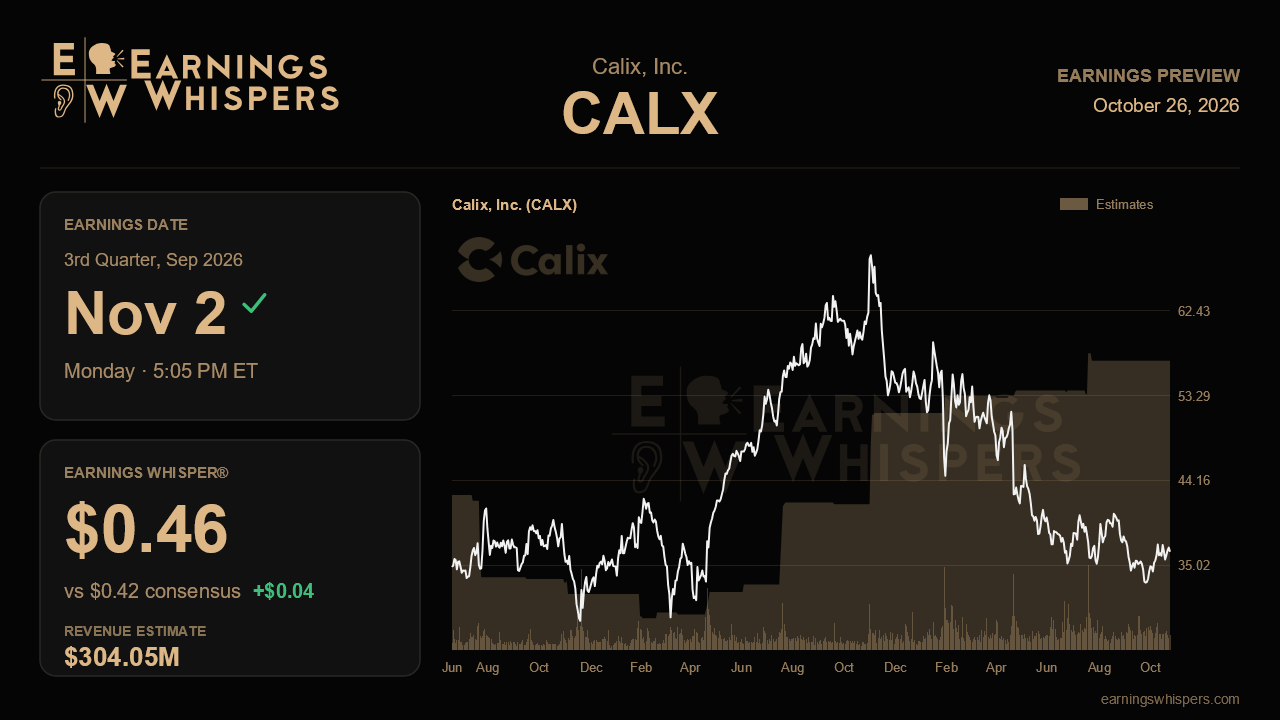
Calix heads into its third-quarter report with two stories pulling in opposite directions. Its AI-native software platform finally started paying off last quarter, but soaring memory prices are squeezing hardware margins. Management has called this quarter the bottom for appliance profitability. That makes Monday's release, due after the close on November 2, the first real test of whether the software story can carry the company through a cost shock it does not control.
The Street is looking for non-GAAP earnings of $0.42 a share on revenue of $304.1 million. That revenue figure would mean growth of roughly 14.6% from a year ago and about 4% from the second quarter. Both numbers sit almost exactly at the midpoint of management's guidance, which called for $0.37 to $0.45 a share on revenue of $301 million to $307 million. When that outlook came out, consensus earnings stood at $0.48, above the top of the range. Analysts have since cut their numbers into line, so the official bar now looks fair rather than stretched. The whisper number of $0.46 is the more demanding figure. It sits just above the high end of guidance, which suggests some investors expect Calix to beat its own conservative framing.
The margin line will set the tone. Total non-GAAP gross margin was guided to about 52% at the midpoint, down sharply from 57.2% in the first quarter and a record 58% in late 2025. That record had capped eight straight quarters of expansion. Part of the decline is deliberate. Calix restructured its memory surcharge so that it recovers higher costs without adding profit, and it now resets the surcharge monthly instead of quarterly. That protects gross profit dollars but dilutes the percentage. A result at or above 52%, plus a credible signal that appliance margin has stopped falling, would support the claim that this is a transient trough. If margin slips below guidance, or management hedges on whether the bottom has arrived, investors will start to worry that 2027 could be the harder year. Management itself has flagged that risk if hyperscaler spending keeps memory scarce.
The other half of the equation is software, and this is where the bullish case lives. Software and service revenue hit a record $50 million last quarter, its software margin jumped 810 basis points, and management took the unusual step of guiding that margin to another record this quarter. Contracts for CalixOne and its Agent Workforce Cloud tripled sequentially. Just as notably, the buyers broadened beyond early adopters to late-majority customers. To validate that shift, Calix needs continued growth in software revenue, a new software margin high, and remaining performance obligations that build on the $386 million record, especially the $162 million current portion that feeds near-term revenue. A stall in those backlog figures would undercut the claim that the platform migration has turned into a durable growth engine.
Demand on the hardware side deserves scrutiny too. Customers have been tightening inventory as costs rise, and the roughly 4% sequential growth implied by guidance is softer than Calix has often delivered. Any update on the full-year target, which was lifted to the high end of the 15% to 20% range, will show whether that cautious buying is spreading.
Sentiment has warmed noticeably. It has moved from heavily bearish before the last report to roughly neutral now. The stock has gained 3.6% since then, edging out the S&P 500, yet at $36.47 it remains well below its 200-day moving average near $43 and trades in a lower range than the prior quarter. That leaves room for a rerating if the margin trough holds. In the end, the report turns on one question: whether software momentum and backlog growth are strong enough that a temporary hardware margin hit looks like a passing cost problem rather than a structural one.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 8 hours | |
| Oct-26 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-12 | |
| Oct-08 | |
| Oct-07 | |
| Sep-29 | |
| Sep-28 | |
| Sep-24 | |
| Sep-17 | |
| Sep-01 |
