Healthpeak's Lab Recovery Faces A Proof Test As Shares Lag Its Guidance Raises
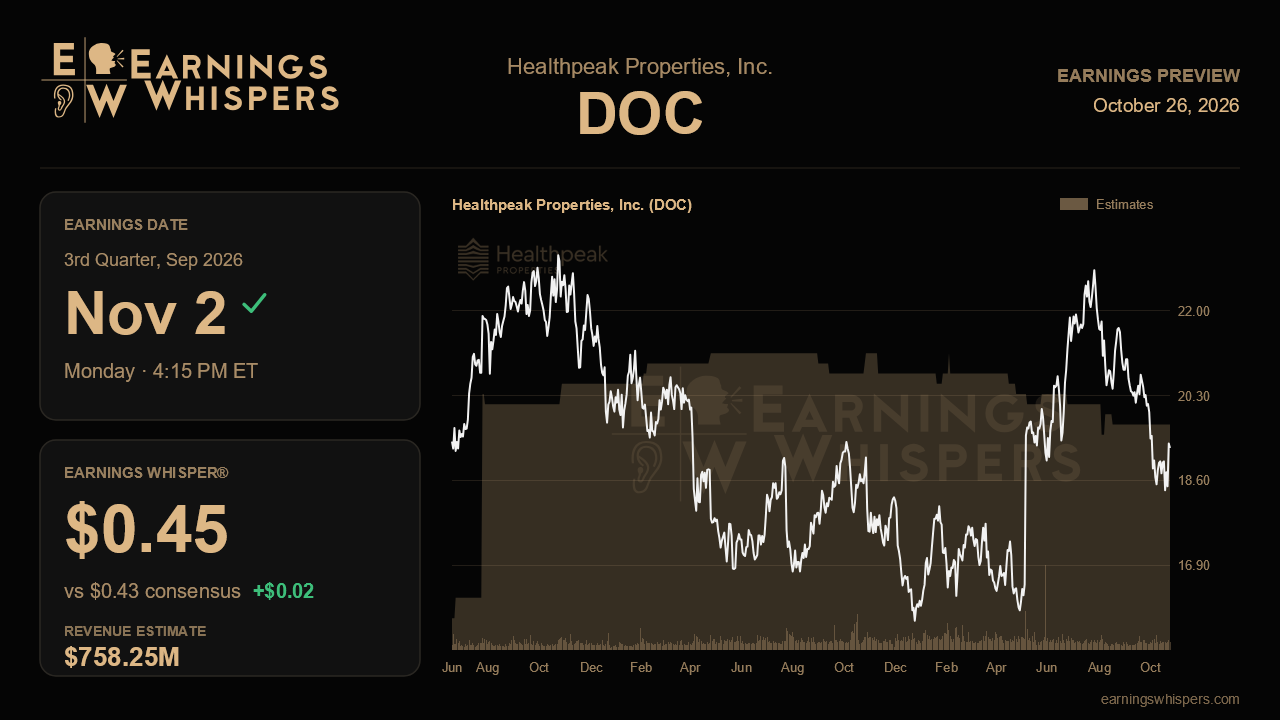
Healthpeak Properties enters its third-quarter report with an awkward mismatch. Management has raised full-year guidance twice in a row, lab occupancy is finally moving in the right direction, and the balance sheet is the strongest the company has described. Yet the stock has fallen 12.5% since the last report, about 10 percentage points worse than the S&P 500. The question for November 2 is whether the operating story keeps building or whether the market has spotted something the guidance does not yet show.
The Street expects $0.43 per share on revenue of about $758.3 million. That is a 6.5% decline from the year-ago $0.46, even as revenue grows 7.4%. The gap between top-line growth and per-share contraction largely tracks risks management has already flagged. In July, the company refinanced $650 million of notes that had carried roughly a 3.5% coupon at materially higher rates, an interest-cost headwind it said would weigh on the second half. Revenue is also expected to slip from last quarter's $771.6 million. That is worth watching given the $1 billion Brookfield outpatient recapitalization, in which Healthpeak kept a 51% stake in 5.6 million square feet. The Earnings Whisper sits at $0.45, two cents above consensus. That suggests the more informed bar is closer to repeating last quarter's result than to the softer published estimate.
On the full year, management now guides to funds from operations of $1.73 to $1.77 per share, up from $1.71 to $1.75. Consensus of $1.75 sits right at the midpoint, so the Street is giving management credit for the raise without pricing in another one. A third consecutive increase, even a modest one, would signal that the higher same-store midpoints are holding. A reaffirmation would be acceptable, though less convincing given the momentum language on the last call.
The lab portfolio is where the narrative will be tested hardest. Total lab occupancy climbed to 78.5% from 77.7% the prior quarter and 77.0% at year-end, already hitting the full-year improvement goal. Management backed that up with 480,000 square feet under letters of intent. It also said Torrey Pines is now 97% leased including LOIs, up from roughly 65% at year-end. Validation this quarter means those LOIs converting into signed leases and occupancy pushing visibly past 79%. It would also help to see evidence that management's new framing, in which lab shifts from building to buying and consolidating, is producing actual acquisitions. A stall in occupancy, LOIs slipping, or fresh weakness in Boston, where supply overhang remains heaviest, would undercut the idea that the pendulum has swung for good.
Senior housing has been the quieter engine. Last quarter delivered 260 basis points of same-store occupancy gains, 19% NOI growth, and a 200-basis-point lift to the segment's NOI midpoint. Sustaining double-digit NOI growth would support the raised guidance. In outpatient, cash releasing spreads eased to 5% from 5.4%, which management blamed on a single competitive Boston renewal. A rebound would confirm that explanation, while a second soft quarter would start to look like a trend.
Sentiment has cooled, with the bearish reading deepening to -0.302 from -0.225 heading into the prior report. At $19.25, shares sit barely above the 200-day moving average of $19.07. That is in the lower part of the $18.35 to $22.44 range traded since July and well off the high. Expectations are therefore subdued, which lowers the hurdle for a positive reaction if the fundamentals hold. Ultimately, this report turns on whether lab leasing momentum converts from signed intent into occupied, rent-paying space fast enough to offset higher interest costs. If it does, the gap between the operating story and the share price becomes hard to justify.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 10 hours | |
| Oct-14 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-01 | |
| Oct-01 | |
| Sep-24 | |
| Sep-14 | |
| Sep-08 | |
| Aug-17 | |
| Aug-05 | |
| Aug-04 |
