Corebridge Heads Into Its Last Pre-Merger Report Needing Institutional Strength To Offset Weak Alternatives
Corebridge Financial enters its third-quarter report in an unusual position: the most important event on its calendar is not the quarter itself but the year-end closing of its merger with Equitable. That makes this release less about any single number and more about whether the standalone business is arriving at the altar in the shape management described in August. Back then, the company paired a noticeably more confident tone with mixed hard numbers. Institutional markets and fee businesses were accelerating, while retail annuity sales and investment income tied to private equity were softening.
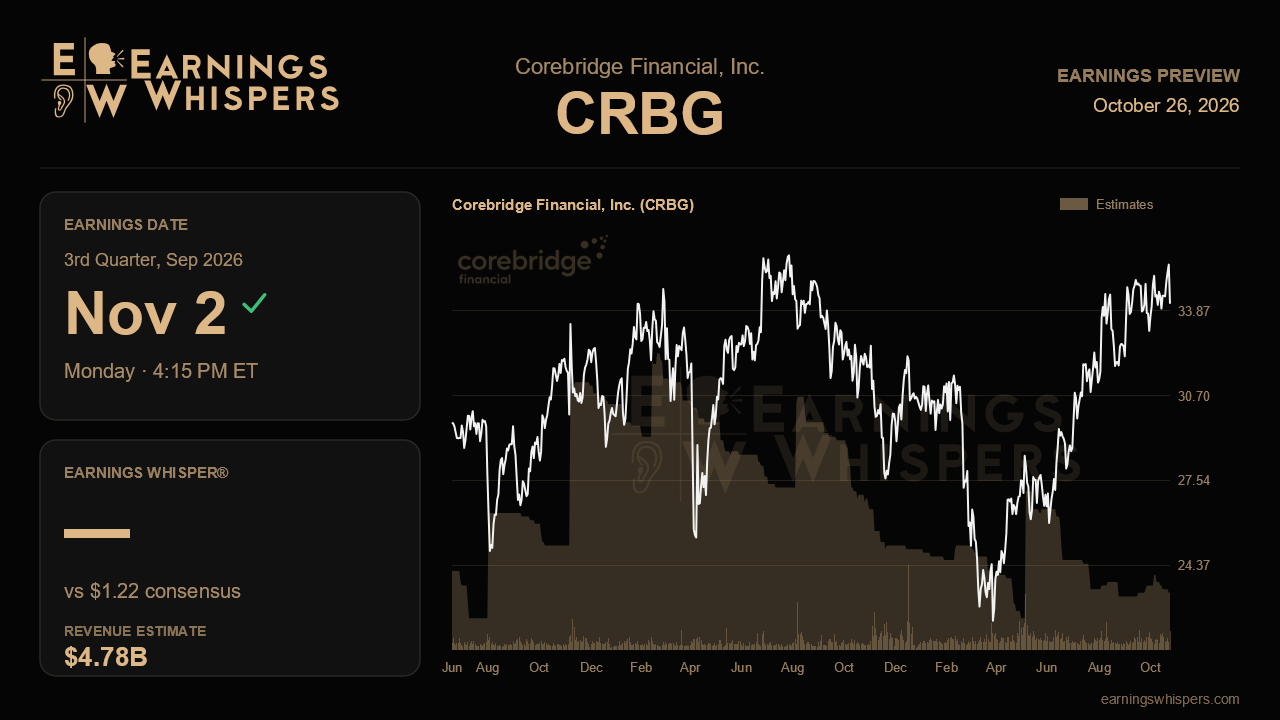
The Street expects earnings of $1.22 per share, up about 27% from $0.96 a year ago and ahead of the $1.12 reported last quarter. Revenue is forecast at $4.78 billion, roughly 15% below the year-ago $5.63 billion. That gap is less alarming than it looks. Reported revenue at a life and retirement company can swing with reinsurance transactions, divested blocks and accounting marks, so top-line contraction alongside strong per-share growth is not a contradiction. The company did not provide a fresh numeric outlook beyond its standing framework, so the useful yardstick is management's own run-rate commentary. Last quarter, run-rate EPS reached $1.35, up 16% and accelerating for a third straight period. Consensus sits well below that level, which suggests analysts have already priced in the drag from below-target variable investment income that management flagged for the rest of the year.
That alternatives guidance is the first swing factor. Management blamed weak private equity marks on worries about AI valuations, geopolitical tension and a backlog of unrealized exits. If fund marks improved during the summer, Corebridge could clear the bar with room to spare. If they stayed soft, the burden shifts to the core spread and fee engines. On that front, base spread income guidance of roughly $2.55 billion has been held flat across four straight calls, with compression expected through year-end. Another quarter of stability would validate that view. Any slippage below the trajectory would raise uncomfortable questions just before the merger closes.
Institutional markets is where the bullish case lives. Its adjusted pretax operating income growth jumped from 8% to 15% to 36% over the past three quarters, and management said guaranteed investment contract and funding-agreement balances make up only about 5% of the general account, versus 10% to 15% at peers. With the pension risk transfer pipeline described as weighted toward the second half, a strong deal tally and another quarter of GIC issuance above $1 billion would confirm that the momentum is real rather than lumpy. Individual retirement is the counterweight. Sales slipped to $3.8 billion from $4.3 billion amid tougher competition in simpler annuity designs, though management pointed to a strong June and continued strength in July. A rebound toward the prior run rate would ease concerns about pricing pressure. Group retirement, still declining but improving, needs to keep narrowing its losses as the shift from spread to fee income proceeds, and the life segment must show that last quarter's favorable underwriting was not a one-off.
The market has already leaned in. Shares have gained 8.3% since the last report while the S&P 500 fell 2.1%, and sentiment has edged up modestly to 23.7% bullish from 21.3%. At $34.13, the stock sits comfortably above its 200-day average near $29.71 and within about 4% of its post-earnings high of $35.64, not yet testing a breakout but trading near the top of a range that has shifted well above last quarter's. Much of that strength likely reflects merger confidence, which limits how much a clean quarter can add while leaving room for disappointment if the core weakens.
The central question is whether institutional and fee growth can keep run-rate earnings expanding despite a soft alternatives backdrop and flat spread income. If they can, Corebridge reinforces the case behind the reaffirmed 2027 combined targets of $5 billion in earnings and 15%-plus ROE. If retail sales stall again and investment income disappoints, the merger story will carry more of the weight on its own.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 11 hours | |
| Oct-16 | |
| Oct-12 | |
| Sep-30 | |
| Sep-16 | |
| Sep-01 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-27 | |
| Jul-24 | |
| Jul-14 | |
| Jul-09 | |
| Jul-02 |
