Clorox's Kingsford Blip And $200 Million Inflation Bill Test A Fragile Recovery
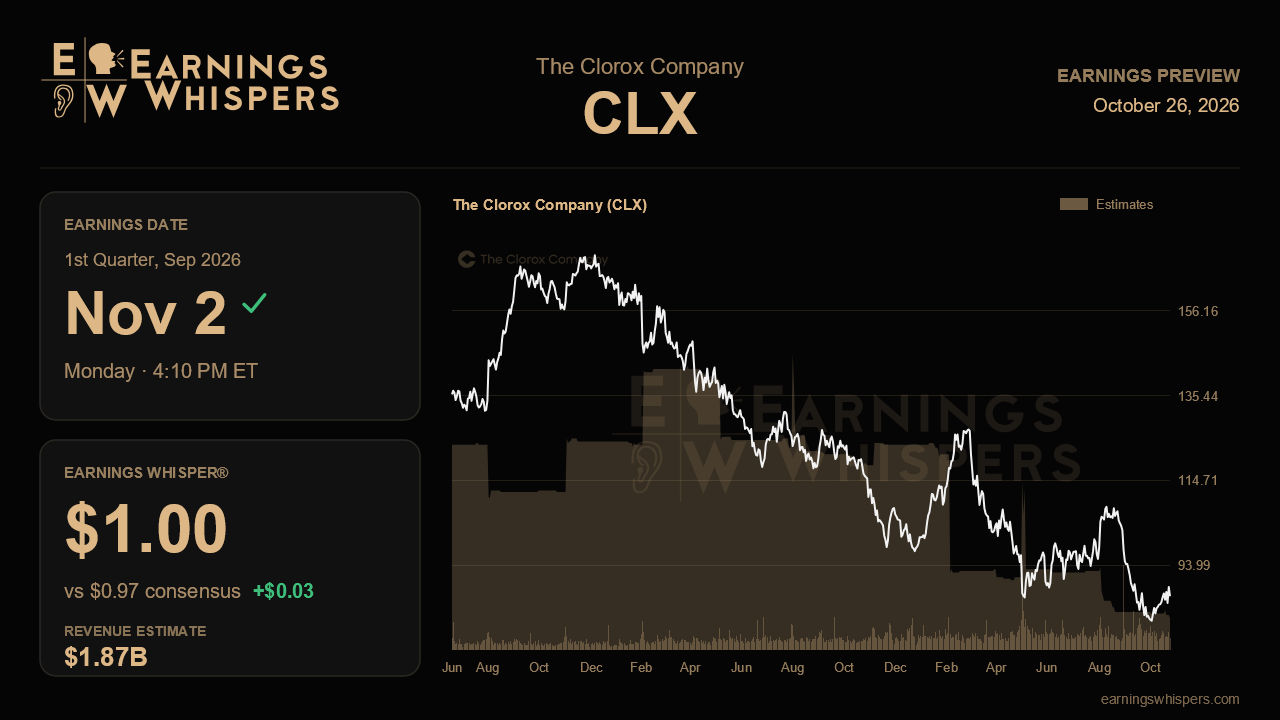
Clorox heads into its fiscal first-quarter report with a split personality. Operationally, the business looks healthier than it has in two years, with share losses from last year's botched ERP rollout fading and the Purell acquisition running ahead of plan. Financially, management has already warned that this quarter will be a soft one, weighed down by a weak charcoal season and an inflation bill that lands heaviest in the first half of the year. The question on November 2 is whether the expected soft spot stays contained or turns into something worse.
Wall Street expects earnings of $0.97 per share on revenue of about $1.87 billion. Those numbers look robust on paper, implying roughly 14% earnings growth and nearly 31% revenue growth from a year ago. Context matters. The revenue jump largely reflects the addition of GOJO, the maker of Purell, while management has guided organic sales only flat to slightly positive for the year, with volumes expected to decline. The earnings comparison is also flattered by a year-ago quarter that was hobbled by ERP-related out-of-stocks. The Earnings Whisper of $1.00 sits only a few cents above consensus, a modestly higher bar but hardly a sign that anyone expects a blowout.
The more telling tension lies in the full-year outlook. Clorox guided fiscal 2027 earnings of $5.70 to $6.00 per share, yet consensus sits at $6.03, just above the top of that range. On revenue the picture flips: management's $7.59 billion to $7.66 billion outlook sits above the Street's $7.42 billion. In other words, analysts are betting on better profitability on less revenue than the company itself projects. That gap leaves earnings forecasts exposed if the cost picture proves as heavy as management warned, and it makes any reaffirmation, narrowing or trimming of the EPS range a key part of this report.
Cost is the swing factor. Management flagged more than $200 million of inflation for the year, more than double its historical norm, driven by oil assumed near $90 a barrel along with freight, trucking and supplier costs. That load pushes gross margin toward roughly 42% and won't fully ease until the back half. A first-quarter gross margin that holds up better than feared would validate the view that the guidance was built with cushion. A sharper squeeze, particularly if paired with a Kingsford shortfall deeper than the flagged timing blip, would challenge it. The GLAD price increase tied to resin costs is an early test of whether targeted pricing can offset inflation without denting volumes, given management's deliberate restraint on broader pricing amid stretched consumers.
On the commercial side, the momentum story needs continued proof. Consumption improved sequentially through every quarter of last year, ending near flat on share, while Home Care logged eight straight quarters of share gains and both GLAD and Hidden Valley turned positive. Holding those gains, along with early evidence that GOJO is accretive as promised, would support the more confident tone management struck last quarter. Any update on the CEO search following Linda Rendle's decision to step down will also be closely parsed, as will commentary on an elevated payout ratio near 85%.
The market has not given Clorox the benefit of the doubt. Shares have fallen about 12% since the last report while the S&P 500 was essentially flat, and at $86.40 the stock trades well below its 200-day moving average of roughly $100 and in the lower part of its post-earnings range. Sentiment has softened from clearly bearish to only mildly so, suggesting expectations are subdued rather than hostile. That combination means a quarter that simply confirms the soft first half is temporary could be enough. The real verdict hinges on whether margins and the full-year outlook show that inflation is a manageable headwind rather than an open-ended one eroding a genuine operational recovery.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-19 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-10 | |
| Oct-08 | |
| Oct-08 | |
| Oct-06 | |
| Sep-28 |
